


EN
BorgWarner (BWA) Stock May Look Fully Priced Following Raised EPS Guidance
BorgWarner has delivered a strong multi‑year share price run, yet recent volatility now has investors asking whether the current valuation still lines up with the earnings the business is generating. With the stock changing hands around US$50.40 after a sharp pullback, the key issue is how that price compares with what the company actually earns.
- Over the past 3 years, BorgWarner has returned 62.0%, which puts real pressure on the question of whether the earnings profile can continue to support that kind of move.
- Recent contract wins for electric vehicle inverters, turbochargers and eMotors may support expectations for future profit streams, which feeds directly into how much investors are willing to pay for each dollar of current earnings.
- There is a second opinion on BorgWarner worth weighing. See what analysts think BorgWarner's shares could be worth.
The stock's next move may depend on whether BorgWarner's current price is justified by its earnings when judged against the Fair Ratio benchmark.
To sense check BorgWarner against others tied to electrification and power systems, compare it with the companies in the 41 power grid technology and infrastructure stocks.
Has BorgWarner Run Too Far on Earnings?
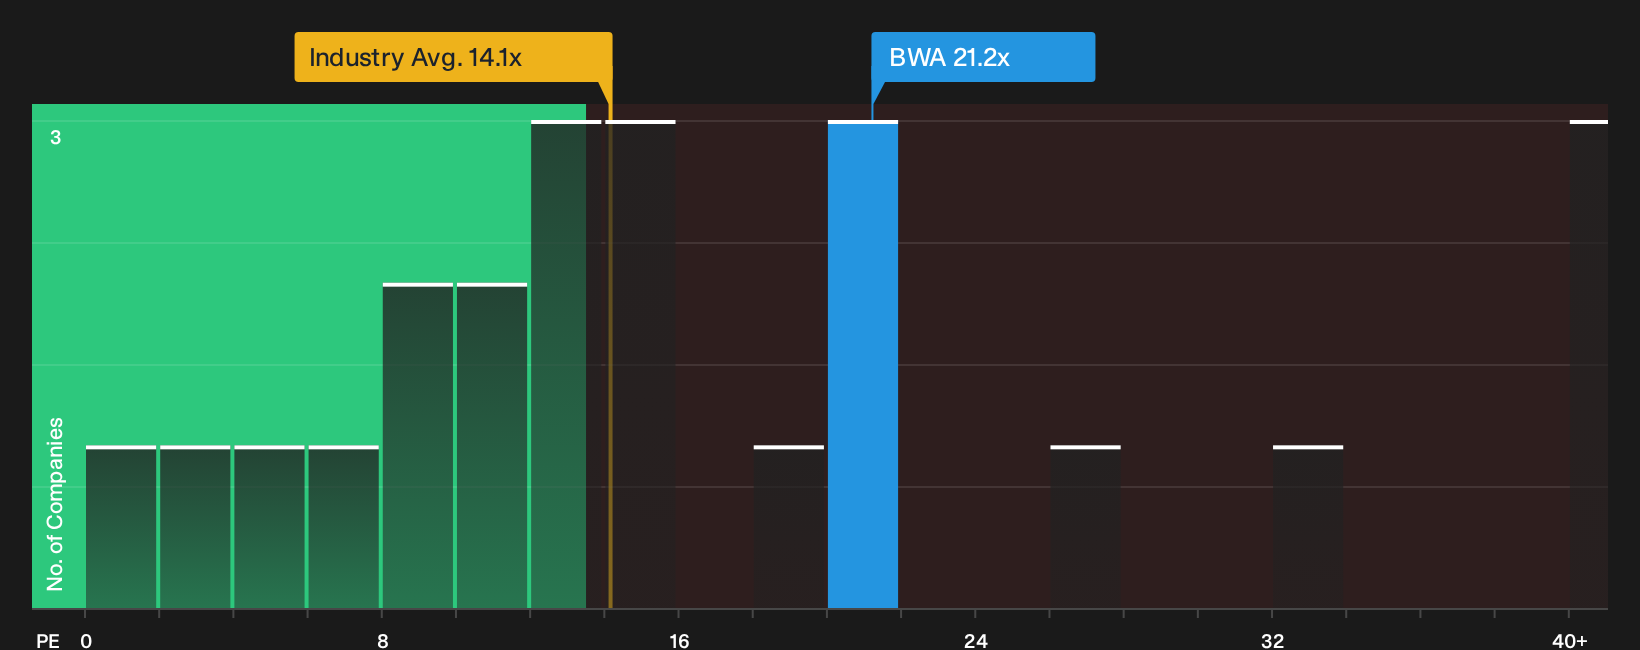
The P/E ratio is a relevant measure for BorgWarner because earnings are a central yardstick for a mature auto components supplier. At around 21.2x earnings, the stock trades above both the Auto Components industry average of 15.7x and the peer group snapshot at about 10.4x. That gap indicates that investors are paying a higher price for each dollar of current profit than they are for many comparable businesses in the sector.
The Fair Ratio model, which adjusts for BorgWarner's own margins, size, sector and risk profile, also indicates that the current P/E is elevated, so the shares appear overvalued on this basis. Despite the company raising its 2026 EPS guidance in connection with share buybacks and tax benefits, the present multiple already reflects a generous view of the earnings stream associated with those factors. Readers considering BorgWarner at this price level need to decide whether the contract pipeline and electrification wins justify paying above both sector norms and the firm specific Fair Ratio benchmark before committing new capital. Explore the numbers behind BorgWarner's P/E valuation.
The BorgWarner Narrative: What Would Justify Today's Price?
Narratives on BorgWarner pick up where the valuation puzzle leaves off, spelling out which paths for growth, profitability and earnings would need to play out for the current share price to look meaningfully high or low. Each scenario links its number to a clear view on how BorgWarner's growth, margins and risk profile might evolve. This gives you a reference point you can return to as fresh results and contract updates arrive on Simply Wall St's Community page.
One of the top community narratives on BorgWarner: 36% undervalued
"The current valuation implies the market is not fully pricing in this narrative, and views BorgWarner as undervalued while disciplined capital allocation, including sizeable buybacks, could support a higher share price over time…"
Discover why this Narrative puts BorgWarner at 36% undervalued.
Before acting on BorgWarner's valuation, one more piece of the puzzle matters
BorgWarner's price tag tells only part of the story. Separate analytical checks have highlighted potential pressure points that investors may want to scrutinise carefully before making a move. Take a closer look at 2 warning signs before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com