


EN
XPO (XPO), What Is Behind The Fresh Attention?
XPO (XPO) put fresh numbers on the board on October 29, 2026, as third quarter and year to date earnings highlighted shifts in profitability that many investors scrutinized closely.
That earnings release landed after a strong run for XPO, with the share price delivering a 35.50% year to date return to November 4 even though the 90 day share price return is down 4.22%, and the one year total shareholder return of 35.94% sits on top of a very large five year total shareholder return of 315.13%. Together, these figures point to momentum that has cooled recently but still reflects a longer stretch of confidence being priced into the stock.
Scan beyond XPO and see how other freight and logistics players stack up on profitability and momentum with the curated list of solid balance sheet and fundamentals (24 results).
The bull case highlights XPO’s higher earnings and strong year-to-date surge, while the bear case focuses on the recent pullback and elevated expectations. Which side does the current valuation actually support?
Most Popular XPO Narrative: 16% Undervalued
On this narrative framework, XPO’s fair value sits at $225.04 versus a last close of $188.06. The story leans toward upside with a clear focus on execution, capacity, and cash generation as the swing factors.
The main factor that has to go right is that XPO continues to convert higher productivity, tighter LTL capacity, and a richer mix of local and premium shipments into sustained free cash flow generation and balance sheet strength.
The current valuation suggests that the market has not fully priced in the view that XPO is undervalued relative to its record profitability, rising free cash flow, and improving leverage profile.
See why 12 investors see XPO as 16% undervalued.
Result: Fair Value of $225.04 (UNDERVALUED)
Still, XPO’s reliance on cyclical freight markets and rising labor costs could quickly challenge today’s profitability assumptions and put pressure on that case for a 16% undervaluation.
Find out about the key risks to this XPO narrative.
Another View: XPO Looks Expensive On Earnings
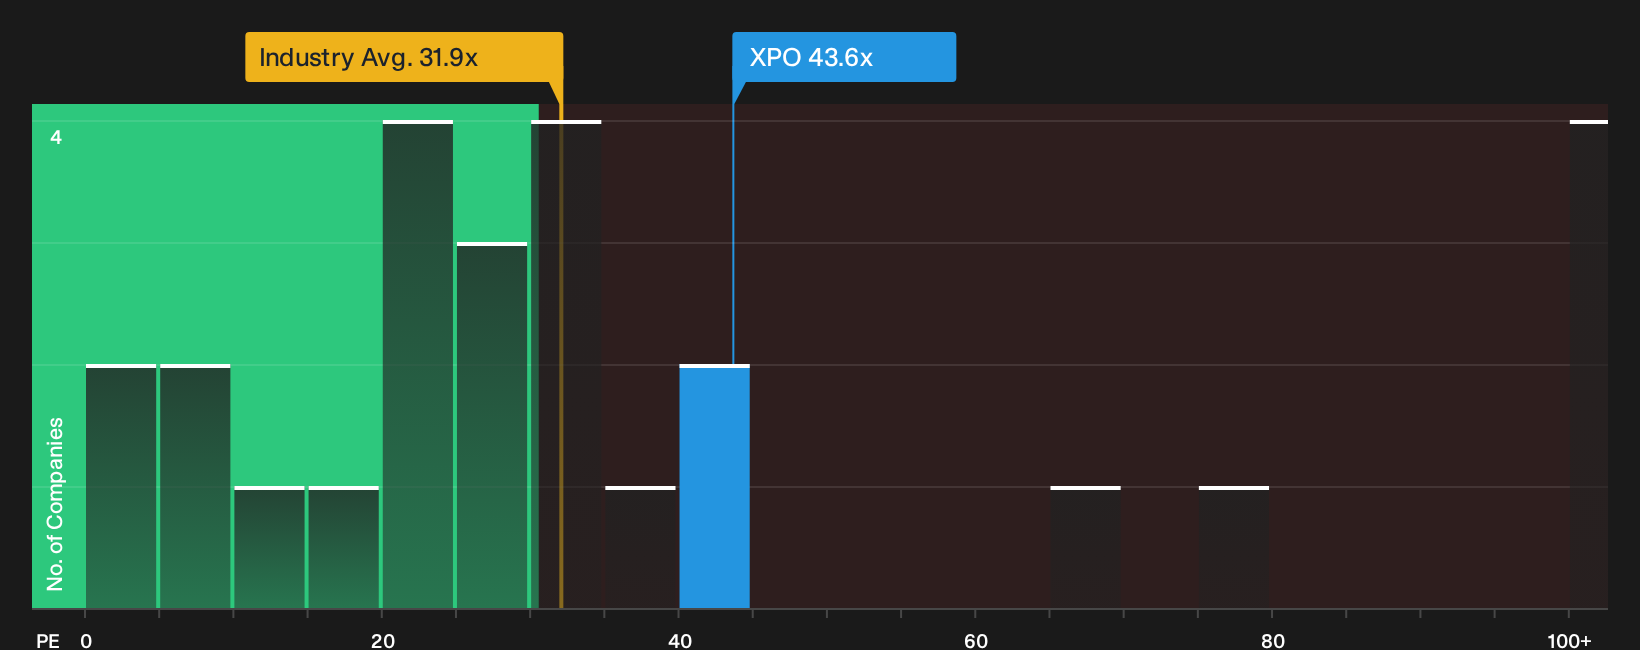
On the flip side of that fair value story, XPO trades on a P/E of 43.6x. That sits well above the US Transportation industry at 31.3x and ahead of peer levels near 28.4x, and it is also roughly double the estimated fair ratio of 21.6x.
This gap points to meaningful valuation risk if sentiment cools or earnings forecasts are revised. It raises a simple question for investors weighing XPO: is the current price already paying upfront for a lot of the good news in those forecasts?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on XPO in this piece is mixed, with optimism on profitability sitting right next to concerns on valuation and freight cyclicality. Move fast and stress test the story against your own expectations by weighing the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond XPO?
If XPO has sharpened your focus on what matters, do not stop here. Broaden your watchlist with ideas filtered for quality, value, and resilience.
- Target potential mispricings by scanning companies that screen as high quality yet out of favor through the 35 high quality undervalued stocks.
- Build a steadier income stream by reviewing businesses that qualify as 5 dividend fortresses with robust payouts and yield support.
- Reduce portfolio shock by focusing on companies that pass strict stability checks using the 31 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com