


EN
Is Sezzle (SEZL) Undervalued Following Strong Q3 Results And Its Bank Charter Bid?
Sezzle (NasdaqCM:SEZL) is back in the spotlight after reporting third quarter sales of US$166.5 million and net income of US$47.83 million, along with its recent Sezzle Bank charter application.
Recent trading has reflected that excitement. Sezzle’s 1-day share price return of 11.65% on the latest close at US$136.69 comes on top of a 23.31% 30-day share price gain, even though the 90-day share price return is down 23.44% after a strong year-to-date move of 109.81% and a very large 3-year total shareholder return that sits in the tens of multiples. This suggests that momentum has been rebuilding in the short term after a sharp pullback.
Scan beyond Sezzle and see how other fintech and specialty finance stocks compare in our hand picked 19 high quality undiscovered gems.
After that kind of swing, the real tension for Sezzle is simple. Does fair value sit closer to the current US$136.69 price, or to the far higher analyst and intrinsic estimates ahead?
Most Popular Narrative: 27% Undervalued
On the numbers, the leading Sezzle narrative pegs fair value at $187.88 per share against the latest $136.69 close. This points to a sizeable valuation gap that bullish investors are watching closely.
On a two-stage model running 10 years of +25.0% growth that then fades to a 2.5% terminal rate, discounted at 14.5%, the shares are worth USD 187.88 against a market price of USD 111.38, a 41% discount, or +69% to fair value.
The business earns 52.4% on invested capital with a 40.4% operating margin on 74.6% gross margins. Of USD 531.89M in trailing revenue, 61.6% converts to free cash flow, and the balance sheet carries debt at 0.52 times equity.
See why 3 investors see Sezzle as 27% undervalued.
Result: Fair Value of $187.88 (UNDERVALUED)
Still, the Sezzle narrative hinges on assumptions that can break, including aggressive 25% growth inputs and any future data or SEC filing discrepancies flagged by the author.
Find out about the key risks to this Sezzle narrative.
Another View On Sezzle’s Valuation
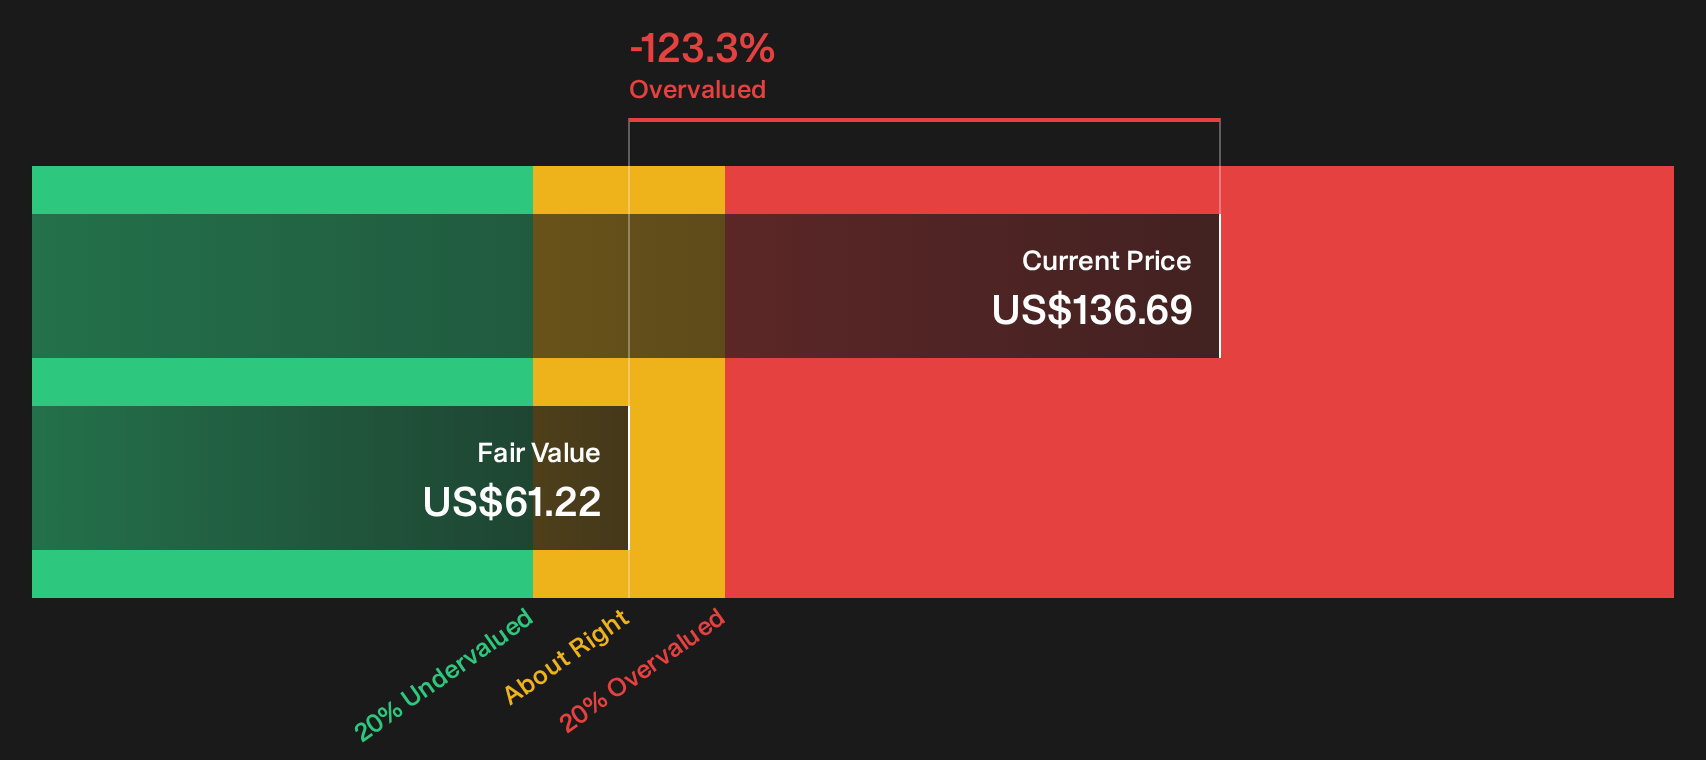
The SWS DCF model tells a very different story to the popular Sezzle narrative. On those future cash flow assumptions, fair value lands at $61.22 per share, well below the current $136.69 price, which implies the stock screens as overvalued on this framework. Which lens do you trust more for the next move?
To see how that cash flow based view is built line by line, Look into how the SWS DCF model arrives at its fair value.
Next Steps
Sentiment on Sezzle is clearly split, and that is exactly when your own homework matters most. Move quickly, review the underlying figures, and carefully consider both the 3 key rewards and 2 important warning signs.
Looking for more Sezzle sized investment ideas?
Do not stop with Sezzle. Put that curiosity to work, because some of the most compelling opportunities often sit just outside the headlines you already know.
- Target dependable income streams by reviewing a hand picked group of higher yielding payers in the 5 dividend fortresses.
- Filter for quality at a sensible price by scanning companies that screen well on valuation and fundamentals using the 35 high quality undervalued stocks.
- Prioritise peace of mind by focusing on resilient businesses that carry lower risk scores through the 31 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com