


EN
F5 (FFIV) Stock May Be Fully Priced Despite Weaker 2027 Guidance
F5 has had a strong multi‑year share price run. After a sharp pullback and fresh headlines on growth expectations, the question is whether the current valuation is still supported by the cash the business can generate.
- Over the past 3 years, the stock has returned 111.6%. This puts real pressure on the idea that existing and future cash flows are enough to justify where the price has moved.
- Recent revenue growth, alongside increased spending and a softer outlook for future top line expansion, can reshape how much cash investors expect F5 to produce and when that cash is likely to arrive.
- If you'd rather focus on earnings, this one's for you. See why F5's 25.9x P/E tells a different valuation story.
The issue now is whether the cash flows implied by F5's current share price around US$329.72 look well aligned with what the business is positioned to deliver.
If you are weighing whether F5's cash flows still square with that US$329.72 share price after the recent pullback, it can help to compare that same question across 35 high quality undervalued stocks
Is F5 Fairly Priced on Cash Flow?
The Discounted Cash Flow (DCF) model used here estimates the cash F5 can return to shareholders over time and discounts it back to today. On this view, the estimated intrinsic value comes out broadly in line with the current share price of US$329.72. This suggests the recent pullback has moved the stock closer to what its projected cash generation implies.
F5 produced about $899.3 million of free cash flow over the latest twelve months, and the model assumes that cash figure grows gradually over the coming decade rather than surging or collapsing. That pattern fits a business already producing sizeable cash, where the story is about sustaining and modestly building on that base rather than a turnround from losses. Because the weaker guidance for fiscal 2027 has already been aired, the fact that the DCF still points to value roughly in line with the current market price suggests that slower growth expectations are largely reflected in today’s valuation. Find out what F5 could be worth using our Discounted Cash Flow (DCF) estimate.
The F5 Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for F5 pick up where this valuation puzzle leaves off. They spell out which assumptions on growth, margins and earnings would need to hold for F5's stock to be worth materially more or less than it is today, and sit on the platform's Community page. Each narrative ties a specific fair value to a clear story about F5's potential catalysts and key risks so you can track which version of events appears to be unfolding over time.
Community views on F5 split between those who see more upside in the multicloud and AI story and those who worry the recent setup still leaves room for disappointment.
Bull case: 27% undervalued
"Expanding AI related use cases, including roughly US$50 million of direct AI bookings in the first half of FY26 and multi million dollar deals around AI data delivery, runtime security and AI factory load balancing, together with indirect AI driven traffic on existing estates, can support continued growth in systems and security revenue..."
Discover why this Narrative puts F5 at 27% undervalued.
Bear case: 6% overvalued
"Reliance on hybrid multicloud architectures increases operational complexity. If enterprises consolidate vendors or shift to more cloud native alternatives, F5 could see pressure on product revenue growth and renewal rates, which would weigh on overall revenue and earnings..."
Explore why this Narrative puts F5 at 6% overvalued.
For F5, the share price is only one piece of the decision
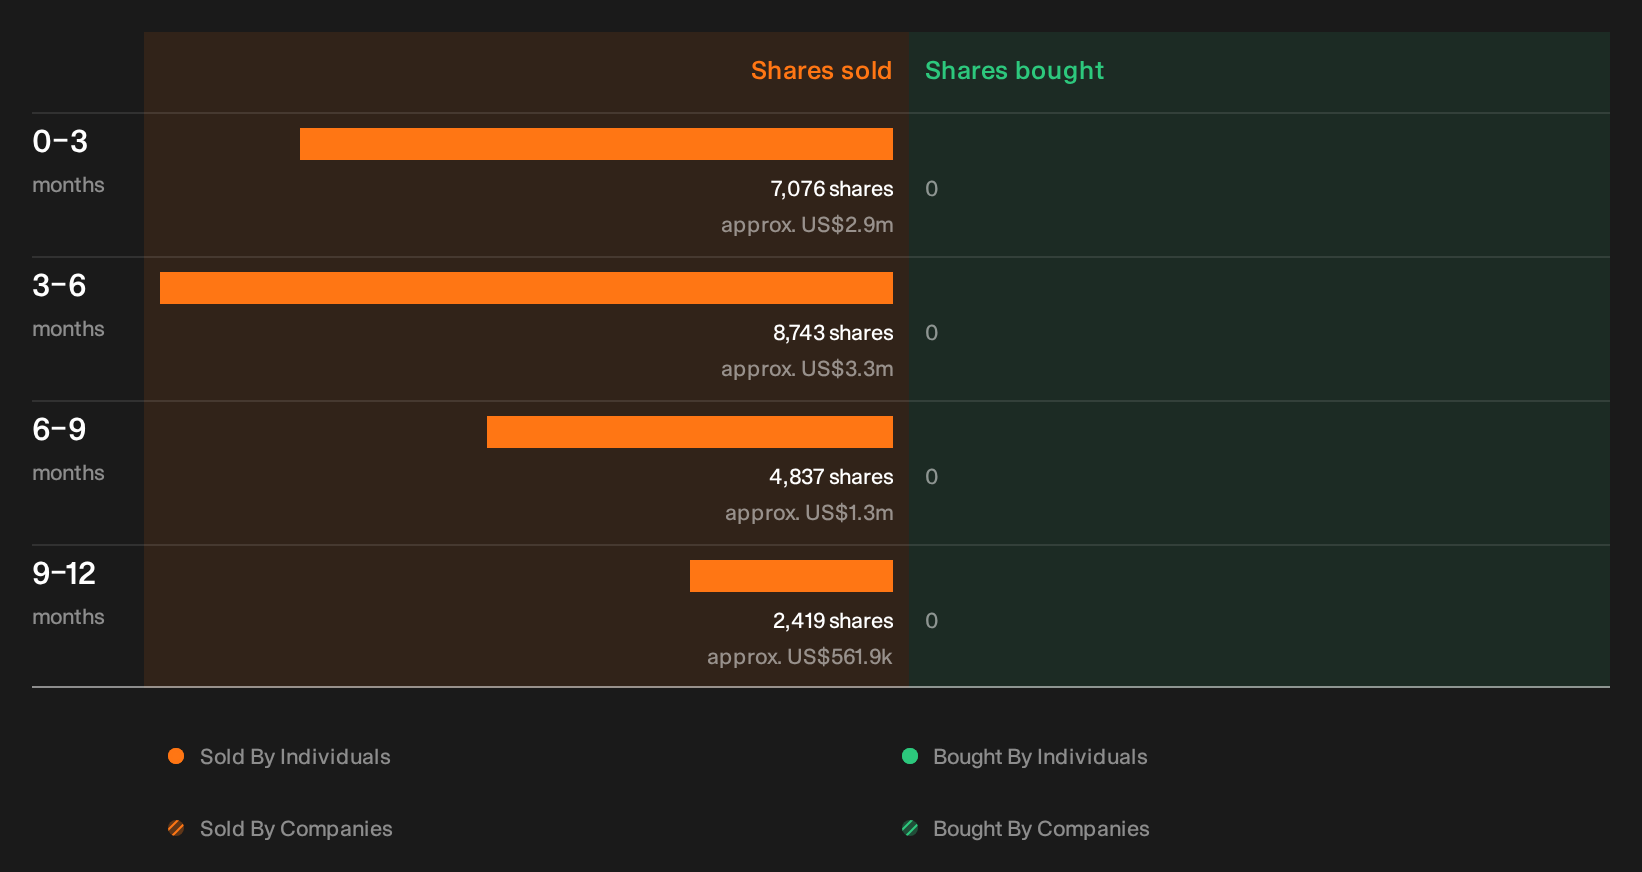
Valuation models and growth stories tell part of the story, but recent trading by people inside F5 can send its own signal, with the sellers, sizes and possible read across left for you to inspect. See the recent insider selling flagged for F5.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com