


EN
Power Integrations (POWI) Returns To Profit While Valuation Questions Linger
Power Integrations (POWI) just put fresh numbers on the table, reporting third quarter sales of US$125.48 million and a net income of US$18.32 million, compared with a loss in the same period a year earlier.
Power Integrations shares trade at US$46.80, with the 30 day share price return down 13.91% and the 90 day move lower by 20.65%, even though the year to date share price return is up 25.47% and the 1 year total shareholder return is 20.28%. This suggests that recent momentum has faded despite a recovery over the past year.
See how Power Integrations compares to other chip makers facing pressure from recent pullbacks and earnings resets with our curated list of 41 power grid technology and infrastructure stocks
The recent slide in Power Integrations after a return to profit raises a sharper issue. Are investors reassessing the business, or did sentiment simply swing too far, too fast ahead of current valuation levels?
Most Popular Narrative: 35% Undervalued
On the most followed valuation view, Power Integrations screens as undervalued, with a fair value estimate of $71.75 against the last close at $46.80, pointing to a wide gap that hinges on how the higher voltage product roadmap plays out.
Power Integrations' proprietary high-voltage GaN technology, now extending from 750–1700 V up to 2,200 V and reaching into applications that have used silicon carbide, supports premium positioning in higher power systems and has the potential to lift average selling prices and gross margins.
AI data center power opportunities, including auxiliary supplies for NVIDIA’s 800 V racks using 1,700 V InnoMux-2 ICs and a longer-term path into the main GPU power stage within a serviceable data center market sized at about US$1b by 2030, set up new content drivers for revenue and earnings.
See why 10 investors see Power Integrations as 35% undervalued.
Result: Fair Value of $71.75 (UNDERVALUED)
Still, a very high P/E, ongoing insider selling, and heavy exposure to tariff-sensitive consumer appliances could quickly undercut the bullish Power Integrations narrative.
Find out about the key risks to this Power Integrations narrative.
Another Take On Power Integrations’ Valuation
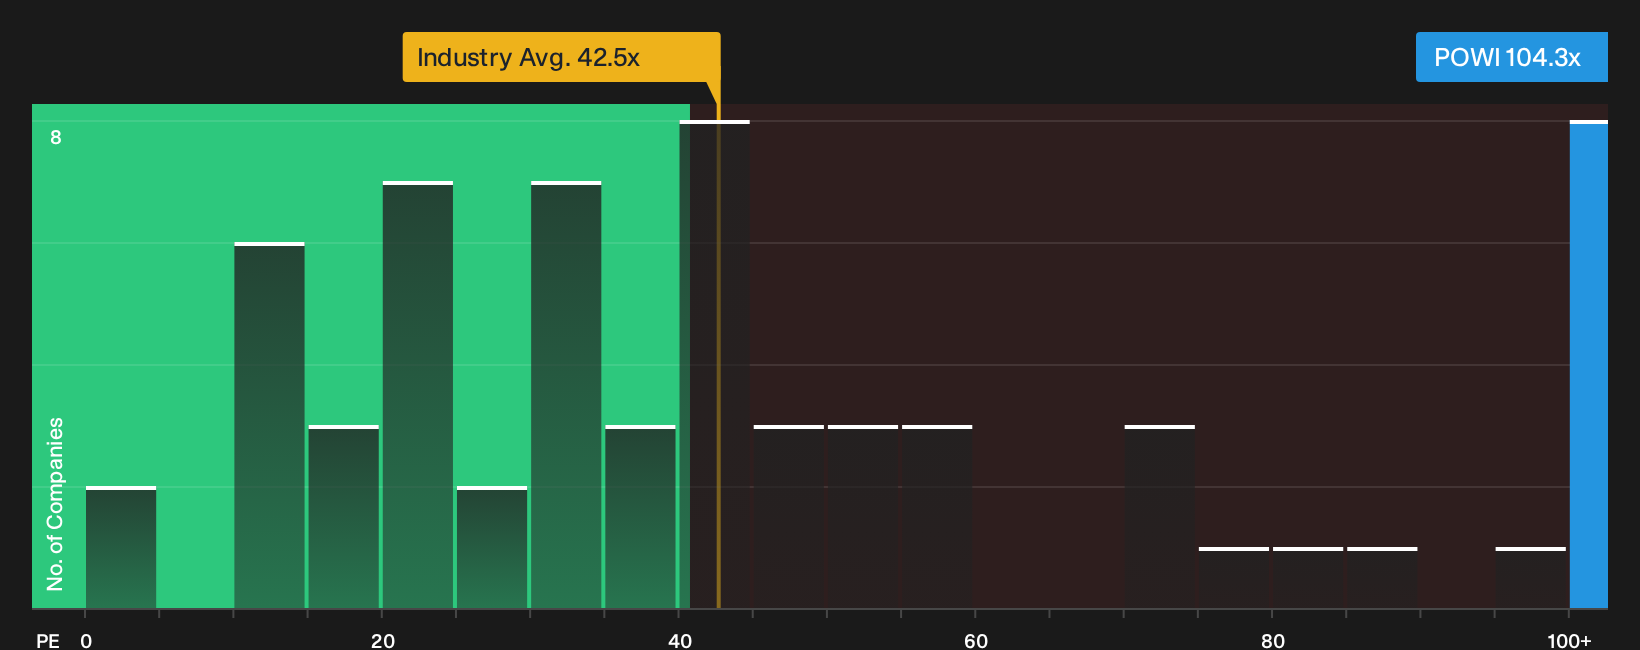
The bullish fair value of $71.75 leans heavily on analyst forecasts. Viewed another way, the current P/E of 104.3x compared to the US Semiconductor industry at 43.5x and a fair ratio of 41.3x suggests that Power Integrations is trading at a premium. If the market moves closer to that fair ratio, where does that leave today’s optimism?
For a closer look at what the numbers imply for valuation risk and potential upside compression, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages run through the Power Integrations story right now. Consider acting promptly, reviewing the underlying data, and weighing both the upside and the red flags by checking the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Power Integrations?
If Power Integrations has you thinking harder about where to put fresh capital, do not stop here. Broaden your watchlist and keep your options open.
- Target resilience by scanning companies that combine strong finances with measured risk using the 31 resilient stocks with low risk scores.
- Hunt for quality at a discount by reviewing the 19 high quality undiscovered gems before other investors start paying attention.
- Strengthen your core holdings by focusing on businesses with robust balance sheets through the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com