


EN
Happen (HAPN) Could Be 33% Undervalued Following Higher 2026 Profit Guidance
Why Happen’s latest quarter matters for investors
Happen (HAPN) just paired third quarter earnings with a higher full year 2026 profit outlook, highlighting AI driven efficiency gains, growing loan categories, and an active share repurchase program in a higher rate backdrop.
Happen’s one day share price return of 7.06% and 7 day share price return of 16.39% around the earnings release indicate that investors are reacting positively to the higher 2026 profit guidance and active buyback. This is occurring even though the 90 day share price return is down 15.32% and the 1 year total shareholder return is down 12.85%. The 3 year total shareholder return is a little more than triple, which points to long term holders still being well ahead despite recent volatility.
Compare Happen’s AI driven efficiency story with other financial stocks that pair earnings power with disciplined risk, starting with our curated 31 resilient stocks with low risk scores for potential candidates.
A 7% jump in Happen after a weak year for the stock raises a simple tension: Is the market waking up to sturdier earnings power, or just swinging with sentiment as guidance and buybacks hit the headlines?
Most Popular Narrative: 33% Undervalued
At a last close of $16.69 against a widely followed fair value of $24.75, Happen is framed as materially undervalued, with that gap rooted in the durability of its hybrid marketplace bank model and credit discipline story rather than short term trading swings.
Happen is still rolling out and deepening its digital marketplace bank model, which lets it shift loans between marketplace sales and the growing deposit funded balance sheet. The recent records in net interest income of US$179 million and a 6.1% net interest margin point to further potential contribution to revenue and earnings as this mix optimizes over time.
See why 25 investors see Happen as 33% undervalued.
Result: Fair Value of $24.75 (UNDERVALUED)
Still, Happen’s slowest revenue growth versus peers and the deeply negative cash flows in 2025 and early 2026 could challenge confidence in that undervaluation story.
Find out about the key risks to this Happen narrative.
Another View: What Happen’s P/E Is Really Telling You
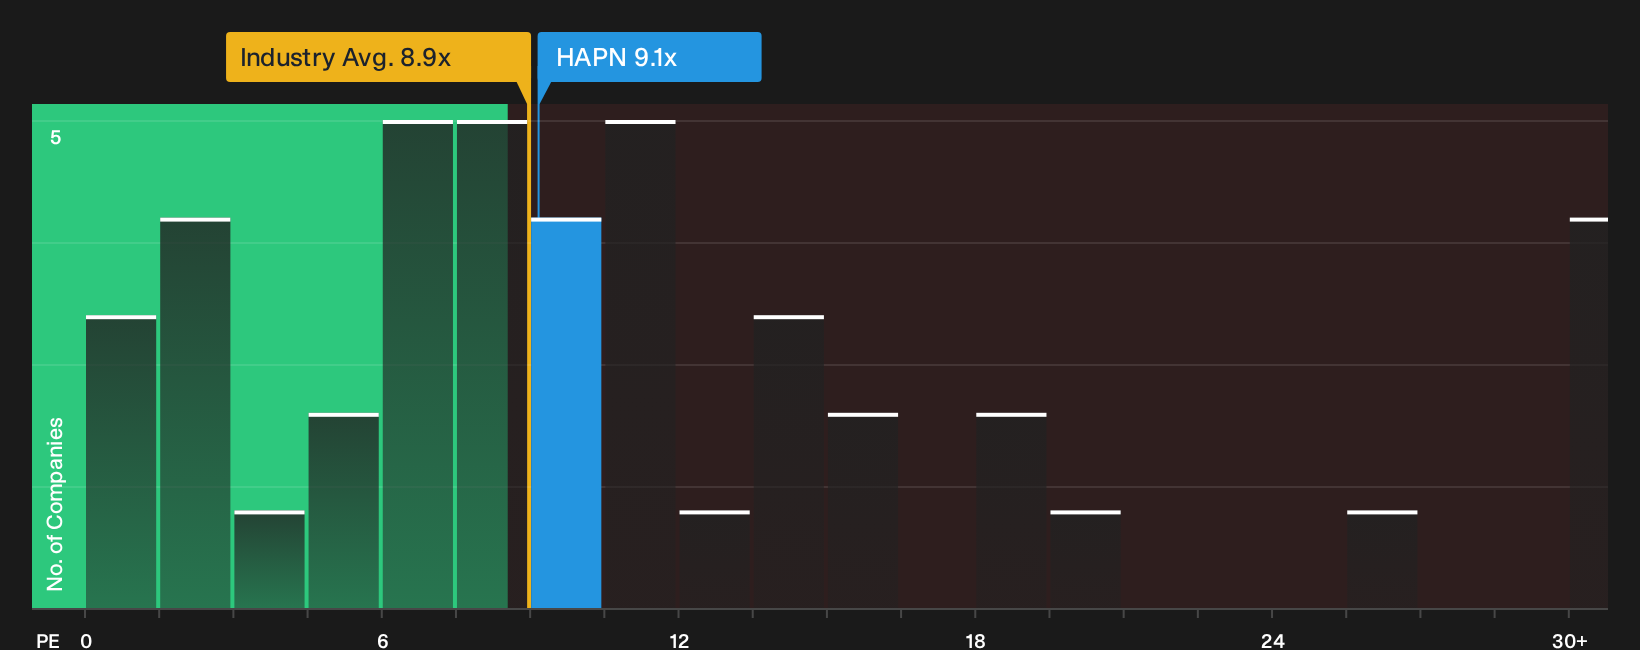
The first valuation story on Happen leans on a fair value of $24.75 and a wide gap to today’s $16.69 share price. A simple P/E check tells a quieter story, with the stock at 9.1x earnings compared with 8.5x for the US Consumer Finance group and a fair ratio of 15.3x.
That means Happen screens a bit more expensive than the wider industry on today’s earnings, yet still well below where the fair ratio suggests the multiple could move toward if sentiment changed. Is that gap a cushion or a signal that expectations already carry more risk than they appear to at first glance?
See what the numbers say about this price, find out in our valuation breakdown.See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Happen invite debate, so move quickly, review the underlying numbers, and weigh both the 1 important warning sign and the 4 key rewards in 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Happen?
Happen’s setup is only one angle. Cast a wider net now, so you are not relying on a single stock when the next opportunity appears.
- Target quality at a discount by scanning a curated pool of undervalued opportunities through 35 high quality undervalued stocks. These already combine solid fundamentals with attractive pricing.
- Strengthen your downside protection by focusing on companies with robust balance sheets. Use the list of solid balance sheet and fundamentals (24 results) to filter for financial resilience.
- Get ahead of the crowd by spotting lesser known prospects through the 19 high quality undiscovered gems before they attract broader attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com