


EN
Is Ryanair Holdings (ISE:RYA) Still Undervalued As Fuel Costs And Softer Fares Cloud Guidance?
Ryanair Holdings (ISE:RYA) just paired fresh traffic and earnings updates with a new capital return plan, as higher unhedged jet fuel costs and softer fares weighed on recent profitability and clouded forward guidance.
Ryanair Holdings has seen sharp short term momentum, with a 1 day share price return of 5.98% and 7 day gain of 11.59%. The share price is still down 14.71% year to date, while the 3 year total shareholder return of 61.09% points to a materially stronger longer term picture. This suggests the latest earnings, buyback and dividend moves are being weighed against higher fuel exposure and softer fares as investors reassess both upside potential and risk. Capitalize on Ryanair Holdings' fuel and fare reset by lining it up against hand picked 195 high quality undervalued stocks that also pair solid balance sheets with compressed expectations.Bulls point to resilient traffic, a fresh €800 million buyback and rising dividends. Bears focus on thinner profits, unhedged fuel and softer fares. Which side does the current valuation of Ryanair Holdings lean toward?
Most Popular Narrative: 11% Undervalued
Ryanair Holdings closed at €25.33 against a widely followed fair value estimate of about €28.57. The current quote sits at a clear discount in that narrative and puts more weight on fuel and fare worries than on long term execution.
Completion of the 210 Gamechanger program by early 2026 and the phased introduction of MAX 10 aircraft from 2027 will increase seats per flight while cutting fuel burn per flight. This supports both traffic growth towards 300 million passengers and structurally higher operating margins and earnings per passenger.
See why 10 investors see Ryanair Holdings as 11% undervalued.
Result: Fair Value of €28.57 (UNDERVALUED)
Still, softer near term fares and ongoing fuel price uncertainty could pressure Ryanair Holdings' profit metrics and challenge the case for a higher valuation.
Find out about the key risks to this Ryanair Holdings narrative.
Another View: What Ryanair Holdings' P/E Is Telling You
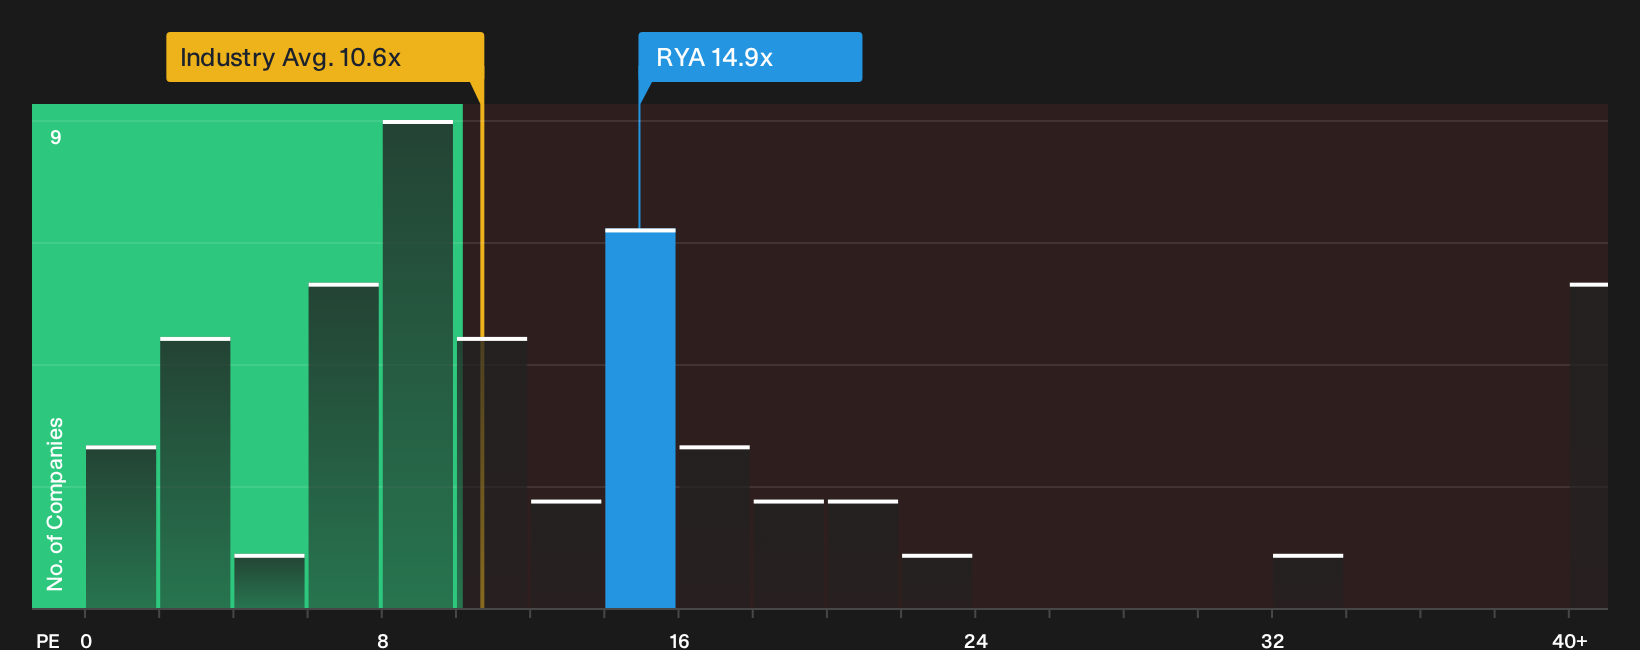
The earlier fair value work points to upside for Ryanair Holdings. The P/E picture is less generous. At about 14.9x earnings, the shares trade above both the peer average of 13.9x and the global airlines mark of 12.1x. This raises questions about how much caution is already in the price.
That gap means you are paying a higher earnings multiple for Ryanair Holdings than for many comparable carriers, even as its 1 year return has fallen short of the Irish market and the local airlines group. It puts more pressure on future execution to justify the premium. The key question is whether you think that extra multiple is comfort or risk.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages around Ryanair Holdings' valuation, fuel exposure and fare trends leave plenty of room for debate, so move fast and test the numbers against your own expectations. To see how risk and reward balance out in more detail, take a close look at the 2 key rewards and 1 important warning sign.
Ready For More Ideas Beyond Ryanair Holdings?
Ryanair Holdings gives you a clear case study in how fuel, fares and valuation all collide. Do not stop there when the wider market is full of contrasts and potential mispricings that could better suit your own risk limits and income needs.
- Target quality at a discount by scanning a curated 195 high quality undervalued stocks that pair strong financials with expectations that still look compressed.
- Build a steadier income stream by reviewing a focused 216 dividend fortresses that aim for higher yields without losing sight of balance sheet strength.
- Dial down portfolio stress by checking a hand picked 224 resilient stocks with low risk scores that screen for resilience when conditions turn choppy.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com