


EN
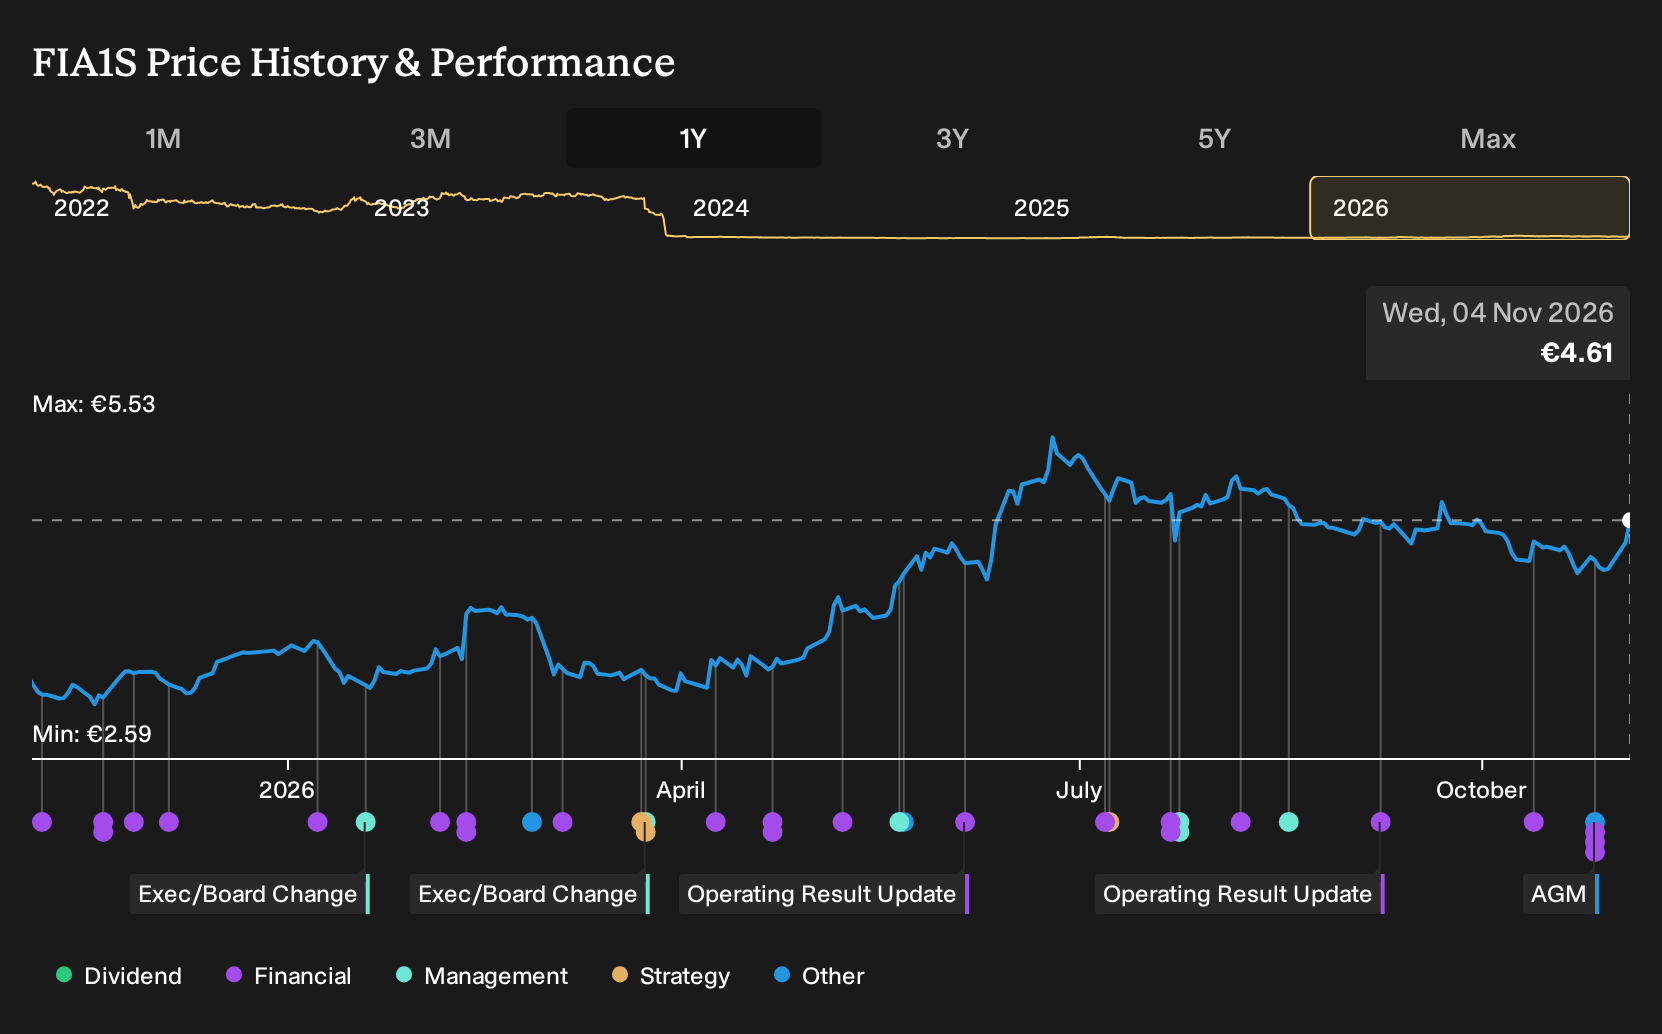
Finnair Stock In Focus After Earnings Beat And Stronger Passenger Demand
- Finnair Oyj reported third quarter 2026 sales of €953.2 million and net income of €59.1 million, and reaffirmed full year guidance for €3.5 billion to €3.6 billion in revenue with a comparable operating result of €175 million to €220 million.
- Behind these figures, Finnair Oyj recorded higher passenger volumes, a stronger passenger load factor and a return to profit over the first nine months compared with a loss a year earlier. This indicates an airline that is using its capacity and network more effectively.
- Attention now turns to how Finnair Oyj's investment narrative incorporates this reaffirmed earnings guidance and the sharper improvement in passenger load factor.
Finnair Oyj Investment Narrative Recap
To own Finnair Oyj, you need to believe the airline can keep filling more seats at acceptable yields while absorbing higher fuel and environmental costs and a sizeable fleet renewal program. The reaffirmed 2026 guidance suggests management still sees enough demand to support €3.5b to €3.6b in revenue and a comparable operating result of €175m to €220m.
The near term catalyst is execution on capacity and load factor, especially as environmental and sustainable aviation fuel costs add around €10m each per quarter. The key risk is that unit revenue or ancillary sales soften while these costs and planned CapEx towards 2029 tighten margins and reduce room for error.
The reaffirmation of full year guidance after the third quarter release is the announcement that matters most here. Finnair Oyj paired €953.2m of quarterly sales and €59.1m of net income with unchanged targets, which points to management seeing current performance as broadly aligned with its 2026 plan rather than a one off spike.
For catalysts, investors are watching whether this earnings profile can coexist with higher environmental costs, a planned 10% ASK increase in 2025 and a €2.0b to €2.5b CapEx plan tied to Embraer E2 and A321 aircraft. The risk is straightforward: if fuel or regulation driven outlays bite faster than efficiency and pricing gains, earnings volatility can rise from here.
Finnair Oyj's analyst narrative points to revenue of €3.7b and earnings of €92.3m by 2029, built on assumed yearly top line growth of 2.5% and a decline in earnings from €134.6m today to that 2029 consensus level. This implies an earnings drop of €42.3m over the period.
Uncover why Finnair Oyj's fair value indicates a 24% potential downside to its current price, leaving little room for error.
Exploring Other Perspectives
One alternative view on Finnair Oyj focuses on fuel risk rather than capacity. The most pessimistic analysts were already assuming 4.3% annual revenue growth to about €3.6b and earnings of €96.5m by 2029, yet still arrived at a €2.9 price target. These estimates all pre date the latest guidance confirmation, so you may see those storylines shift.
Explore 2 other Finnair Oyj fair value estimates, including one that suggests as much as 99% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Finnair Oyj research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Finnair Oyj. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Finnair Oyj's overall financial health at a glance.
Looking For More Ideas Beyond Finnair Oyj?
If the Finnair Oyj story has sharpened your thinking about capacity, earnings quality and balance sheet pressure, it can help to line those insights up against a broader watchlist built with the Simply Wall St Screener.
- For readers who want potential mispricing supported by fundamentals rather than hype, scan through our 195 high quality undervalued stocks and see which businesses pass tougher quality and value filters.
- If resilience matters more to you than headline growth, narrow your search to companies in the 224 resilient stocks with low risk scores that combine sturdier risk profiles with more measured return prospects.
- When capital preservation and financial strength sit at the top of your checklist, build a shortlist using the list of solid balance sheet and fundamentals (197 results) so you can focus on firms with stronger balance sheets and underlying fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com