


EN
How $500 Million Buyback Will Impact Terex (TEX) Investors
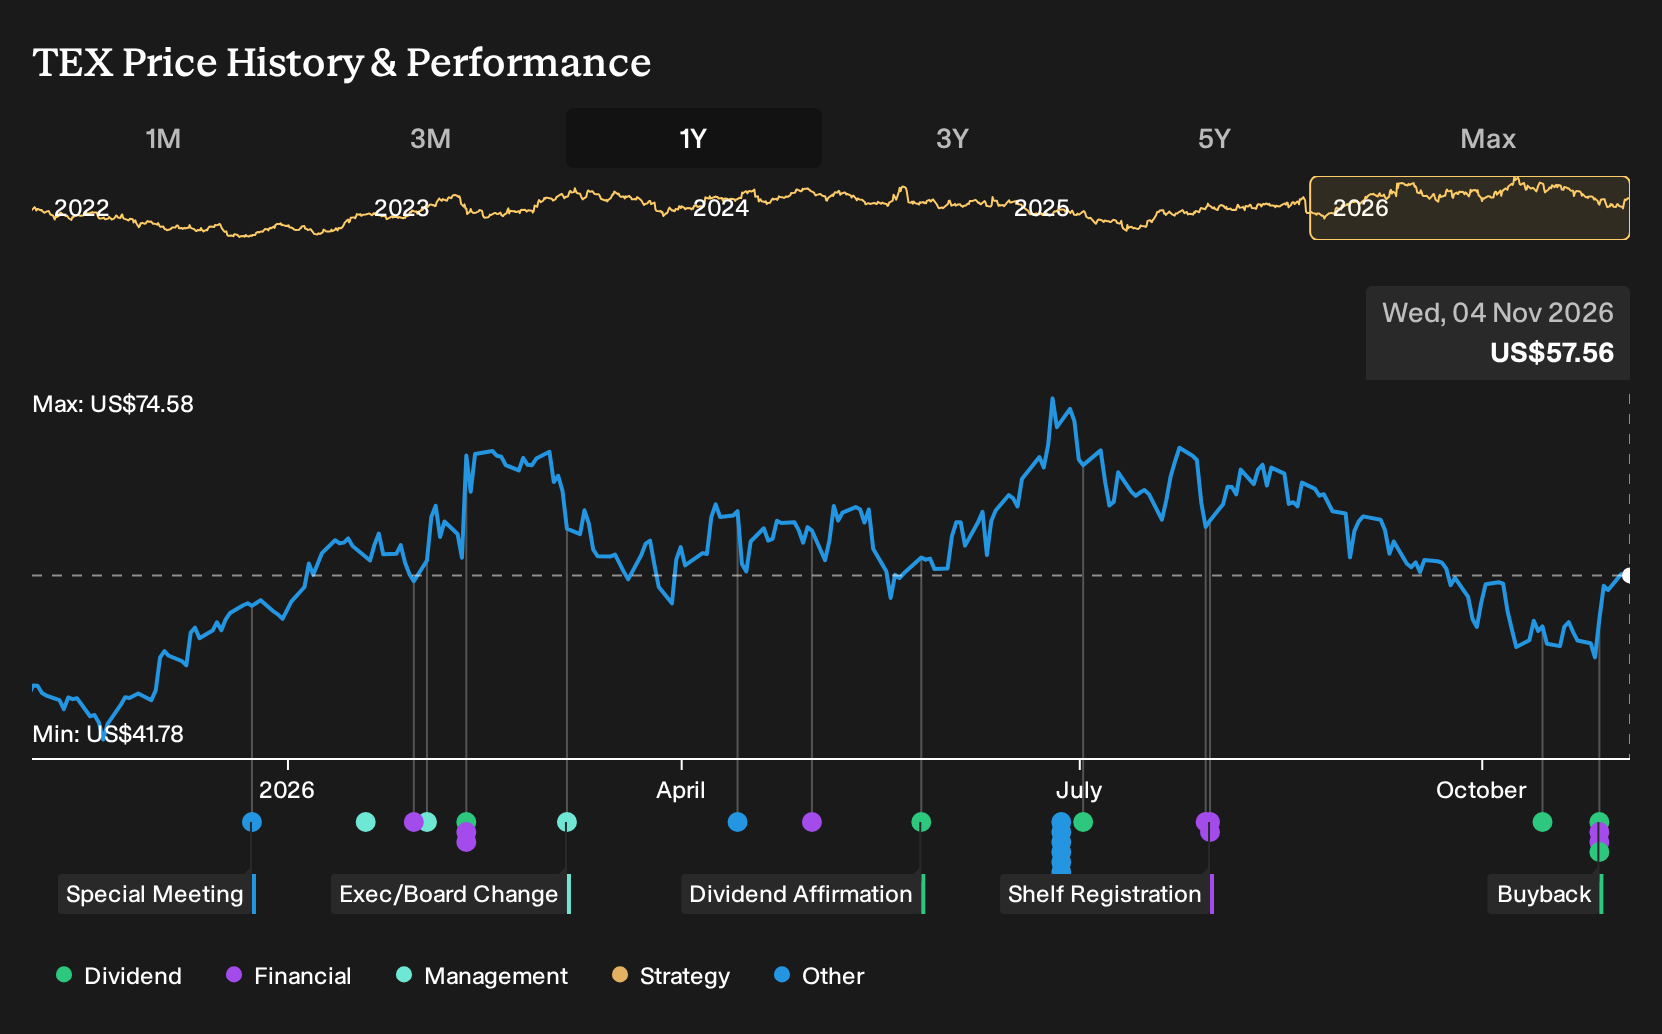
- Terex reported third quarter 2026 sales of US$2,197 million and net income of US$114 million, refined its 2026 net sales outlook to US$8.0b to US$8.2b, and announced authorization for up to US$500 million of share repurchases.
- The combination of higher year on year quarterly revenue, lower year to date net income, and a large buyback authorization highlights how Terex is balancing growth investments, earnings pressure, and capital returns.
- This article examines how Terex's refreshed earnings guidance and US$500 million buyback plan fit into the broader investment narrative.
Scan for other industrials balancing earnings guidance shifts and fresh buyback plans by checking the hand picked 35 high quality undervalued stocks alongside Terex in your watchlist.
Terex Investment Narrative Recap
For Terex, the big picture you need to buy into is pretty simple. Large infrastructure, utility and industrial projects keep needing its equipment and software, and Terex converts that demand into consistent orders, solid backlog and cleaner earnings. The refined 2026 net sales range of US$8.0b to US$8.2b keeps that narrative intact rather than resetting it.
The immediate swing factor now is margins. Third quarter revenue and earnings grew year on year, yet year to date profit is lower and Environmental Solutions carries softer second half expectations. If pricing, mix or REV integration weigh further on profitability, that is the risk that matters most in the near term.
The new authorization to repurchase up to US$500 million of Terex common stock is the announcement that ties most directly into the current setup. Buybacks amplify whatever happens to earnings per share, so execution on cost control, REV synergies and Environmental Solutions mix becomes even more important if this plan is used meaningfully.
For you as a shareholder, the combination of refined sales guidance and potential repurchases concentrates attention on cash generation and balance sheet resilience. Interest costs already receive some scrutiny and the firm relies fully on external borrowing. That makes disciplined capital allocation, and the timing and scale of any buybacks, a key catalyst to track alongside margins.
What The Terex Forecasts Really Assume
Terex's narrative projects US$9.5b revenue and US$974.5 million earnings by 2029. This relies on analysts estimating 12.5% yearly revenue growth and an earnings increase of about US$829.5 million, from US$145.0 million today to the 2029 consensus level.
Uncover why Terex's fair value points to a 39% potential upside to its current price that could narrow quickly if sentiment shifts.
Exploring Other Perspectives
One alternative angle on Terex focuses on the bullish catalyst from Environmental Solutions and Specialty Vehicles margins rather than near term earnings pressure. The most optimistic analysts were penciling in revenue of about US$10.2b and earnings of roughly US$1.0b by 2029 before this guidance and buyback news. Those forecasts show how far opinions can stretch, so it is useful to compare several narratives and decide which assumptions feel realistic to you.
Explore another Terex fair value estimate, including one that suggests potential upside of as much as 70% from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Terex research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Terex. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Terex's overall financial health at a glance.
Looking For More Ideas Beyond Terex?
If you want to stress test your thesis on Terex against a broader watchlist, it helps to line it up beside companies with different balance sheet strength, payout profiles and return patterns. The Simply Wall St Screener gives you a quick way to do that without getting buried in data.
- For investors who want income to matter as much as price moves, take a look at companies in the 5 dividend fortresses and see how their payouts compare to Terex's total return profile.
- If capital preservation is high on your list, focus on businesses in the 31 resilient stocks with low risk scores and see how their risk scores and financial footing stack up against what you see at Terex.
- When you are hunting for potential future leaders before they are widely followed, scan the 19 high quality undiscovered gems and test whether any of those fundamentals look stronger than what you are underwriting with Terex.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com