


EN
How Analyst Upgrade Will Impact Bread Financial Holdings (BFH) Investors
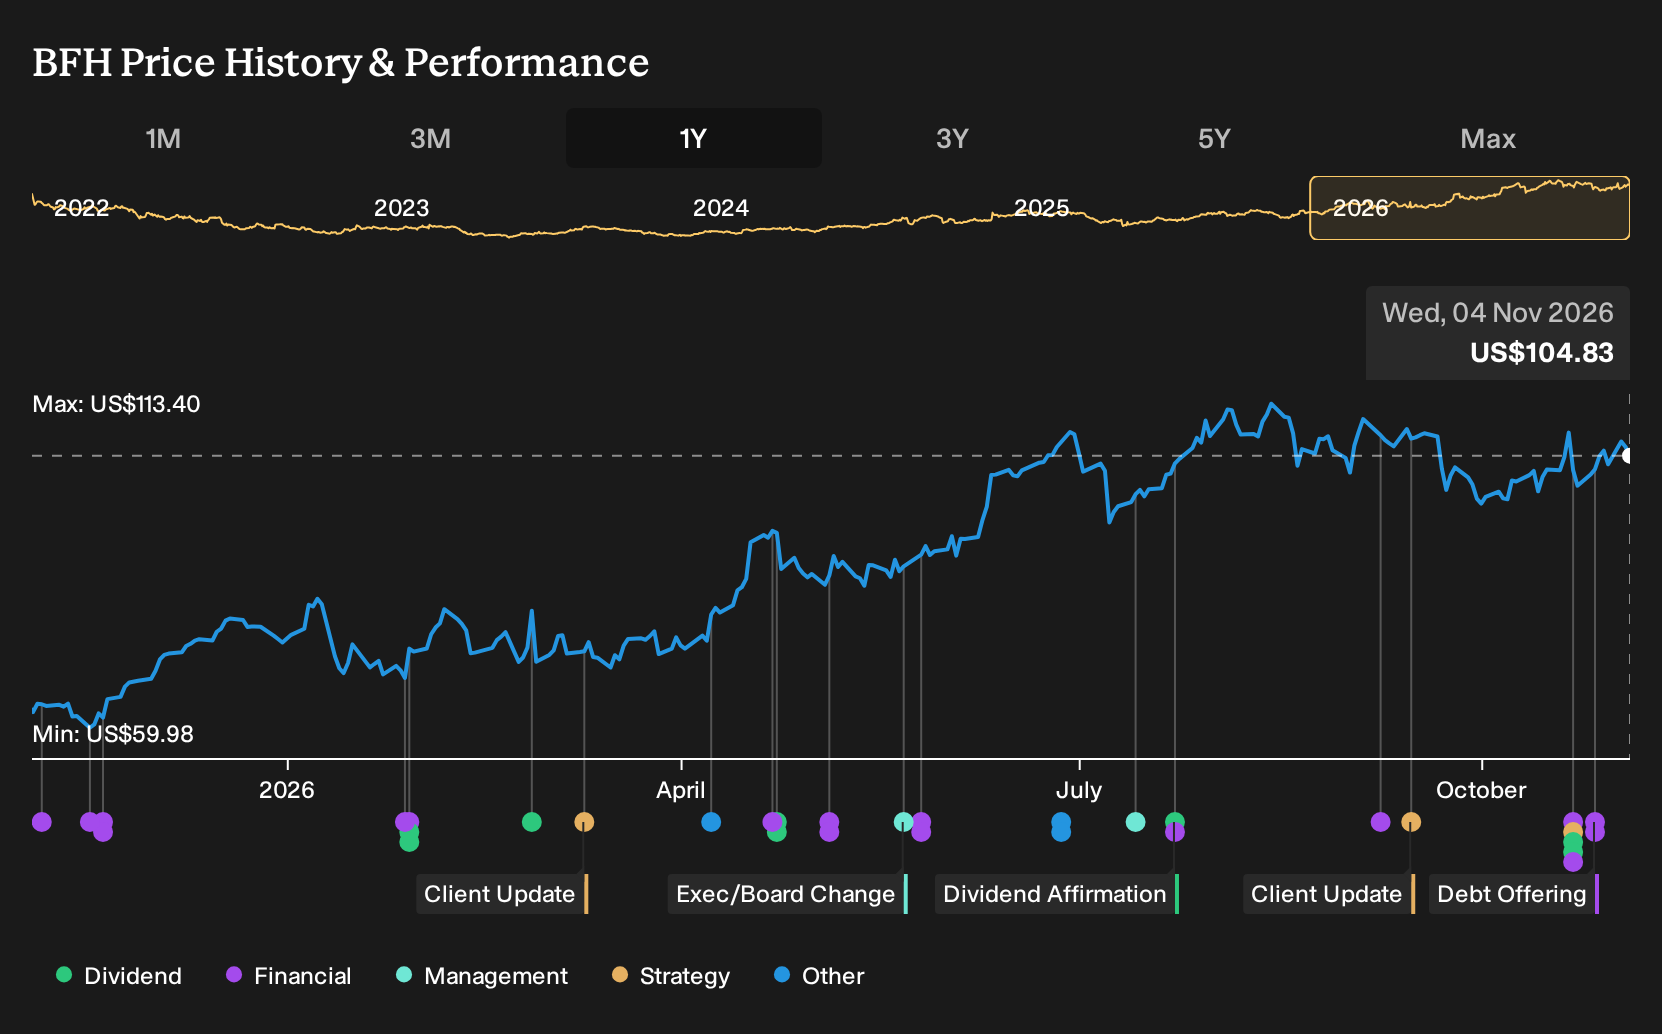
- Bread Financial Holdings has completed a US$125 million fixed income offering of 5,000,000 non convertible, callable, non cumulative perpetual preferred depositary shares at US$25 each, alongside updated 2026 guidance, renewed partnership terms with Sephora, and higher common and preferred dividends.
- The combination of fresh preferred capital, a long term Sephora renewal, and a 9% lift in the common dividend indicates that management is balancing funding flexibility with ongoing investment in co branded loyalty and credit programs.
- We will look at how Bread Financial Holdings' investment narrative is affected by the preferred issuance and related capital allocation moves.
Compare how Bread Financial Holdings' latest capital move stacks up against other lenders positioning for income-focused investors by scanning our curated 5 dividend fortresses with resilient payout profiles.
Bread Financial Holdings Investment Narrative Recap
For Bread Financial Holdings, the core view is that a tech focused card and installment lender can continue tightening credit quality while still growing loans and fee income. The preferred issuance, Sephora renewal, and updated 2026 outlook all sit against that backdrop. Management is guiding to about 5% revenue growth and a net loss rate below 7%, so execution on underwriting remains the key near term catalyst.
The main risk is that higher partner profit sharing and rewards costs, plus a mix shift toward prime customers, could compress loan yields and net interest income while loss rates stay elevated. The fresh US$125 million of perpetual preferred funding does not remove that risk. However, it can provide more flexibility if credit costs or consumer spending trends turn less helpful.
The long term renewal with Sephora appears most directly tied to the capital raise and dividend decisions. Bread Financial Holdings depends heavily on co brand and private label relationships, and this agreement underpins a high profile program where credit and loyalty are closely linked. The renewal secures a meaningful stream of credit sales volume that can support the 2026 loan growth outlook.
For you as a shareholder, the Sephora deal matters because it interacts with both the main catalyst and the key risk. Stronger engagement in that portfolio can support revenue and help absorb the expected step up in partner profit sharing. It also keeps pressure on Bread Financial Holdings to manage rewards expense, funding costs, and loss rates carefully so that headline growth does not come at the expense of returns.
Bread Financial Holdings is currently modeled to reach revenues of US$4.4b and earnings of US$519.1 million by 2029, based on analyst forecasts that include 18.0% yearly revenue growth and an earnings decline of about US$45.9 million from current earnings of US$565.0 million.
Uncover why Bread Financial Holdings' fair value indicates a 10% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One catalyst that bullish analysts lean on is capital returns. Before this preferred deal, the most optimistic group was already penciling in revenue of about US$4.8b and earnings of roughly US$593.3 million by 2029. In comparison, the more cautious view projects revenue of US$4.4b and earnings of US$519.1 million. The new preferred issuance, dividend increases, and Sephora renewal could all nudge those stories in different directions, so it is worth comparing several viewpoints before deciding how Bread Financial Holdings fits your own income and risk goals.
Explore another Bread Financial Holdings fair value estimate, including one that suggests potential upside of up to 119% from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Bread Financial Holdings research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Bread Financial Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bread Financial Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Bread Financial Holdings?
Once you have formed a view on Bread Financial Holdings, it can help to compare that thesis with other opportunities that fit different income, quality, or risk profiles. The Simply Wall St Screener lets you quickly filter for businesses that match your own checklist rather than relying on a single story.
- If you want potential income plus balance sheet strength, focus on companies with steady cash flows and low leverage by starting with this list of solid balance sheet and fundamentals (24 results).
- For investors hunting for value, widen your research to stocks that pair quality fundamentals with pricing that screens as attractive using the 35 high quality undervalued stocks.
- If capital preservation sits high on your priority list, concentrate on businesses that show fewer red flags across earnings, debt, and volatility through the 31 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com