


EN
Is Klaviyo (KVYO) Still Below Fair Value Following Its Third Quarter Earnings Beat?
Klaviyo (KVYO) stepped into the spotlight on 4 November as third quarter earnings topped forecasts, alongside year over year sales and net income improvements and fresh buyback announcements.
The recent earnings beat and fresh buyback authorisation have arrived after a sharp swing in sentiment around Klaviyo. The 30 day share price return is 27.9% and the 90 day share price return is 27.7%, even though the year to date share price return is still down 27.2% and the 1 year total shareholder return has fallen 20.5%. This points to momentum rebuilding in the short term after a tougher first stretch of 2026 as investors reassess the company in light of improving profitability and sizeable repurchase activity at a last close of US$21.36.
Compare Klaviyo's rebound with a curated set of other software and tech names showing strong fundamentals and potential re-rating using the 19 high quality undiscovered gems.
Klaviyo now trades at what looks like a steep discount to both analyst targets and some fair value estimates after the rebound. The key issue is whether that gap reflects lingering risk or an overly cautious market.
Most Popular Narrative: 19% Undervalued
Klaviyo's most followed valuation storyline points to a fair value of $26.33 against a last close of $21.36. This frames the recent rally as a partial catch up rather than a completed move.
Ongoing product expansion from a single channel email tool into a broader B2C CRM platform, with nearly 20% of ARR now coming from customers using three or more products and materially higher gross retention for multiproduct users, gives Klaviyo more scope to cross sell and lift revenue per customer while supporting more resilient margins.
See why 31 investors see Klaviyo as 19% undervalued.
Result: Fair Value of $26.33 (UNDERVALUED)
Still, the Klaviyo story can quickly look different if higher SMS and infrastructure costs keep squeezing gross margins, or if heavier AI and acquisition spending fails to lift earnings.
Find out about the key risks to this Klaviyo narrative.
Another View: Klaviyo On Sales-Based Valuation
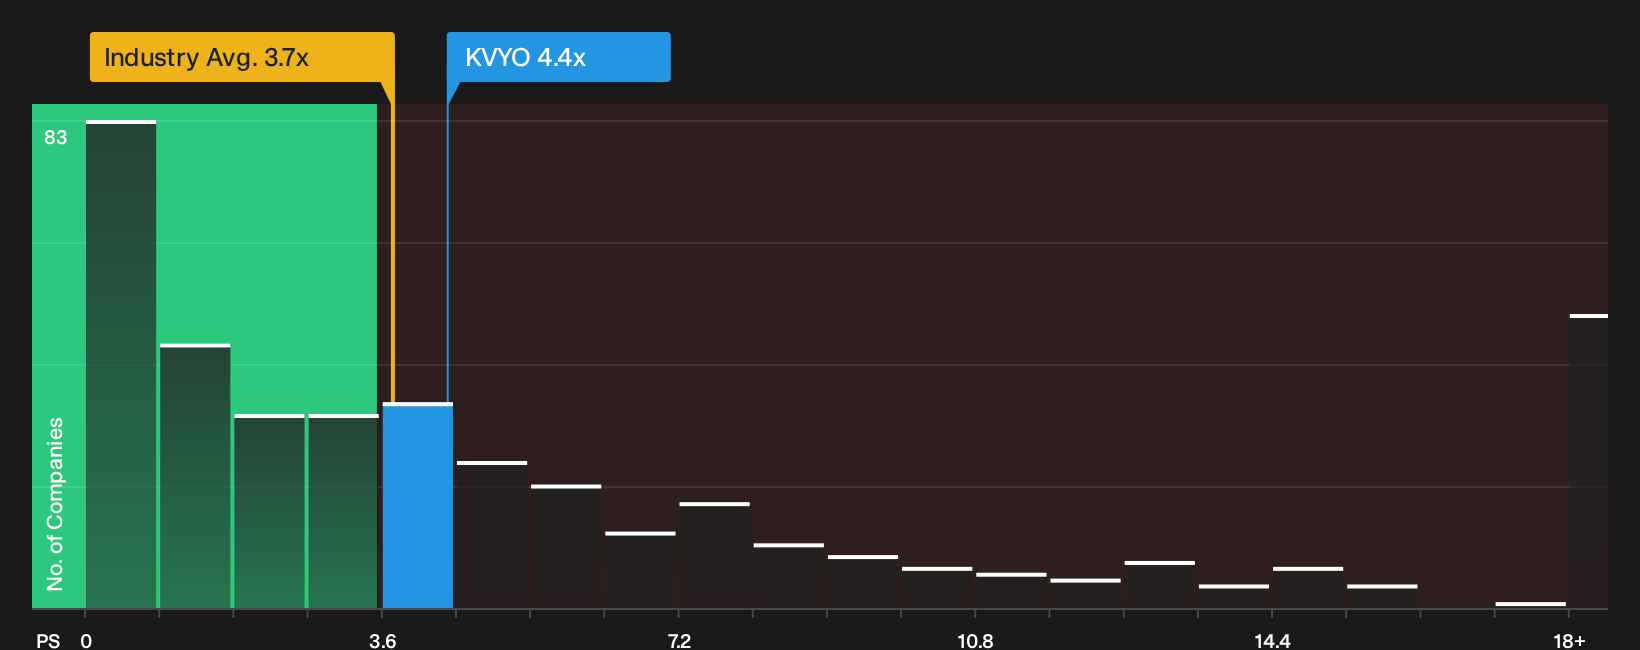
On the flip side of the fair value narrative, Klaviyo screens as expensive on a simple P/S check at 4.4x compared with 3.7x for the wider US Software industry, yet still cheap versus a 13.1x peer average and a 5.9x fair ratio that the market could move toward. That mix points to both valuation risk if sector multiples compress and potential upside if sentiment shifts back toward higher growth software, so investors need to consider which side of that trade-off they are emphasizing.
For a closer look at how this sales multiple stacks up against fundamentals and peers, take a look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages on Klaviyo can be useful if you test the data yourself and move quickly to shape an independent view. To size up both the optimism and the caution flags in one place, review the 3 key rewards and 3 important warning signs.
Looking for more Klaviyo-sized opportunities?
Do not stop with Klaviyo. Use the Simply Wall Street Screener to surface fresh ideas that match your style before the crowd focuses on them.
- Target potential mispricing in quality businesses by scanning the 35 high quality undervalued stocks that combine solid fundamentals with discounted market expectations.
- Secure income-focused ideas by filtering for companies in the 5 dividend fortresses that pair higher yields with an emphasis on durability.
- Dial back portfolio risk by concentrating on the 31 resilient stocks with low risk scores that show stronger balance sheets and fewer red flags across key checks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com