


EN
Hawkins (HWKN) Earnings Growth And Dividend Keep Fair Value In Focus
Hawkins (HWKN) just paired a fresh quarterly earnings update with another dividend declaration, giving investors new numbers on sales, profits and cash returns to shareholders to weigh against the recent share price move.
At a share price of $155.97, Hawkins has ridden a strong run of momentum recently, with a 30-day share price return of 17.94% and a 90-day gain of 20.06%. The 1-year total shareholder return of 23.74% sits on top of very strong 3- and 5-year compounding.
Scan how Hawkins fits into a wider trend of high-quality, cash generative businesses by checking the 35 high quality undervalued stocks that have also been holding up under closer earnings scrutiny.
After a sharp run to $155.97, Hawkins now sits only partway between intrinsic value estimates and a higher analyst target. Where does fair value fall within that range, and how demanding is the current price?
Price-to-Earnings of 37.8x: Is it justified for Hawkins?
Hawkins trades on a P/E of 37.8x, which is high relative to many US chemicals peers and comes after a share price around $155.97.
The P/E ratio compares the current share price with earnings per share. For a business like Hawkins that reports earnings growth and distributes a dividend, this metric helps you see how much you are paying for each dollar of profit.
Earnings have grown 11.4% per year over the past 5 years and are forecast to grow 12.16% per year. Yet the current P/E sits well above both the US Chemicals sector average of 22.9x and the peer group average of 20.3x. The market is paying a steep premium to those benchmarks, which signals that a lot of future profit expansion and stability are already reflected in the valuation and leaves less room for disappointment.
The internal fair P/E estimate sits at 17.2x, so the current 37.8x multiple is more than double that level and implies a rich pricing that could compress if sentiment or earnings expectations cool.
Explore the SWS fair ratio for Hawkins.
Result: Price-to-Earnings of 37.8x (OVERVALUED)
Still, the Hawkins story can be knocked off course if the rich P/E meets weaker earnings delivery, or if sector-wide chemicals demand softens and drags sentiment lower.
Find out about the key risks to this Hawkins narrative.
Another View On Hawkins Using Cash Flows
The earnings multiple paints Hawkins as expensive, yet the SWS DCF model lands in a very different place. On that measure, an estimated future cash flow value of $154.94 almost matches the current $155.97 price, which points to a stock that screens close to fully priced rather than stretched.
That kind of narrow gap cuts both ways. It limits clear upside from valuation alone but also reduces the margin for mispricing. The question for you is simple: if Hawkins is roughly in line with the DCF output today, what would need to change before the risk or reward looked very different?
Look into how the SWS DCF model arrives at its fair value.
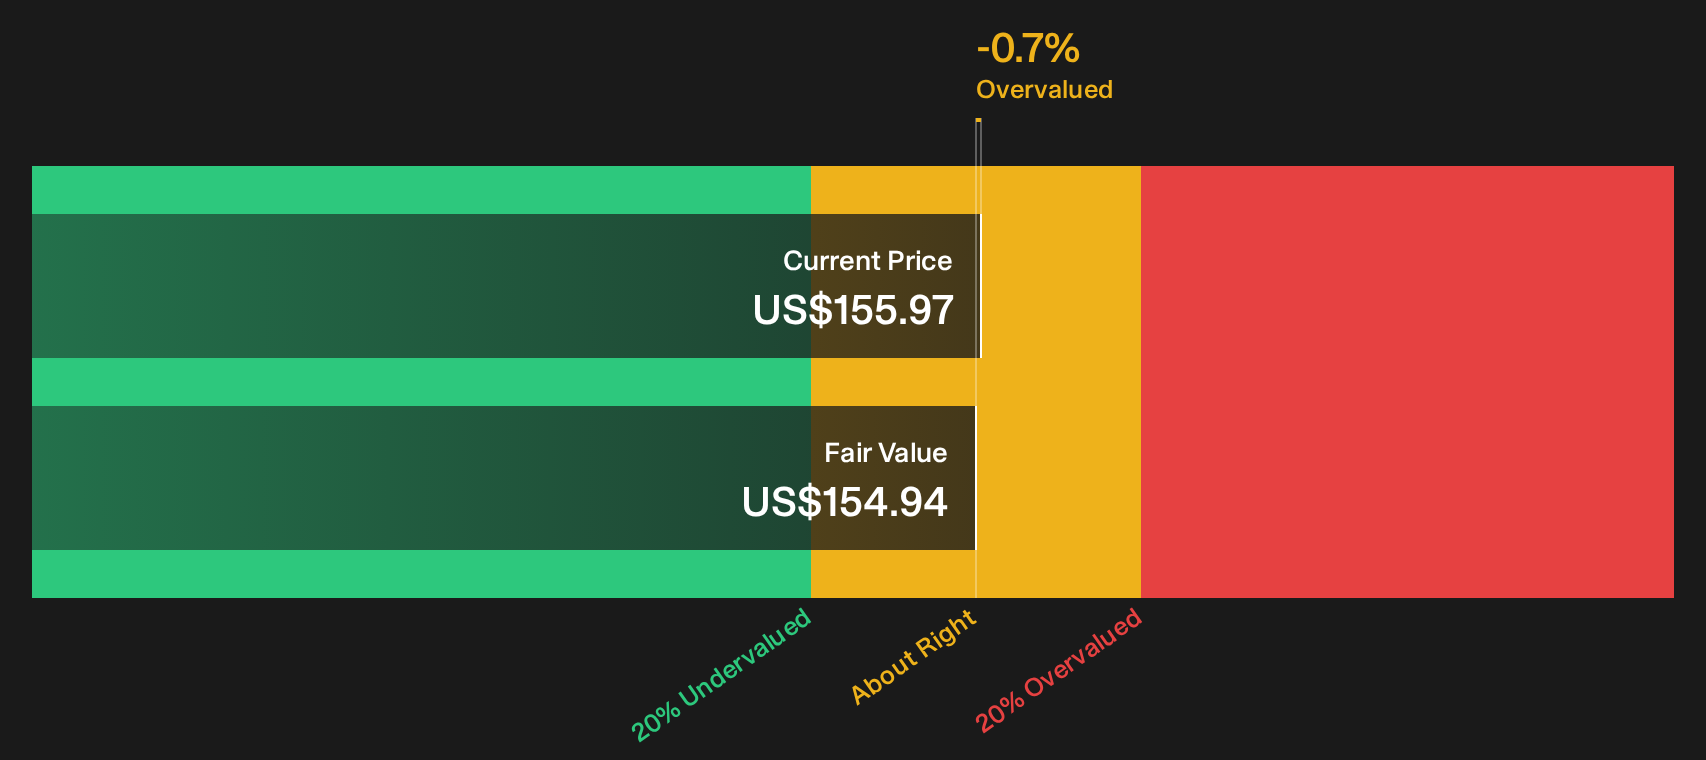
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Hawkins for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Hawkins now looks finely balanced on the numbers, so your next move depends on how you weigh the potential upsides against the valuation risk. If you want a quick way to see what investors are optimistic about, start with the 2 key rewards.
Looking for more Hawkins-sized opportunities?
If Hawkins has sharpened your focus on quality and price, do not stop here. Broaden your watchlist now so you are not late to the next idea.
- Spot potential value plays early by scanning a 35 high quality undervalued stocks that pairs solid fundamentals with prices that still look reasonable on key metrics.
- Strengthen your income stream by reviewing a 5 dividend fortresses that focuses on yield, consistency and balance sheet support behind those regular payouts.
- Reduce portfolio stress by filtering for a 31 resilient stocks with low risk scores that screens businesses on resilience, financial robustness and lower historical risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com