


EN
Missed Teck Resources' Rally? Here's What Buyers Needed
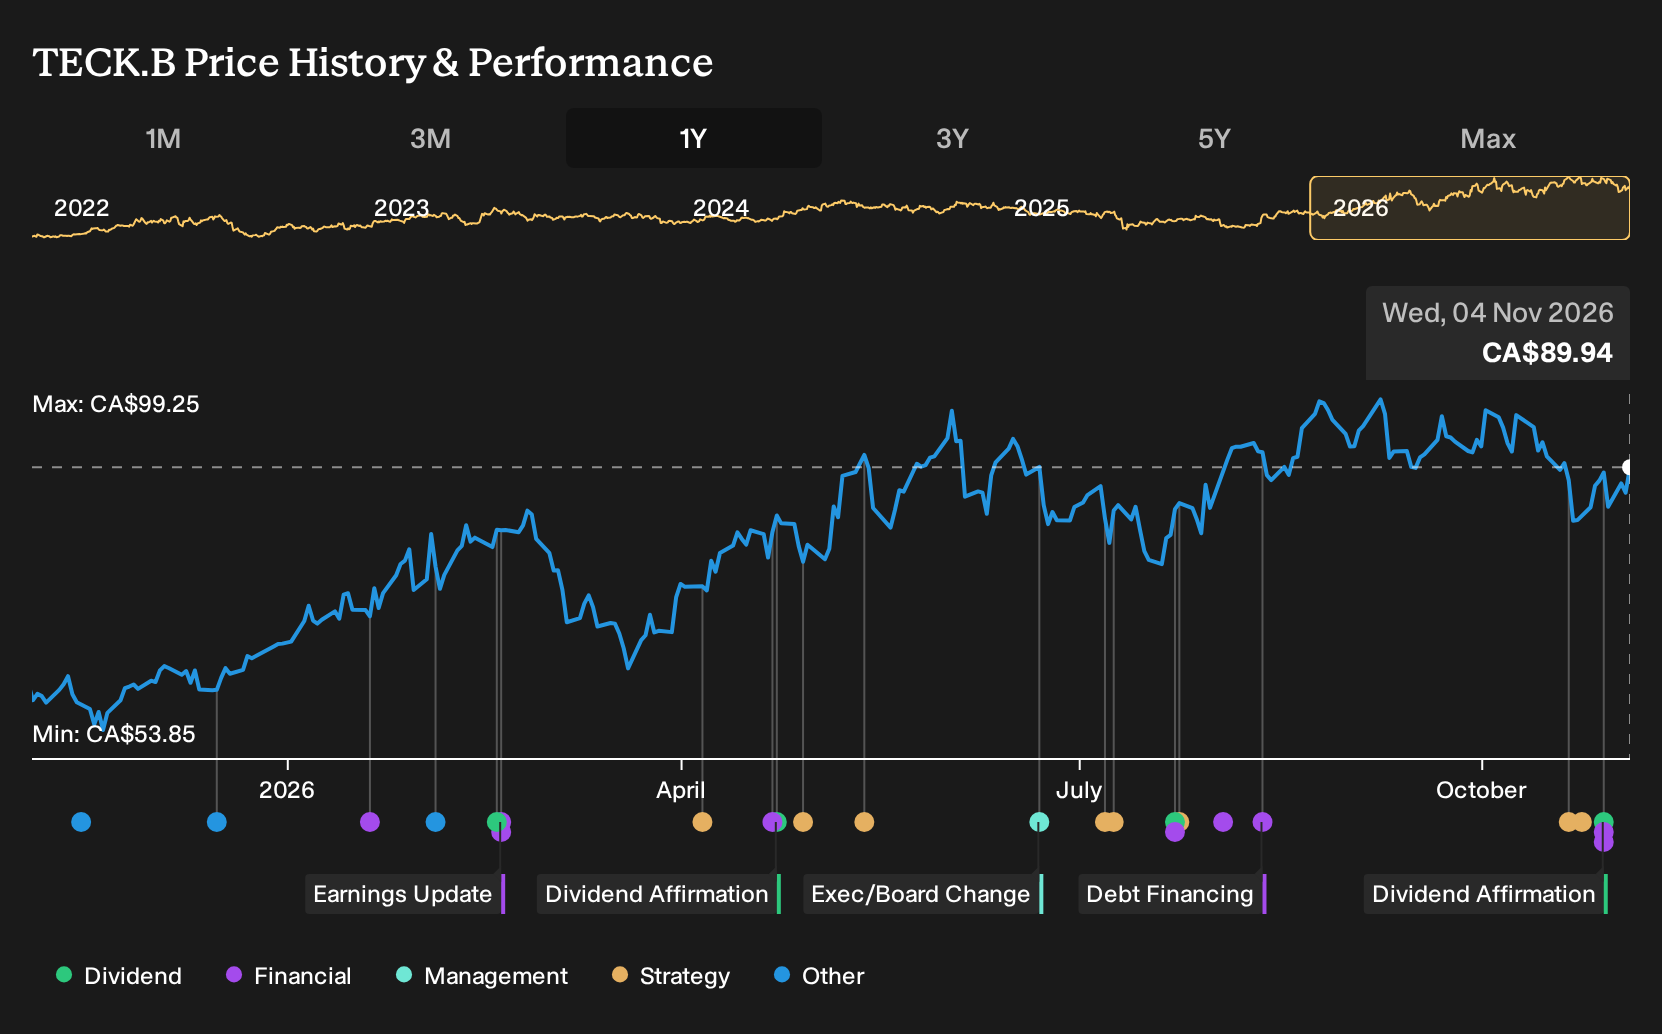
Teck Resources had plenty of headlines during the period, but one concrete shift was front and center by the end of it. Copper had become the core of the business, helped by record Q3 2026 results where profit and margins on copper production were on display. For Teck Resources shareholders, the return over the past year was 53.9%, including dividends. If you were deciding back in November 2025, what would have needed to look credible about that copper pivot and those project timelines to justify buying in before any of this arrived?
Teck Resources is not the only name tied to this theme. Zero in on 16 top copper producer stocks and compare how each one is priced.
The Two Copper Stories Investors Were Arguing About
The shares cost CA$57.94 at the start, and anyone looking at Teck Resources had to decide whether copper growth would justify paying that price.
The bullish story pointed to a Fair Value of CA$68.09, the price implied if copper expansion and policy support played out, built on an assumption that revenue could grow 8.9% a year and profit margins could climb from a loss to 16.3%.
The cautious view anchored on a Fair Value of CA$50, tied to concerns that Highland Valley delays and higher costs meant revenue might grow only 0.8% annually and margins might settle near 7.2%.
What The Results Changed For The Teck Resources Copper Debate
Record Q3 2026 numbers gave Teck Resources bulls fresh support. Revenue moved from C$3,385m in Q3 2025 to C$4,517m, while net income excluding extra items went from C$281m to C$1,592m. Net margin shifted from 8.3% to 35.2%. That profitability profile leaned toward the optimistic case, even though Highland Valley disruption reminded investors that execution risk on copper projects had not disappeared.
The takeaway is simple. When a copper pivot is the pitch, you test it against the mix of revenue and the direction of net margin in later reports, not just production headlines or project stories.
What Teck Resources' Rally Already Assumes
Teck Resources shares now trade at CA$89.94, after a 53.9% gain over the past year from CA$57.94. The selected Narrative’s Fair Value sits below that price, reflecting a view that copper benefits and byproduct support are already heavily reflected in the quote.
Rather than question the copper focus outright, this Narrative leans on the merger, capital intensity and mine mix to frame the risk. The key consideration for a buyer today is whether the copper-heavy portfolio can deliver stable volumes and margins through peak spending, which is concentrated on a few large assets.
"Key Takeaways: Bearish analysts expect Teck Resources to face sustained pressure on long term growth and profitability, as high capital spending on copper projects coincides with declining zinc output and higher unit costs at mature assets. The main factor that has to go right is that the copper-heavy portfolio, including QB, Highland Valley and the Anglo Teck merger, delivers stable volumes and attractive margins once the current peak investment phase passes."
One Narrative disagrees with today's price. → See where this Narrative says Teck Resources should trade
Find Your Own Contrarian Opportunity
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 40% below our estimate - uses an open to buy model and new distribution hub to react faster.
- Company 2 - 32% below our estimate - scales AVL production capacity and technician headcount so rising bookings convert into revenue.
- Company 3 - 47% below our estimate - shifts to higher grade ore feed and new underground zones to push volumes while lowering costs.
That is three of the list. See the full list of 5 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com