


EN
How Investors May Respond To AMETEK (AME) Raised 2026 Outlook
- AMETEK reported record third quarter 2026 results, with sales of US$2,220.31 million and GAAP diluted EPS of US$1.85, and raised full year 2026 guidance, including expected GAAP EPS of US$7.29 to US$7.33 and mid teens sales growth versus 2025.
- The business paired strong organic demand with contributions from acquisitions like Indicor Instrumentation, supported by record orders and backlog plus higher operating margins across key segments.
- The focus now turns to how AMETEK's raised 2026 earnings outlook may influence the investment narrative around its long term earnings power.
Scan how AMETEK’s raised 2026 outlook compares with peers by reviewing hand picked 53 AI infrastructure stocks that are also tied into semiconductor and data center spending trends.
What Is AMETEK's Investment Narrative?
To own AMETEK, you need to be comfortable with an execution story built on high value instrumentation, disciplined M&A and exposure to long cycle niches like aerospace, process industries and semiconductor infrastructure. The raised 2026 outlook, including GAAP EPS guidance of US$7.29 to US$7.33 and low 20% Q4 sales growth versus 2025, reinforces that current demand and pricing hold up well for now. In the short term, integration of Indicor, order conversion from the record backlog and keeping margins firm look like the real swing factors.
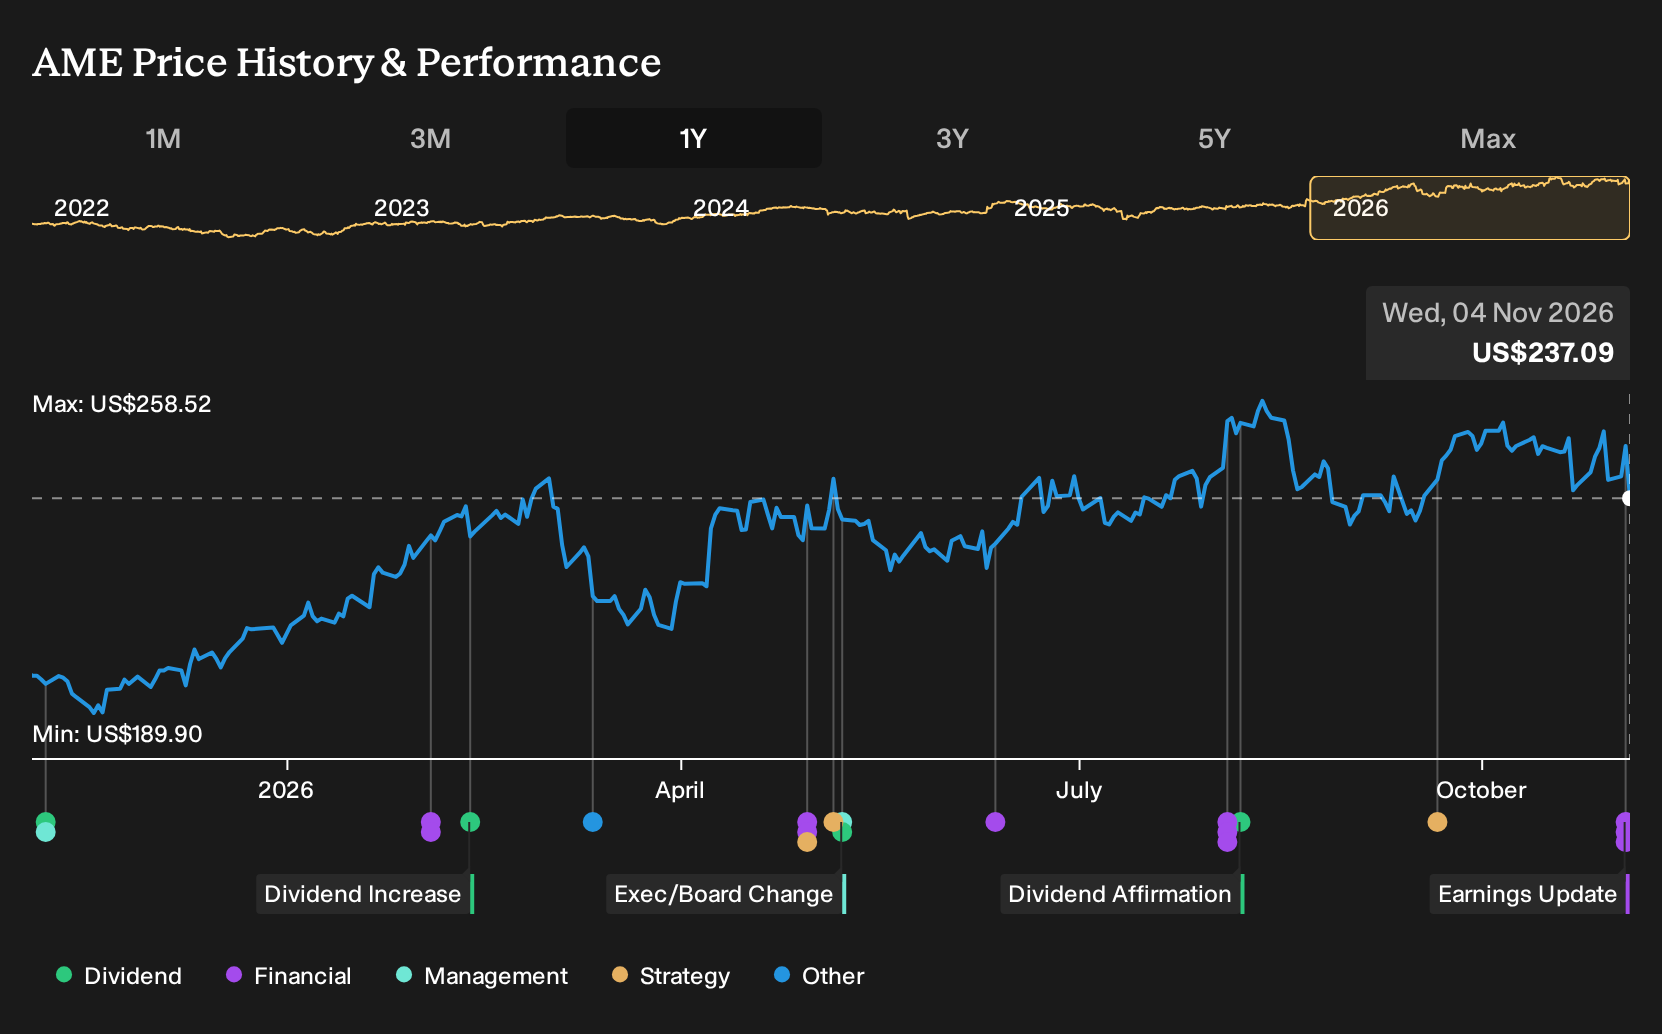
On the other side of the ledger, you are paying a premium multiple for AMETEK while accepting forecasts that are not explosive, with earnings expected to grow 10.2% per year and revenue 8.1% per year. Debt is meaningful, and funding is entirely from higher risk sources, so sustained cash generation matters if management stays “full speed ahead” on acquisitions. The recent pullback in the share price despite strong results shows how quickly sentiment can cool if investors start to question that balance.
Even so, there is one pressure point in the AMETEK story that rarely gets top billing until you look closely at ...
There's only one way to know the right time to buy, sell or hold AMETEK. Head to Simply Wall St's company report for the latest analysis of AMETEK's Fair Value.
Exploring Other Perspectives
Three fair value views from the Simply Wall St Community span roughly US$183 to about US$285 per share, so retail opinions on AMETEK sit on a wide spectrum. Those estimates were set before the record third quarter and raised 2026 guidance, so you are effectively weighing fresh guidance against older expectations. Use that gap as a prompt to explore several alternative viewpoints before deciding how AMETEK fits into your own thesis.
Explore 2 other AMETEK fair value estimates, including one that suggests as much as 23% downside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your AMETEK research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for AMETEK. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AMETEK's overall financial health at a glance.
Looking For More Investment Ideas Beyond AMETEK?
Once you have a view on AMETEK, it can help to put that thesis alongside a few contrasting opportunities. A focused stock list gives you a quick way to compare quality, balance sheet strength and income potential without getting lost in a huge universe of tickers.
- If you want businesses that combine robust finances with room to grow, start with this 19 high quality undiscovered gems and see which ones deserve a spot on your watchlist.
- For investors who care most about resilience in tougher markets, filter for companies with steadier profiles using a 31 resilient stocks with low risk scores that prioritises lower risk scores.
- Income focused readers can zero in on payout heavy opportunities by scanning a curated 5 dividend fortresses that meet a 5%+ yield hurdle while aiming for durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com