


EN
Earnings Beat Might Change The Case For UFP Technologies Stock (UFPT)
- UFP Technologies reported third quarter 2026 sales of US$172.43 million and net income of US$20.62 million, with both basic and diluted earnings per share from continuing operations above the prior year period.
- The nine month 2026 figures show US$500.6 million in sales and US$58.96 million in net income, indicating that the medical focused manufacturer is scaling its operations while maintaining profitability.
- We will now examine how UFP Technologies' stronger third quarter earnings and higher earnings per share could reshape its investment narrative.
Scan how UFP Technologies’ latest earnings stack up against peers by reviewing the hand picked 19 high quality undiscovered gems that share strong fundamentals and are still flying under most investors' radar.
UFP Technologies Investment Narrative Recap
To own UFP Technologies, you need to believe the medical focused manufacturer can keep turning its niche in advanced components and packaging into steady earnings, while managing concentrated exposure to customers like Intuitive Surgical and Stryker. The latest quarter, with higher sales, net income and EPS versus last year, supports that operating thesis rather than changing it.
The near term swing factor is execution at facilities such as AJR and the ramp of lower cost sites in the Dominican Republic. Recent results suggest margin pressure from earlier labor inefficiencies is not worsening, but integration, workforce stability and cost inflation remain the biggest operational risks to watch.
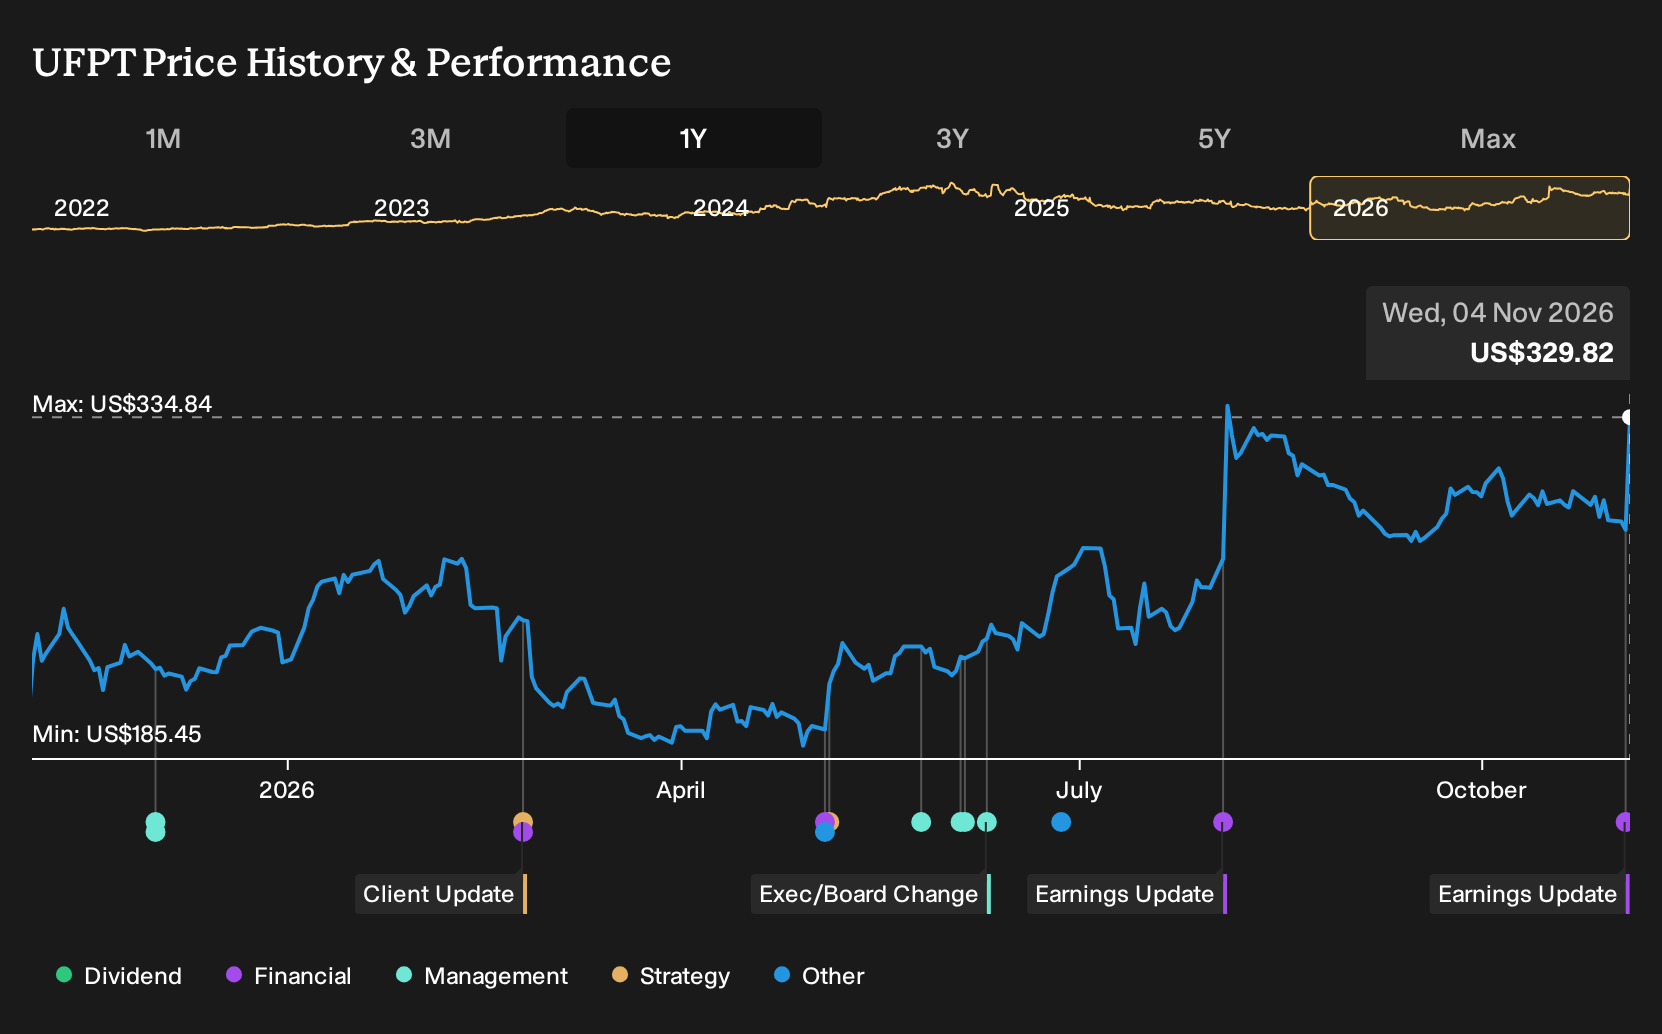
The key announcement in focus is the Q3 and nine month 2026 earnings release on November 3, 2026. Management reported quarterly sales of US$172.43 million and net income of US$20.62 million, with both basic and diluted EPS from continuing operations above the prior year period, pointing to solid operating leverage.
Over the first nine months of 2026, UFP Technologies recorded US$500.6 million in revenue and US$58.96 million in net income. For you as a shareholder, that report ties directly into the main catalysts, such as new medical programs and acquisition integration, while also highlighting the ongoing risks from customer concentration, labor issues and cost pass through.
UFP Technologies' current analyst narrative points to US$741.6 million in revenue and US$102.0 million in earnings by 2029, based on forecasts that assume 5.5% annual revenue growth and an increase in earnings of about US$29.7 million from US$72.3 million today.
Uncover how UFP Technologies' fair value indicates an 8% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
One alternate view on UFP Technologies places significant emphasis on customer concentration risk. The most cautious analysts have focused on the fact that the top 5 customers represented 61% of year-to-date revenue and, before this Q3 release, were only penciling in about US$784.8 million of 2029 revenue and US$111.1 million of earnings. That is a much more conservative story than the consensus, and this fresh earnings beat could eventually push those expectations higher or reinforce the caution, depending on how you read the new numbers. Exploring both angles can help you decide which version of the future feels more realistic.
Explore another UFP Technologies fair value estimate, including one that suggests as much as 32% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis and judgment.
- A great starting point for your UFP Technologies research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for UFP Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to review UFP Technologies' overall financial position at a glance.
Looking For More UFP Technologies Investment Ideas?
If UFP Technologies has sharpened your appetite for quality businesses, it can be useful to line it up against other candidates with different strengths. The Simply Wall St screener lets you filter for the traits you care about, then compare fundamentals side by side so your watchlist reflects your own playbook rather than someone else’s.
- For investors hunting for resilient businesses with strong finances, review the list of solid balance sheet and fundamentals (24 results) which can help anchor a more defensive portfolio mix.
- If value is the priority, scan the 35 high quality undervalued stocks which match solid fundamentals with prices that look compressed on key metrics.
- Income focused investors can concentrate on the 5 dividend fortresses which pair higher yields with an emphasis on durability of payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com