


EN
Napco Security Technologies (NSSC) Earnings And Dividend Put Fair Value Back In Focus
Napco Security Technologies (NSSC) put fresh numbers and cash returns on the table on 2 November, pairing its first quarter fiscal 2027 earnings release with a declared quarterly dividend of $0.17 per share.
Despite the fresh Q1 2027 figures and the new dividend, Napco Security Technologies shares have been under pressure, with the 7-day share price return down 19.94% and the year-to-date share price return down 23.27%, while the 1-year total shareholder return has declined 27.35%. However, the stock remains ahead over three and five years, with total shareholder returns of 29.92% and 45.88% respectively, pointing to fading short-term momentum against a still positive longer-term record.
Scan beyond Napco Security Technologies and compare this earnings plus dividend setup with a curated list of list of solid balance sheet and fundamentals (24 results).
After a sharp pullback, but with a price that still sits below both analyst targets and one intrinsic value estimate, the real tension is simple: Does Napco Security Technologies now trade below fair value or still above it?
Most Popular Narrative: 28% Undervalued
Napco Security Technologies last closed at $31.75, compared with a widely followed fair value estimate of about $44.33 that uses an 8.8% discount rate. That gap rests heavily on how recurring service revenue and new platforms shape the earnings profile over the next few years.
The main factor that has to go right is that recurring service revenue and StarLink activations continue to convert at high margins, while new platforms like MVP and connected locking products begin to add meaningful recurring revenue without being disrupted by component cost and supply pressures.
See why 26 investors see Napco Security Technologies as 28% undervalued.
Result: Fair Value of $44.33 (UNDERVALUED)
Still, if component costs stay elevated or StarLink conversions slow, the recurring service engine that underpins Napco Security Technologies' valuation story could stall.
Find out about the key risks to this Napco Security Technologies narrative.
Another View: What The P/E Ratio Says About Napco Security Technologies
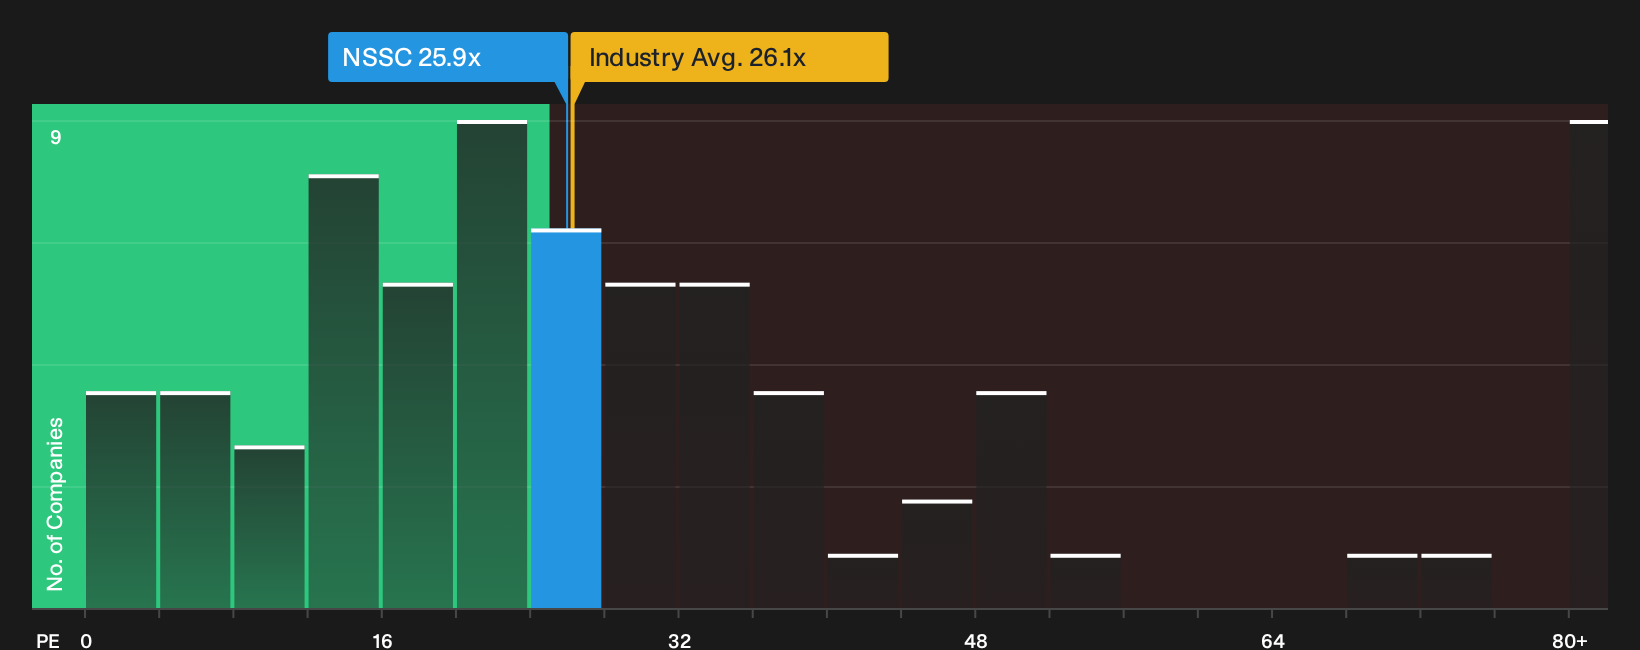
The first fair value story leans on earnings forecasts and discount rates. A quick reality check comes from the current P/E of 25.9x. That level is above the fair ratio of 23.9x and well above a peer average that screens as deeply loss making, yet it still sits below the wider US Electronic industry on 28.5x. In practice, that mix suggests some valuation risk if sentiment cools, but also hints at relative support compared with the broader sector. Which side of that trade off are you more comfortable owning?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the valuation story for Napco Security Technologies. If that balance of risk and reward feels uncomfortable, move fast and interrogate the data yourself, starting with the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Napco Security Technologies?
If the story around Napco Security Technologies leaves you wanting a wider watchlist, use the data tools at your disposal and build a stronger set of contenders.
- Target potential mispricing by scanning a focused group of quality candidates through the 34 high quality undervalued stocks.
- Build a steadier portfolio core by reviewing the 31 resilient stocks with low risk scores that combine resilience with measured risk profiles.
- Get ahead of the crowd by hunting through the 19 high quality undiscovered gems that pair solid fundamentals with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com