


EN
How Investors May Respond To Gjensidige Forsikring Stock (OB:GJF) Strong Earnings Report
- Gjensidige Forsikring reported third quarter 2026 net income of NOK 2,076.7 million and basic earnings per share of NOK 4.08, with nine month net income of NOK 5,924.9 million.
- The gap between basic earnings per share from continuing operations and total EPS for the nine month period suggests incremental contributions outside the core ongoing activities that investors may want to distinguish from underlying performance.
- We will now consider how Gjensidige Forsikring's investment narrative aligns with this third quarter earnings profile.
Scan beyond Gjensidige Forsikring and compare this earnings story with a curated 194 high quality undervalued stocks that may also be pricing in strong profitability and resilient balance sheets.
Gjensidige Forsikring Investment Narrative Recap
Owning Gjensidige Forsikring means believing that disciplined pricing, tight cost control and a broad Nordic footprint can keep underwriting solid while the pension arm gradually earns its place. The latest quarter delivered NOK 2,076.7 million in profit and NOK 4.08 in EPS from continuing operations. This supports that operational story rather than reshaping it.
The key near term swing factor still sits in claims costs and how well premiums keep pace with inflation and the Danish workers compensation exposure. The biggest risk remains that unforeseen claim developments or persistent pension losses chip away at margins. This earnings release does not materially change that risk balance.
The most relevant recent disclosure for this context is the Q3 and nine month 2026 earnings update itself, because it links directly to those underwriting and pension themes. Nine month net income of NOK 5,924.9 million, with EPS from continuing operations of NOK 11.27, shows how the core book and non core items each contribute to overall profitability.
For catalysts, these figures provide a current indication of whether pricing actions, portfolio trimming and digital efficiency are feeding through to the bottom line quickly enough to offset areas under pressure such as pensions or Danish workers compensation. They also indicate how comfortably Gjensidige Forsikring can support its dividend policy given earlier questions around free cash flow coverage.
Gjensidige Forsikring's current analyst storyline points to revenues of NOK 51.3 billion and earnings of NOK 10.3 billion by 2029, based on an assumed 2.6% yearly increase in revenue and an earnings uplift of NOK 3.9 billion from NOK 6.4 billion today.
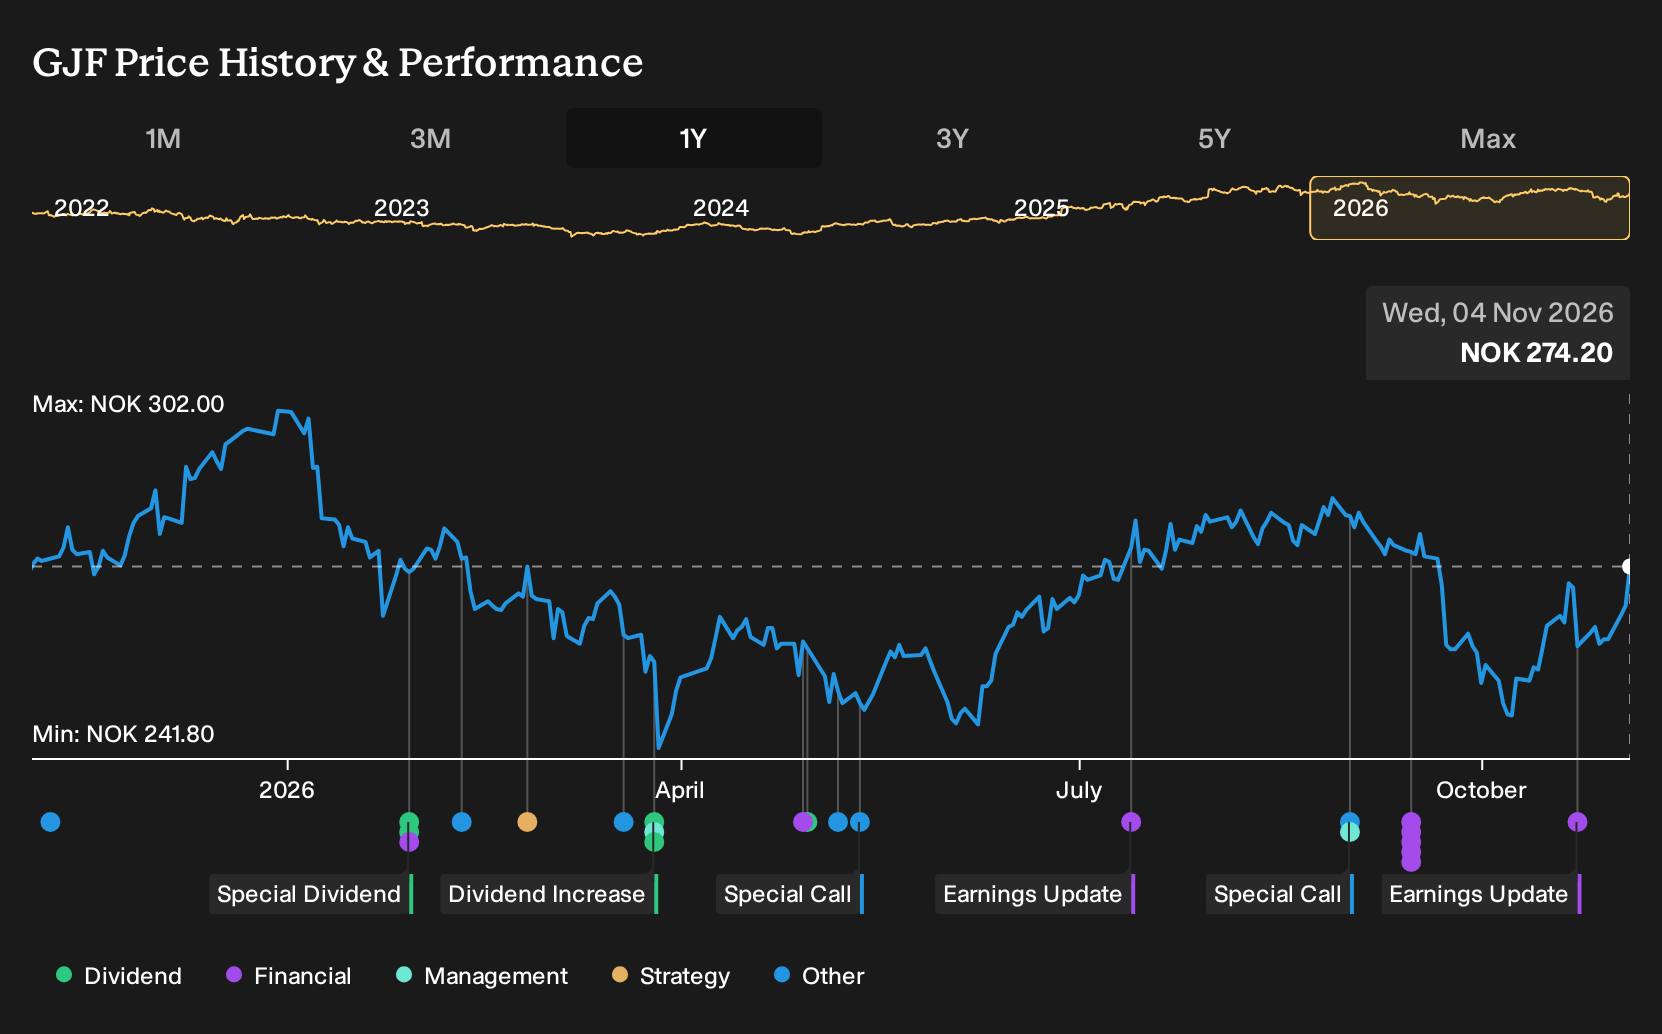
Uncover how Gjensidige Forsikring's fair value indicates a 4% potential upside to its current price, before enthusiasm for Gjensidige Forsikring closes that discount.
Exploring Other Perspectives
One alternate take focuses on the Danish workers compensation exposure as a drag on Gjensidige Forsikring. The most cautious analysts were modelling slower revenue progress of about NOK 50.9 billion and earnings of roughly NOK 9.5 billion by 2029. That is a more muted story than consensus, and this latest earnings release may push those views to evolve.
Explore 3 other Gjensidige Forsikring fair value estimates, including one that indicates as much as 9% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Gjensidige Forsikring research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Gjensidige Forsikring. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Gjensidige Forsikring's overall financial health at a glance.
Looking for more investment ideas beyond Gjensidige Forsikring?
If this Gjensidige Forsikring earnings story has sharpened your process, widen the lens and test your thesis across other companies using the Simply Wall St Screener, so you can compare quality, valuation and risk on the same footing.
- For investors who want to focus on resilient businesses first and potential upside second, start with a 224 resilient stocks with low risk scores that have historically scored well on stability and downside protection.
- If consistent balance sheets and solid fundamentals matter most to you, filter the market through a list of solid balance sheet and fundamentals (197 results) and see which companies clear your quality bar.
- When income is the priority, narrow the field to a 216 dividend fortresses that can help you compare yield, payout ratios and dividend history side by side.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com