


EN
Phillips Edison (PECO) Could Be 5% Below Fair Value Following Raised Guidance
Why Phillips Edison’s latest quarter is in focus
Phillips Edison (PECO) has grabbed investor attention after third quarter earnings showed higher sales, a sharp jump in net income, and a lift to full year profit guidance, all backed by fresh term loan financing.
The recent results and guidance shift appear to be feeding into the price action, with Phillips Edison’s 1-day share price return of 3.94% and 7-day share price return of 9.07% adding to a 16.64% year-to-date share price gain and a 24.80% total shareholder return over the past year. This hints that investors are recalibrating both growth prospects and risk around the stock.
Scan other real estate operators showing similar earnings momentum by checking our curated list of list of solid balance sheet and fundamentals (25 results) along with Phillips Edison’s latest move.
Phillips Edison now looks like a robust grocery anchored landlord with rising guidance and fresh financing behind it. After this latest run in the share price, is that strength already fully reflected in today’s valuation?
Most Popular Narrative: 5% Undervalued
Against a fair value estimate of $43.31 and a last close of $41.14, the most followed Phillips Edison narrative points to a modest valuation gap that investors are watching closely as new acquisitions and capital recycling play through the model.
Capital recycling where assets sold around a 5.9% initial yield are redeployed into properties bought around a 6.6% to 6.7% yield and underwritten at roughly 9% unlevered IRRs creates a positive spread that can lift net margins and FFO per share over time.
See why 5 investors see Phillips Edison as 5% undervalued.
Result: Fair Value of $43.31 (UNDERVALUED)
Still, if e commerce adoption accelerates or higher interest costs stick around, the Phillips Edison thesis could be tested as acquisition spreads and occupancy come under pressure.
Find out about the key risks to this Phillips Edison narrative.
Another View: What Phillips Edison’s P/E Is Signalling
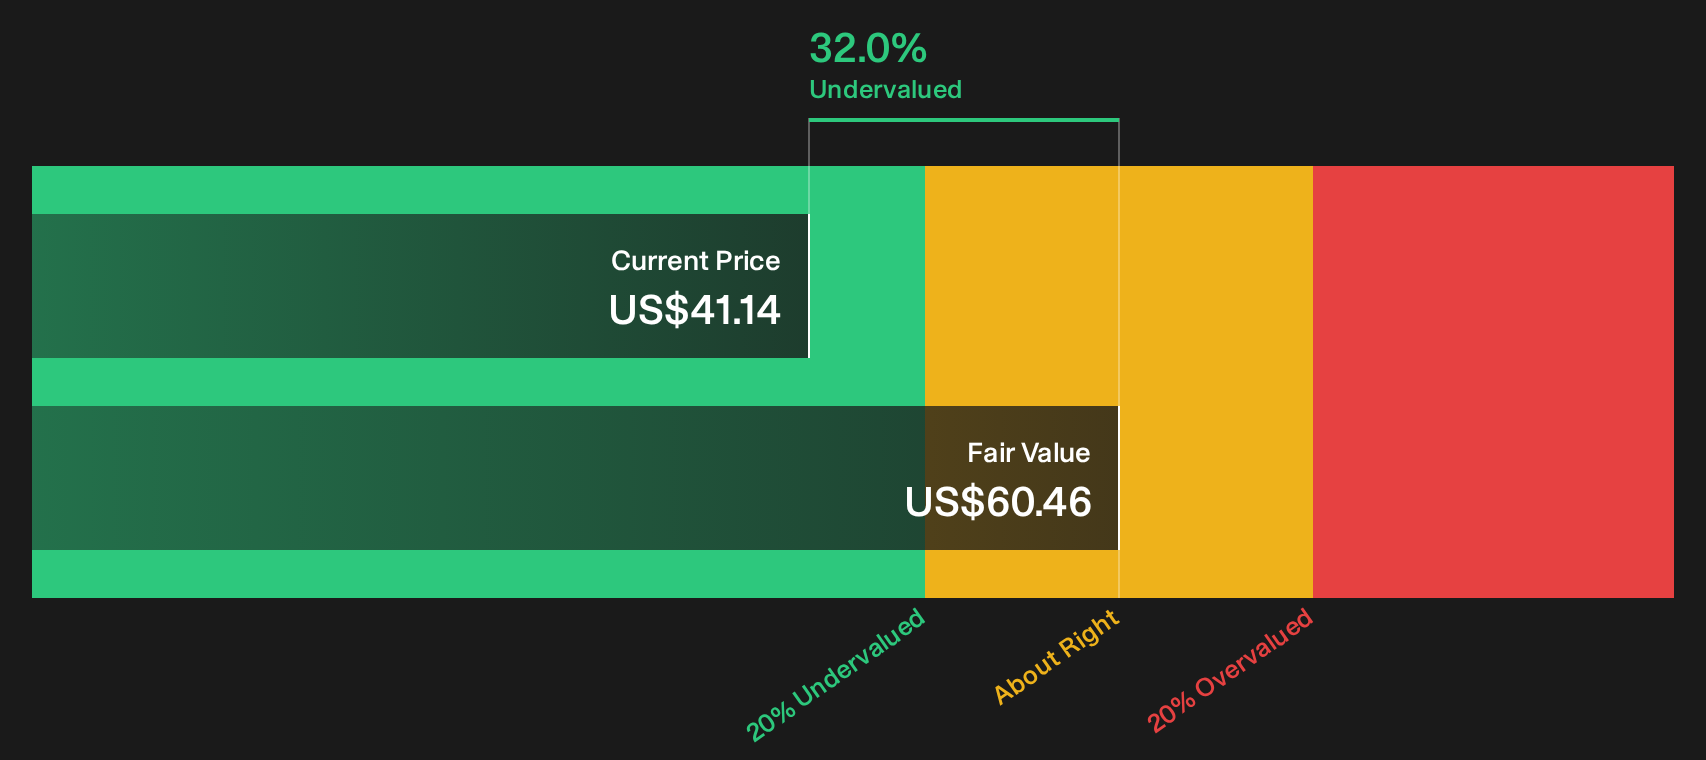
The DCF work paints Phillips Edison as undervalued, with the current $41.14 price sitting about 32% below an internal fair value estimate of $60.46 based on future cash flows. That assumes the cash generation path is reliable enough to outweigh near term earnings pressure.
Yet the market is also assigning a P/E of 29.2x, which is richer than both the US Retail REITs industry at 25x and a fair ratio of 25.4x that the market could move towards over time. That premium suggests investors already pay up for Phillips Edison’s profile. The question is whether the DCF upside or the earnings multiple risk ends up steering the next big move.
For a closer look at how this cash flow based result is built, and how sensitive it is to small shifts in growth or discount rates, Look into how the SWS DCF model arrives at its fair value.
Next Steps
The story for Phillips Edison presents mixed messages so far. Prices, guidance, and valuations are all moving in different directions, so consider acting promptly and stress test the case against our breakdown of 2 key rewards and 3 important warning signs
Looking for more Phillips Edison style investment ideas?
If you like how Phillips Edison stacks up but do not want to stop at a single opportunity, broaden your watchlist with a few targeted screens that surface fresh ideas efficiently.
- Target resilient compounding potential by focusing on strong fundamentals and valuation support through a curated set of 34 high quality undervalued stocks that may suit a disciplined approach.
- Prioritise sleep at night stability by scanning a focused 31 resilient stocks with low risk scores that filters for businesses with more resilient overall risk profiles.
- Hunt for tomorrow's quiet overachievers by working through a hand picked pool of 19 high quality undiscovered gems before the crowd pays closer attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com