


EN
Urban Outfitters Stock After Earnings Beat And Nuuly Expansion
- Urban Outfitters reported a 10.4% year over year rise in revenue and a 75.9% jump in earnings per share in the most recent quarter, supported by growth across its multi brand retail portfolio.
- The expansion of Urban Outfitters' Nuuly subscription and continued investment in logistics and new stores highlight a push toward recurring revenue and operational scale, even as higher marketing and freight costs pressure margins.
- We will now look at how Urban Outfitters' investment narrative is affected by its strong earnings report and Nuuly expansion.
Urban Outfitters Investment Narrative Recap
To be a shareholder in Urban Outfitters, you need to buy into a simple idea. The group aims to use its multi brand portfolio and Nuuly subscription to turn solid recent execution into more consistent cash generation, helped by a relatively clean balance sheet with net debt at 0.7 times EBITDA. The latest quarter, with 10.4% revenue growth and a 75.9% EPS jump, supports that operating story.
The key short term swing factor is still whether Nuuly and FP Group can scale without letting marketing, freight and store expansion costs erode profitability. Higher fuel related surcharges and the merchandising pressure at Anthropologie remain the biggest near term risks, because they can offset efficiency gains elsewhere and limit any earnings benefit from Nuuly growth.
The most relevant development here is the expansion of Urban Outfitters' Nuuly subscription platform, supported by the Kansas City facility and a new East Coast fulfillment center. This matters because a larger, recurring subscription base can spread logistics and technology costs across more orders and potentially support group operating income if execution stays tight.
Nuuly's growth sits alongside continued investment in logistics and new stores, with around US$475 million of planned capital expenditure in FY27. For you as an investor, the operational question is whether these projects and AI driven merchandising tools can lift full price sell through and limit markdowns faster than higher freight, fuel surcharges and Anthropologie margin pressure weigh on the group.
Urban Outfitters' current earnings of $569.1 million sit against analyst forecasts of $587.0 million by 2029, implying an earnings increase of about $17.9 million by that year. That projection is paired with an expected 7.1% yearly rise in revenue and a revenue target of $7.9 billion in 2029.
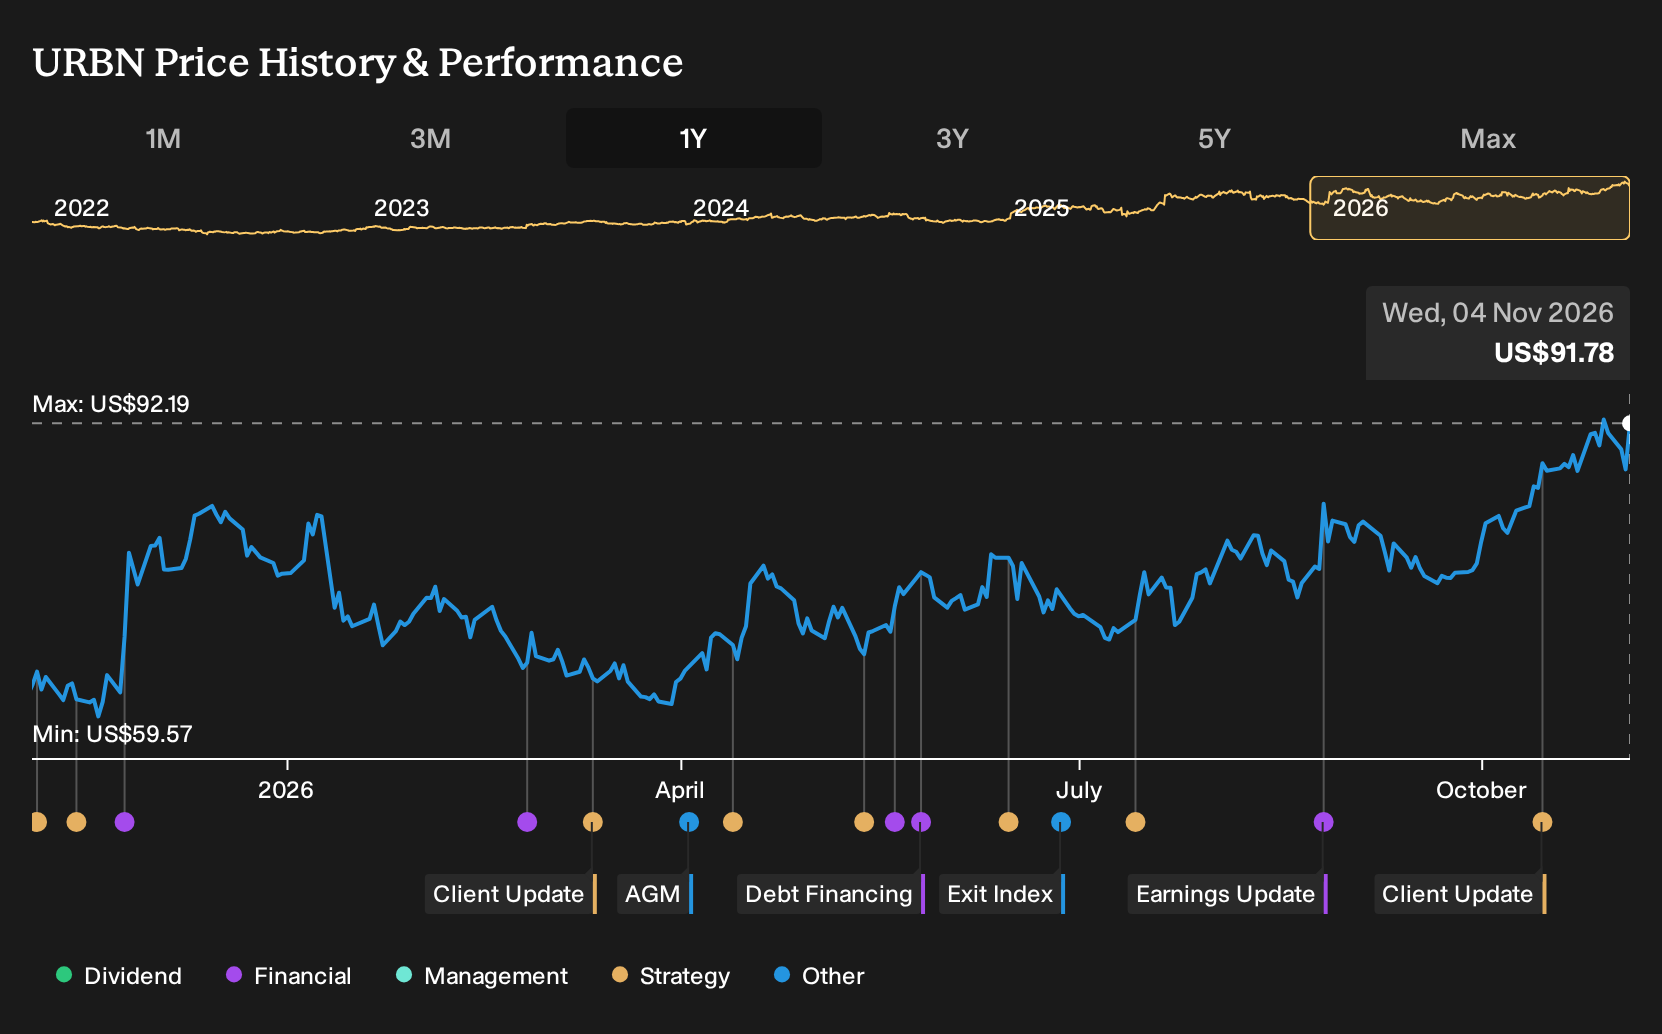
Uncover why Urban Outfitters' fair value indicates a 3% potential downside to its current price, leaving little room for error.
Exploring Other Perspectives
Some analysts placed more weight on the risk that Nuuly and FP Group might not offset cost pressure, which is why their 2029 earnings view sat closer to $564.2 million on about $7.6b of revenue. That is more cautious than the consensus $587.0 million outlook. Those estimates all came before this Urban Outfitters earnings surprise, so you may see narratives shift.
Explore 2 other Urban Outfitters fair value estimates, including one that suggests as much as 39% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Urban Outfitters research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Urban Outfitters. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Urban Outfitters' overall financial health at a glance.
Looking For More Investment Ideas Beyond Urban Outfitters?
Once you have a view on Urban Outfitters, it can help to cross check that thesis against other businesses with different balance sheet profiles and income drivers. The Simply Wall St Screener lets you scan the market through a few focused lenses so you can see where risk, quality and income potential line up with your own preferences.
- If capital preservation is your priority, start with companies that aim for steadier returns and use the 31 resilient stocks with low risk scores.
- For investors who want quality at a measured valuation, compare Urban Outfitters with a 34 high quality undervalued stocks to see which businesses pair stronger fundamentals with pricing that may look more reasonable.
- If you care most about robust finances and cleaner balance sheets, narrow your watchlist using a list of solid balance sheet and fundamentals (25 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com