


EN
Dell Stock Gets A Security Push From New AI Protection Tools
- CrowdStrike recently announced an integrated Falcon security offering for the Dell AI Factory with NVIDIA, while Dell expanded its cybersecurity and resilience portfolio across AI environments, identity systems and storage with new services, PowerProtect features and quantum safe encryption.
- By tying AI focused security, identity recovery and managed detection directly into its AI infrastructure and large AI server backlog, Dell Technologies is sharpening its pitch to enterprises that want a single vendor for both AI compute and protection of mission critical workloads.
- We will examine how Dell Technologies' investment narrative is affected by bundling CrowdStrike secured AI infrastructure into its AI Factory offering.
Scan how Dell Technologies’ AI security push compares with other potential breakout infrastructure plays by reviewing the curated 53 AI infrastructure stocks list aligned with this same theme.
Dell Technologies Investment Narrative Recap
To own Dell Technologies, you need to believe the large AI server backlog and pipeline eventually turn into shipped systems and cash, while higher margin storage and services keep gaining weight in the mix. The recent CrowdStrike and AI Factory security moves support that belief on the demand side, but they do not change the near term reality that component supply and conversion of that US$95b AI backlog remain the key swing factors.
The biggest risk still sits in tight supply and hardware commoditization, which can compress margins if input costs keep rising faster than selling prices, especially with AI GPU systems running at mid single digit operating margins. That is where the new AI focused security offerings matter operationally by giving Dell Technologies more reasons to attach services, storage and managed detection to each AI rack. This helps address margin dilution risk but does not remove it.
The CrowdStrike Falcon integration into the Dell AI Factory with NVIDIA looks most relevant here because it explicitly ties three security layers (agent protection, infrastructure defense, and unified security operations) into the same reference architecture as Dell’s AI servers. That gives enterprises a pre packaged way to buy GPUs, storage, networking, and protection as one bundle, with Dell Managed Detection and Response acting as the security operations overlay.
For catalysts, this alignment matters because it lets Dell Technologies pitch a larger contract per AI deployment and gives the firm more chances to attach services where margins are typically richer than bare hardware. It also introduces new execution questions. Dell needs to prove it can staff and run these expanded managed services at scale while component constraints, elevated inventory, and intense competition in both AI servers and storage still hang over the story.
What The Current Forecast Implies For Dell Technologies
Dell Technologies' current analyst narrative points to revenues of US$266.7b and earnings of US$20.8b by 2029, anchored on an assumed 20.8% yearly revenue growth rate and an earnings increase of about US$9.4b from US$11.4b today.
Discover how Dell Technologies' fair value indicates a 60% potential upside to its current price that may not last much longer.
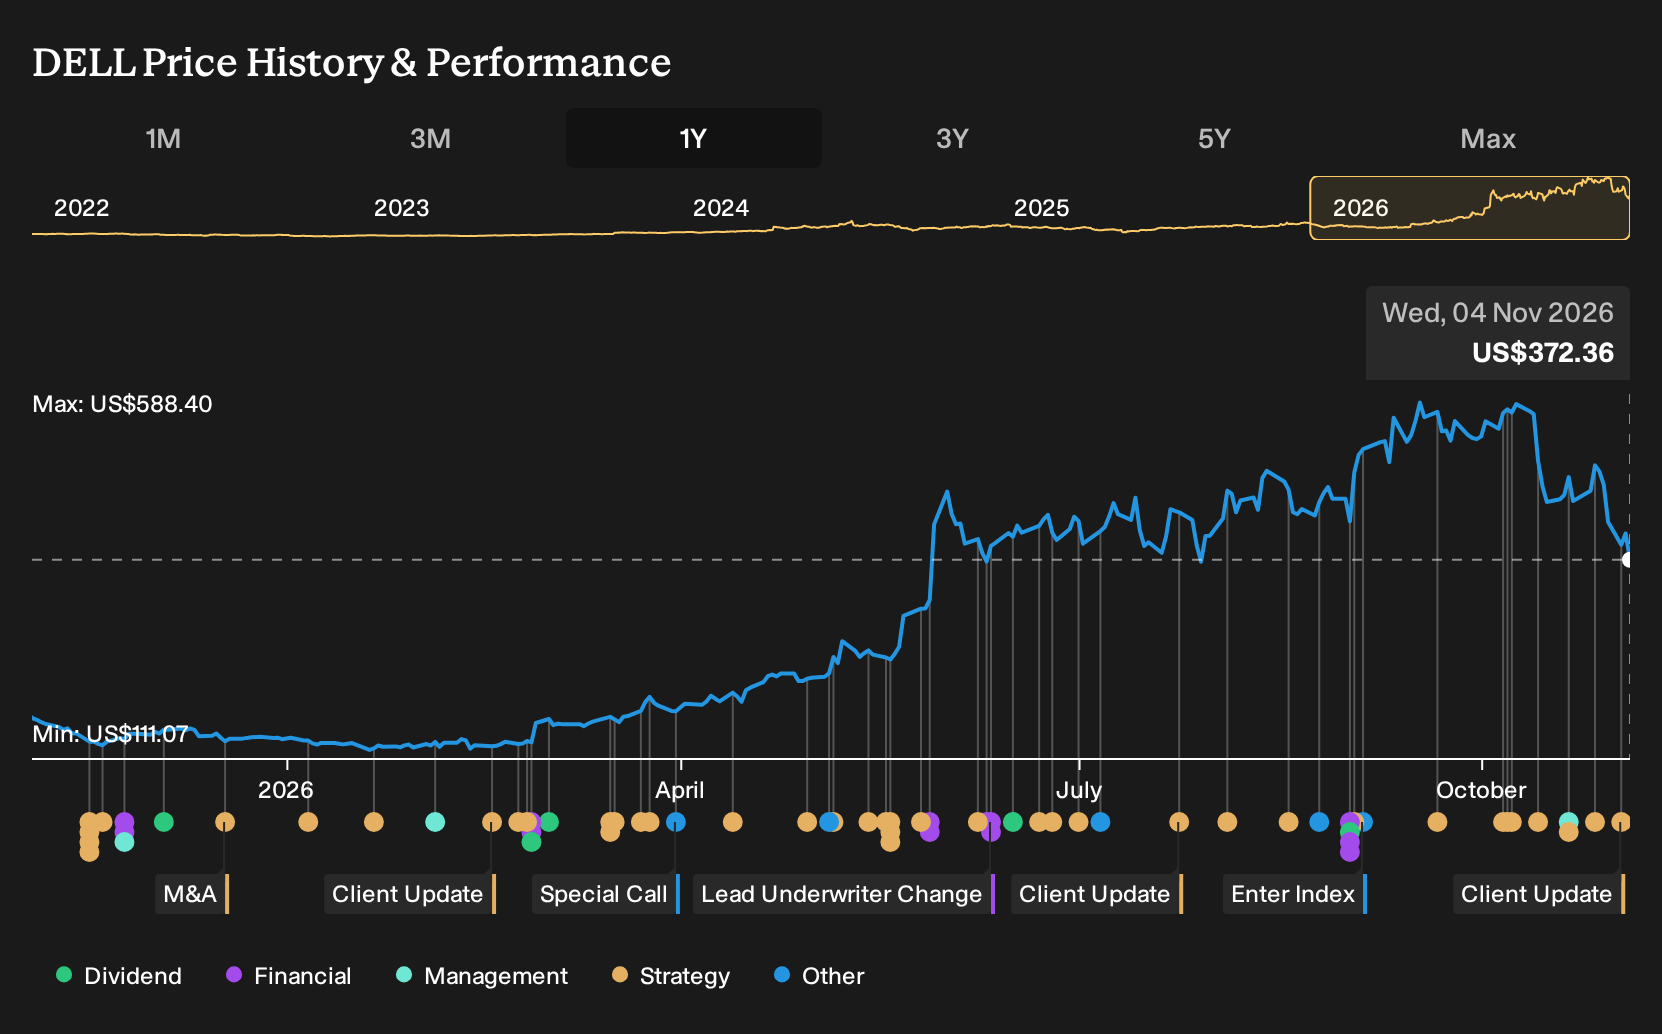
Exploring Other Perspectives
One alternate view zooms in on project timing risk rather than Dell Technologies’ security bundling upside. The most cautious analysts work off about US$238.3b of 2029 revenue and US$19.0b of earnings, well below consensus. That more muted setup did not factor in the CrowdStrike AI Factory news, so these opinions could shift.
Explore 4 other Dell Technologies fair value estimates, including one that suggests it could be worth just $490.00!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Dell Technologies research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Dell Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Dell Technologies' overall financial health at a glance.
Looking For More Investment Ideas Beyond Dell Technologies?
If the Dell Technologies story has you thinking about where else AI, cash generation, and balance sheet strength intersect, it can help to scan a broader field of candidates that share similar financial traits.
- If you value steadier profiles with strong finances, take a look at our 31 resilient stocks with low risk scores that may better match your comfort with volatility.
- For those who care most about financial resilience and clean books, start with a list of solid balance sheet and fundamentals (25 results) that can handle tougher conditions.
- When you want something less picked over, focus on companies that the market may not yet fully appreciate through a 19 high quality undiscovered gems that still show solid fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com