


EN
George Weston (TSX:WN) Could Be 2% Undervalued After Confidence Builds In Its Core Businesses
Fresh reporting on George Weston (TSX:WN) highlights rising investor confidence, as its mix of food retail, pharmacy services, and commercial real estate draws attention despite ongoing pressure on consumers and intense grocery competition.
Recent trading has reflected that improving mood. The company has a 1-month share price return of 11.10% at a latest share price of CA$111.5, while the 1-year total shareholder return of 28.32% and 5-year total shareholder return of 158.54% suggest George Weston has built momentum over both shorter and longer holding periods.
Scan other consumer-focused stocks that show similar momentum and diversified earnings profiles using our curated 8 high quality undiscovered gems. These, like George Weston, pair established brands with underappreciated upside drivers.
George Weston’s quick rerating over the past month raises a sharper question: Has the run largely priced in the story already, or do the current numbers still leave meaningful upside on the table?
Most Popular Narrative: 1.6% Undervalued
On the latest narrative, George Weston screens as modestly undervalued, with a fair value of CA$113.29 against a last close of CA$111.50. This keeps attention firmly on how dependable its earnings and cash returns really are.
The main factor is that Loblaw and Choice Properties continue to support cash flow that funds dividends, regular share repurchases and the planned equity commitment to the First Capital transaction without stretching the balance sheet.
The approximately $5 billion acquisition of high quality urban necessity anchored assets by Choice Properties, supported by George Weston’s $600 million equity commitment, is expected to be cash flow positive to Weston because incremental distributions are projected to exceed funding costs, which could influence future consolidated cash flow and earnings.
See why 1 investors see George Weston as 2% undervalued.
Result: Fair Value of CA$113.29 (UNDERVALUED)
Still, the George Weston story can shift quickly if tighter rules on Loblaw property controls affect pricing, or if valuation changes at Choice Properties keep earnings volatile.
Find out about the key risks to this George Weston narrative.
Another View: Multiples Paint A Tougher Picture For George Weston
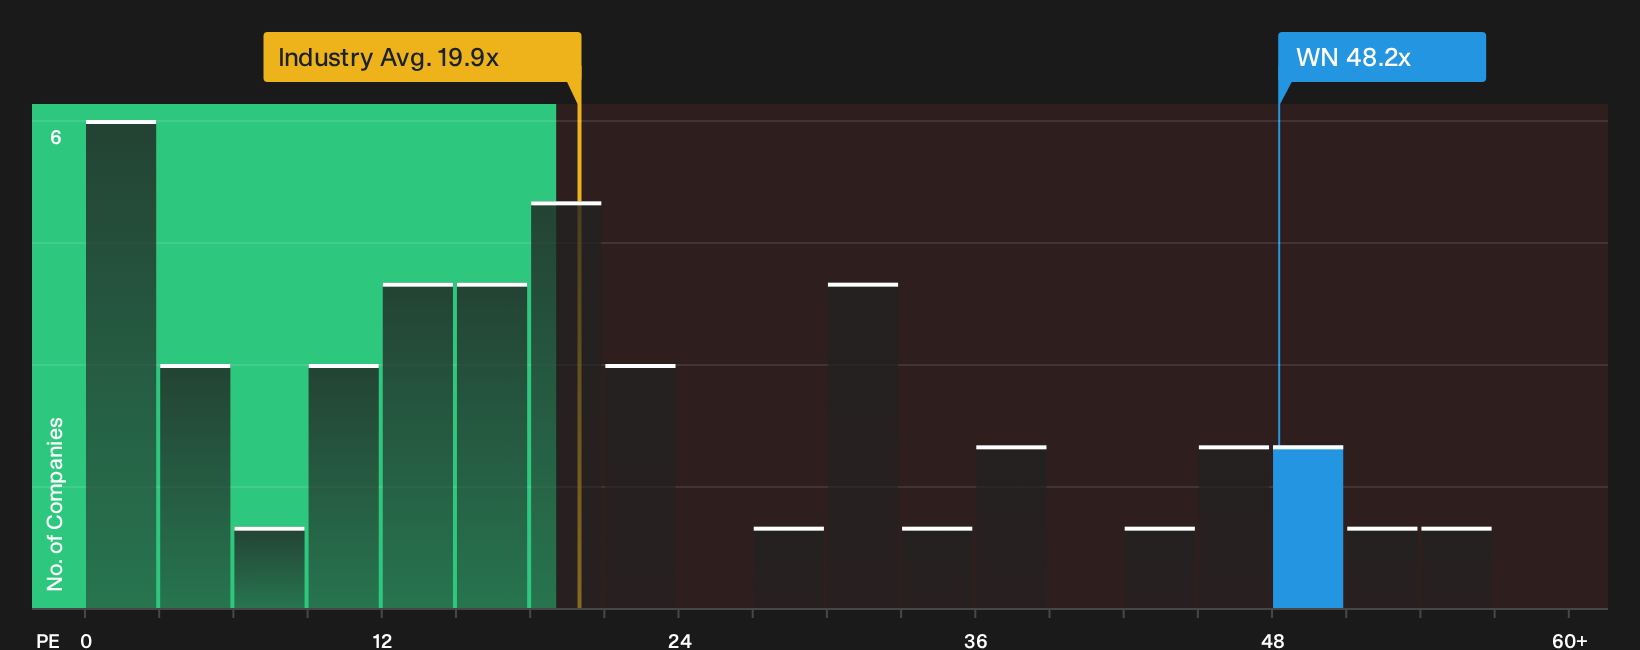
The 1.6% undervaluation argument becomes less compelling when George Weston is viewed through its P/E. The shares trade on 48.2x earnings compared with 19.9x for the North American consumer retailing group and 30.7x for peers. The fair ratio is 35.6x, which suggests there may be meaningful valuation risk if sentiment cools.
Investors comparing these gaps with the holdco story and analyst targets may want to stress test their own assumptions on earnings quality, growth and re rating potential. This may be particularly important before relying too heavily on a modest discount to fair value, or the consensus target, as a comfort zone for new capital.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the George Weston story, with both pressure points and bright spots, make this a moment to move quickly and test the evidence yourself. To weigh those cross currents in a structured way, start with the 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond George Weston?
If George Weston has sharpened your appetite for quality opportunities, do not stop here. A few focused stock lists can quickly broaden your watchlist.
- Target resilient return potential by checking companies with strong fundamentals through the list of solid balance sheet and fundamentals (6 results).
- Hunt for quality at a compelling entry point by scanning the 5 high quality undervalued stocks.
- Prioritise smoother ride potential and capital protection by focusing on the 9 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com