


EN
Is American Healthcare REIT (AHR) Still Below Fair Value As Earnings Estimates Rise?
Recent estimate revisions for American Healthcare REIT (AHR), including higher full-year earnings forecasts and projected double digit quarterly growth, have pushed this healthcare landlord onto more investor watchlists ahead of its next results.
That optimism has already shown up in the chart, with American Healthcare REIT’s 1-month share price return of 11.69% and year-to-date share price return of 19.33% helping lift the stock to US$56.37. Its 1-year total shareholder return of 22.15% points to momentum building rather than fading.
Scan the momentum in healthcare real estate by comparing American Healthcare REIT with hand picked peers through the list of solid balance sheet and fundamentals (25 results).
American Healthcare REIT has momentum and a sizeable healthcare footprint, but a fast move to US$56.37 invites a tougher question: Are you paying up for quality, or is there still clear value on the table?
Most Popular Narrative: 12% Undervalued
Against the last close at $56.37, the most followed narrative pins American Healthcare REIT’s fair value at about $64.40. This frames the current debate as less about momentum and more about how long its growth engine can run.
The combination of a rapidly growing 80+ demographic and a multi-year period of low new supply in senior housing and skilled nursing is expected to drive a persistent supply-demand imbalance, fueling both occupancy gains and rent growth across American Healthcare REIT's portfolio. This dynamic should underpin above-trend revenue and net operating income growth over the next decade.
See why 8 investors see American Healthcare REIT as 12% undervalued.
Analysts behind this narrative use a 7.28% discount rate and arrive at a fair value of $64.40, which is about 12.5% above the prevailing share price and roughly in line with the $63.69 price target implied by their updated work. Their case leans on forecast annual revenue growth of around 17.3% and an earnings growth profile of 26.5% a year, paired with a projected profit margin of about 8.3% versus current levels near 4.8%.
The same story expects American Healthcare REIT to reach revenue of about $4.0b and earnings of roughly $336.3m by 2029, with the stock valued on a P/E of 63.1x in that year. That multiple compares with a 29.8x level cited for the US Health Care REITs group. The thesis effectively assumes the market will keep assigning American Healthcare REIT a sizeable premium while margins and earnings expand.
For investors weighing that view, the key swing factors are already laid out. The narrative relies on tight supply in senior housing, further mix shift into higher rate payors, and ongoing portfolio upgrades. It also flags reimbursement risk, slower growth once occupancy normalizes, integration challenges on new assets, and tougher comparisons from 2025 onward.
Result: Fair Value of $64.40 (UNDERVALUED)
Still, the bullish case for American Healthcare REIT rests on assumptions that could crack if senior housing occupancy plateaus or reimbursement terms for long term care tighten.
Find out about the key risks to this American Healthcare REIT narrative.
Another View: American Healthcare REIT Looks Expensive On Earnings
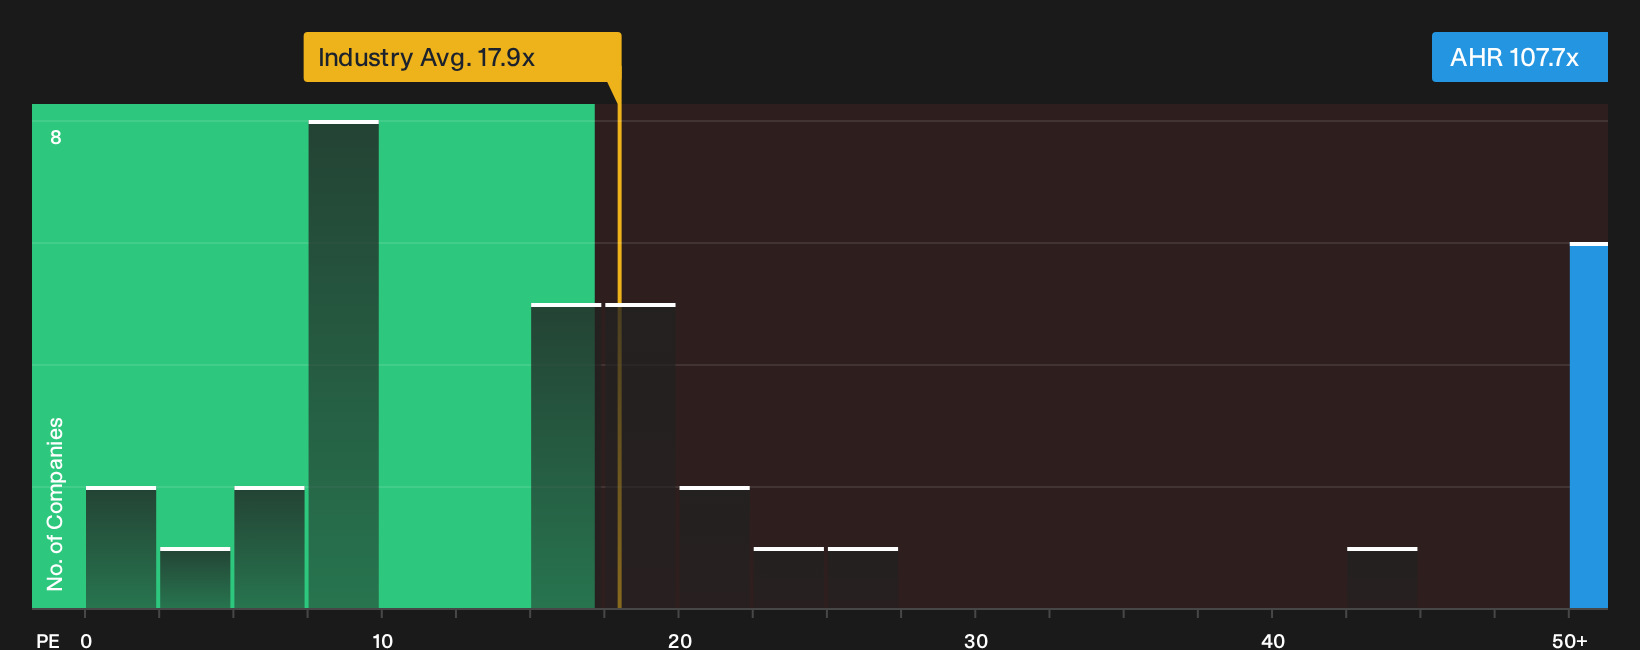
The story changes when you look at American Healthcare REIT through its P/E. At 107.7x, the ratio is far above the Global Health Care REITs average of 17.9x, the US peer average of 39.4x, and the fair ratio of 46.1x that the market could move toward. That kind of gap can be read as optimism priced in or as valuation risk that leaves less room for future disappointments. Which side of that trade are you more comfortable owning?
To stress test this earnings-based view against cash flow assumptions, take a closer look at how the SWS model treats American Healthcare REIT using the See what the numbers say about this price — find out in our valuation breakdown..
Here is how American Healthcare REIT’s valuation on this metric compares with its sector peers visually, through the
Next Steps
Mixed views on American Healthcare REIT so far. If you want to move quickly and decide where you stand, consider weighing both the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond American Healthcare REIT?
If American Healthcare REIT has your attention, do not stop here. Broaden your watchlist now so you are not chasing the crowd later.
- Target potential mispricing by scanning companies that score well on quality yet still trade below intrinsic value through the 34 high quality undervalued stocks.
- Secure steadier cash flow potential by reviewing income-focused opportunities screened as 5 dividend fortresses.
- Prioritize resilience by concentrating on financially robust businesses highlighted in the 31 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com