


EN
Evergy (EVRG) Gets A Zacks Lift, Is It Still Undervalued?
Evergy (EVRG) has drawn fresh attention after Zacks assigned the utility a Rank #2 rating. Its consensus EPS estimate for the current year edged 0.4% higher over the past 3 months.
Evergy’s share price has been firming, with the stock at $86.21 and a 1-month share price return of 9.0% contributing to a 17.97% year-to-date share price gain. Total shareholder return of 16.21% over 1 year and 96.50% over 3 years points to momentum that has built over time rather than appearing overnight.
Scan for other utilities showing similar momentum and earnings revision trends as Evergy by checking the curated 41 power grid technology and infrastructure stocks focused on the same corner of the market.
Evergy’s recent climb invites a simple question. Are investors finally catching up to what the utility’s earnings profile already suggests, or has sentiment just sprinted ahead of the fundamentals that support this valuation reset?
Most Popular Narrative: 3% Undervalued
The most followed valuation narrative for Evergy pegs fair value at $89, slightly above the last close at $86.21. This points to a mild discount that investors are now testing with stronger momentum in the share price.
The current valuation implies investors are pricing Evergy as if the company’s data center led growth, 2026 to 2030 capital plan and targeted equity issuance will support stronger long term earnings without undue pressure on its balance sheet or customer rates.
See why 15 investors see Evergy as 3% undervalued.
Result: Fair Value of $89 (UNDERVALUED)
Still, Evergy’s heavy capital plan and reliance on large data center contracts mean that slower project execution or weaker load ramp could quickly challenge this 3% undervalued story.
Find out about the key risks to this Evergy narrative.
Another View: Evergy On earnings multiples
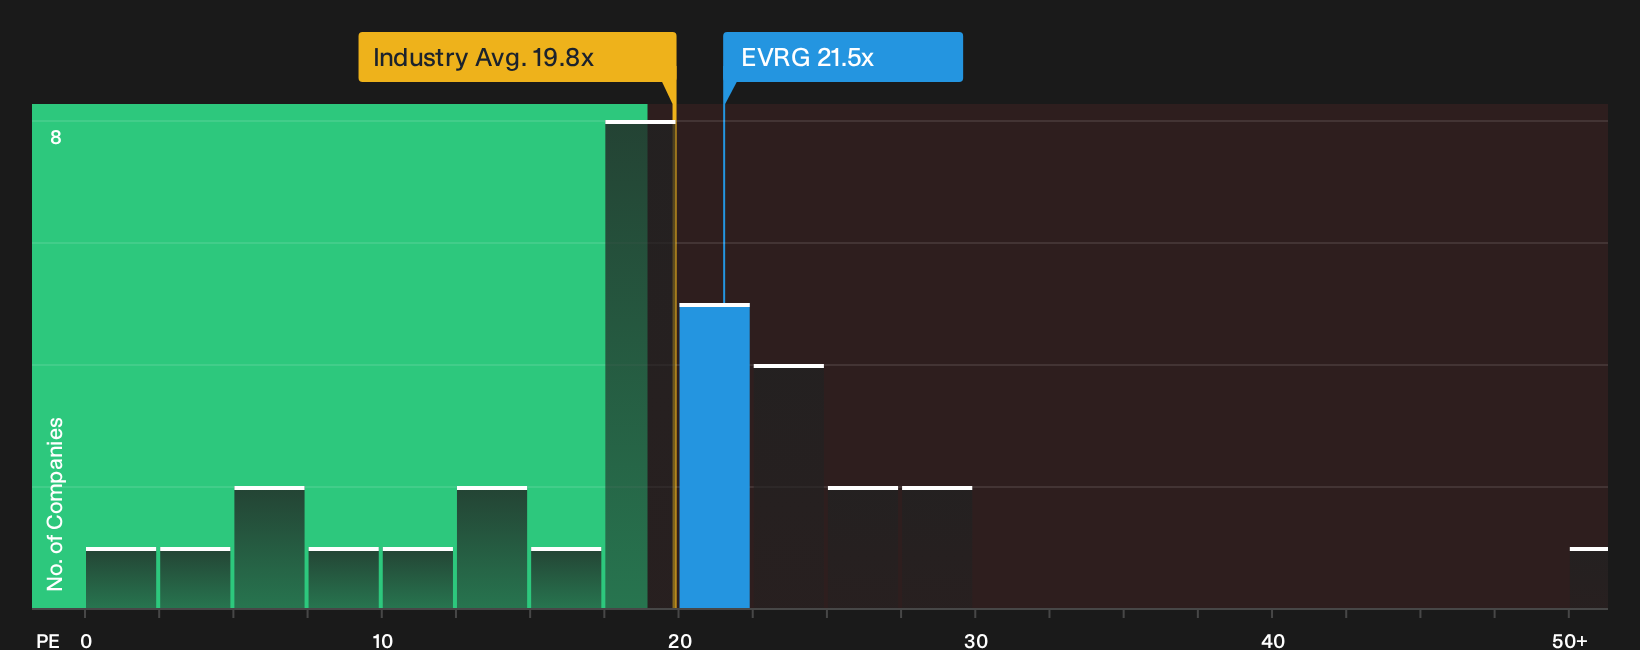
The 3% undervalued fair value story leans on analyst forecasts and long term growth assumptions. A simple check against earnings tells a different story. Evergy trades on a P/E of 21.5x, above both US Electric Utilities at 19.8x and its peer group at 17.7x, which raises the bar for future delivery.
The fair ratio for Evergy sits at 21.6x, almost identical to the current 21.5x. That points to a stock already priced close to what the market could move towards rather than one obviously mispriced. For an investor weighing risk and reward, the real question is how much cushion that leaves if expectations are later trimmed.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of caution and optimism around Evergy feels familiar, consider taking action while the details are fresh and test the story against your own thresholds with the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Evergy?
Do not stop with Evergy. Broaden your watchlist now and pressure test your portfolio by lining it up against other opportunities with different risk and return profiles.
- Target stability first and stress test your downside by reviewing a curated 31 resilient stocks with low risk scores that prioritizes resilience over excitement.
- Hunt for pricing gaps where quality and valuation still line up by scanning the focused 34 high quality undervalued stocks built to highlight potential mispricings.
- Zero in on balance sheet strength and stay picky about fundamentals by working through the detailed list of solid balance sheet and fundamentals (25 results) before committing fresh capital.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com