


EN
Does Earnings Beat Change The Bull Case For ONsemi Stock (ON)?
- ON Semiconductor reported third quarter 2026 sales of US$1,722.3 million and net income of US$313.9 million, and then issued fourth quarter guidance for revenue between US$1.715b and US$1.815b, describing the midpoint as above seasonal growth.
- Management highlighted a 175% year over year increase in AI data center revenue, raised its 2030 AI data center target to more than US$3b, and agreed to acquire Ferric for up to US$775 million to expand its position in AI power management.
- The next step is to examine how ON Semiconductor's stronger AI data center outlook and the Ferric acquisition could reshape its investment narrative.
Scan how ON Semiconductor's AI data center push compares with other chipmakers by reviewing our hand picked list of 53 AI infrastructure stocks in the same theme.
ON Semiconductor Investment Narrative Recap
To own ON Semiconductor stock, an investor needs to believe the pivot toward AI data centers, higher value power products and a leaner manufacturing footprint will matter more than the ups and downs in autos or broader semis. The latest quarter and above seasonal Q4 revenue outlook keep that execution story intact, with AI data center demand now a clear operational focus.
The key near term catalyst is whether ON Semiconductor can keep filling fabs with AI and industrial volume while auto shipments remain temporarily constrained by supply reallocation. The biggest current risk is that utilization or product mix slips below plan, which would pressure the margin improvement targets management has laid out.
The acquisition of Ferric sits in the middle of this catalyst versus risk balance. Ferric brings integrated voltage regulator technology that fits directly into ON Semiconductor's push to serve the full power path for AI processors, and it is a concrete way to support the higher 2030 AI data center revenue target above US$3b.
For you as a shareholder, the question is whether ON Semiconductor can integrate Ferric cleanly while also managing the rephased automotive orders and the planned Synaptics cash deal. Execution on these moving pieces will strongly influence how quickly AI data center and industrial growth, plus Fab Right actions, translate into the higher margin and cash generation profile that management is working toward.
ON Semiconductor's narrative projects US$9.0b revenue and US$2.5b earnings by 2029, based on analysts' models. This projection assumes 13.1% yearly revenue growth and an earnings increase of about US$1.9b from US$630.2m today.
Uncover why ON Semiconductor's fair value indicates a 43% potential upside to its current price that could narrow quickly.
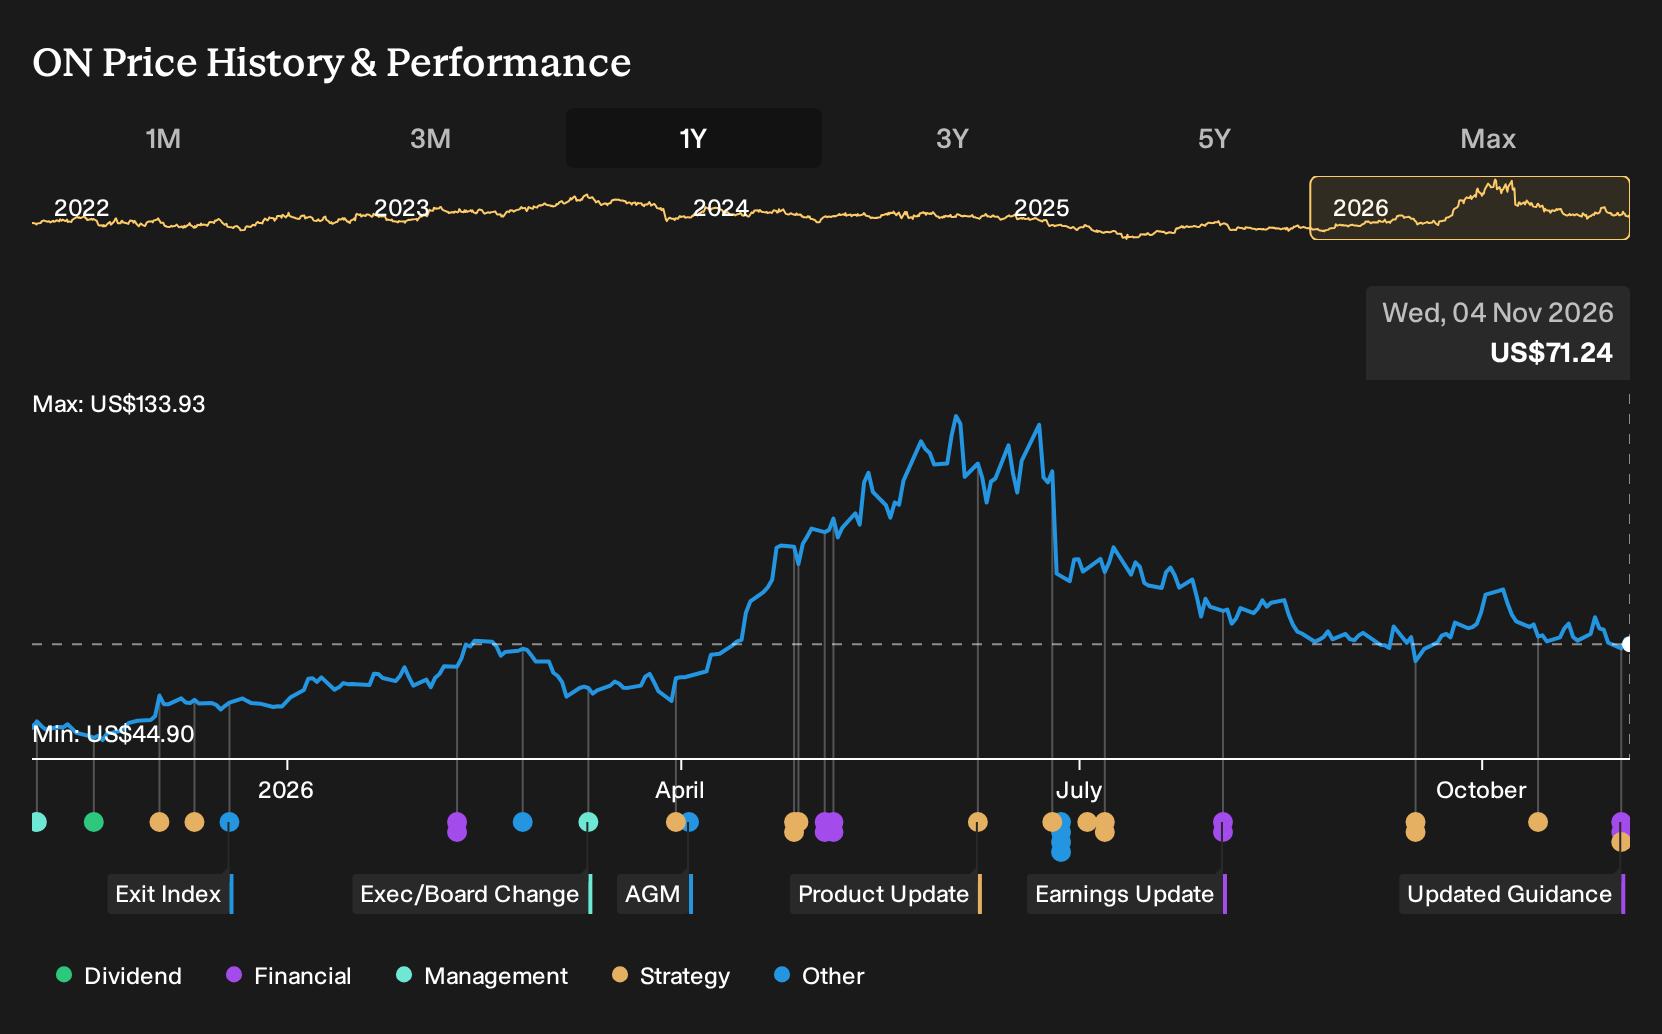
Exploring Other Perspectives
One alternate view on ON Semiconductor focuses on AI data center adoption risk. Some of the lowest analysts were assuming revenue of about US$8.7b and earnings near US$2.2b by 2029, well below the bullish US$3.0b earnings case. That gap shows how far opinions can stretch, and why you may want to compare several narratives that could shift after this latest guidance and the Ferric deal.
Explore 3 other ON Semiconductor fair value estimates, including one that suggests it could be worth just $75.28.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your ON Semiconductor research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for ON Semiconductor. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ON Semiconductor's overall financial health at a glance.
Looking for more ON Semiconductor sized investment ideas?
If you want to put ON Semiconductor in context, it helps to look across a wider field of opportunities using the Simply Wall St Screener. You can compare business quality, balance sheet strength and income potential in a structured way instead of working through tickers one by one.
- For investors who care most about financial resilience, start with a list of solid balance sheet and fundamentals (25 results) that can handle shocks and still fund future growth.
- If upside potential is your priority, focus on our 34 high quality undervalued stocks that combine strong fundamentals with prices that analysts view as below their estimated worth.
- For those building income focused portfolios, scan a curated 5 dividend fortresses that aims to pair higher yields with businesses seeking consistent payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com