


EN
ICL Group (ICL) Following Mosaic’s Miss, Does The Valuation Case Still Hold
Mosaic’s quarterly loss and earnings miss put fertilizer producers under closer scrutiny, and attention quickly shifted to ICL Group (NYSE:ICL) as investors look ahead to its upcoming earnings release.
ICL Group’s share price closed at US$4.58 after a 1-day share price return of 5.05%. However, the 30-day and year-to-date share price returns are down 9.49% and 20.90% respectively, with a 1-year total shareholder return decline of 29.26%. This points to fading momentum even as investors react to Mosaic’s loss and reassess sector risk ahead of ICL’s own earnings update.
Scan beyond ICL Group’s earnings setup and stress test your fertilizer exposure with a curated list of peers on the list of solid balance sheet and fundamentals (25 results).
Bulls point to ICL Group’s value score and pricing below some estimates, while bears focus on long-run share price weakness. Which side does the current valuation actually support as earnings approach?
Price-to-Earnings of 19.4x: Is it justified?
ICL Group closed at $4.58 while screening on a P/E of 19.4x that sits below both the US chemicals sector and its direct peer group. This points to a valuation that is not demanding compared with similar fertilizer producers.
The P/E ratio shows what investors are currently paying for each dollar of earnings. For a minerals and chemicals supplier like ICL Group, which operates across potash, phosphate and specialty fertilizer solutions, that earnings multiple gives a quick read on how the market is weighing its profit profile against other listed chemical businesses.
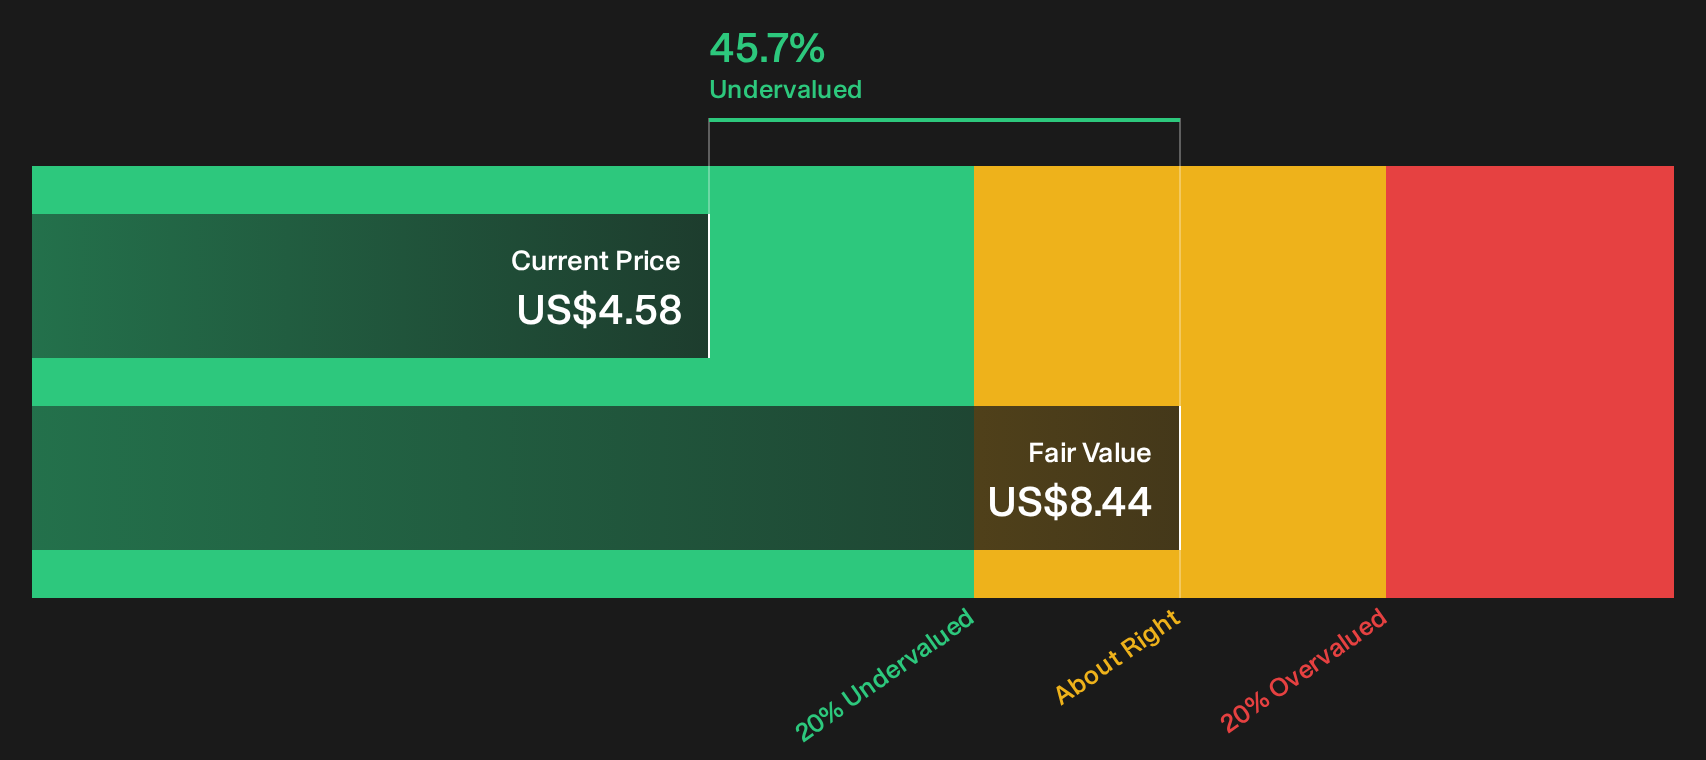
ICL Group is flagged as good value on this measure because its 19.4x P/E is lower than the US chemicals industry average of 22.9x and also below the peer group average of 26x. The gap is clear and suggests the market is attaching a lower earnings multiple to ICL despite analysts being in tight agreement that the target price sits more than 20% above the current share price and that the stock trades at a 45.7% discount to an internal fair value estimate based on future cash flows.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 19.4x (UNDERVALUED)
Still, ICL Group’s long stretch of weak multi year returns, along with its exposure to cyclical fertilizer demand, could quickly challenge any undervaluation thesis if earnings disappoint.
Find out about the key risks to this ICL Group narrative.
Another view on ICL Group’s value
The P/E paints ICL Group as modestly priced, yet our DCF model tells a stronger story. On that framework, the stock at $4.58 trades at a 45.7% discount to an estimated $8.44 fair value, which frames a very different risk and reward balance. Which lens do you trust more as earnings near?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out ICL Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 34 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around ICL Group is clearly split, with pressure from recent returns on one side and valuation support on the other. Now is the time to review the data yourself, weigh the trade off between its potential and its vulnerabilities, and decide where you stand by checking the 2 key rewards and 4 important warning signs.
Looking for more investment ideas beyond ICL Group?
If ICL Group has sharpened your focus on valuation and risk, you can keep that momentum going by lining up a few more high conviction watchlist candidates.
- Target bargain opportunities with solid fundamentals by scanning the 34 high quality undervalued stocks before others price in the same potential.
- Protect your downside first by combing through the 31 resilient stocks with low risk scores and concentrating on resilience when markets turn choppy.
- Spot future leaders early by working through the 19 high quality undiscovered gems while they still sit off most investors’ radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com