


EN
Voya Financial (VOYA) Could Be 3% Undervalued After Earnings And Higher Buybacks
Voya Financial (VOYA) just posted third quarter 2026 results that combined modest revenue pressure with higher net income, while pairing those figures with a higher dividend and an expanded share repurchase plan.
The recent earnings release and capital return moves come on top of a strong run for Voya Financial, with the share price closing at $104.63 after a 1-day share price return of 1.47% and a 7-day share price return of 8.36%, which points to building short-term momentum.
That near term strength sits alongside a 38.40% year to date share price return and a 50.64% 1-year total shareholder return. Together, these figures suggest investors have been reassessing both the earnings profile and the risk around the business as activism, a higher dividend, and increased buybacks have all hit the tape in quick succession.
Scan how other financials are reacting to activism, higher dividends, and buybacks by reviewing the hand picked 34 high quality undervalued stocks that share similar capital return themes with Voya Financial.
Voya Financial now has improving profitability, a higher dividend, and an activist spotlight. The business looks stronger. The open question is whether the recent share price jump still leaves enough value on the table.
Most Popular Narrative: 3% Undervalued
Voya Financial closed at $104.63, compared with a widely followed narrative fair value of $108.08 that uses an 8.13% discount rate. This framework ties that gap directly to earnings power, cash generation, and capital returns rather than short term trading momentum.
The expanding workplace-centric ecosystem, with about 1.3b of combined assets across Retirement and Investment Management and access to more than 50,000 employers and 18 million customers, gives Voya Financial more scope to move retirement participants into wealth and investment products, which can support higher fee revenue and more durable earnings.
See why 4 investors see Voya Financial as 3% undervalued.
Result: Fair Value of $108.08 (UNDERVALUED)
Still, the Voya Financial story can wobble if earnings again miss expectations, or if weaker alternative investment returns keep adding noise to quarterly results.
Find out about the key risks to this Voya Financial narrative.
Another View: What Voya Financial’s P/E Is Telling You
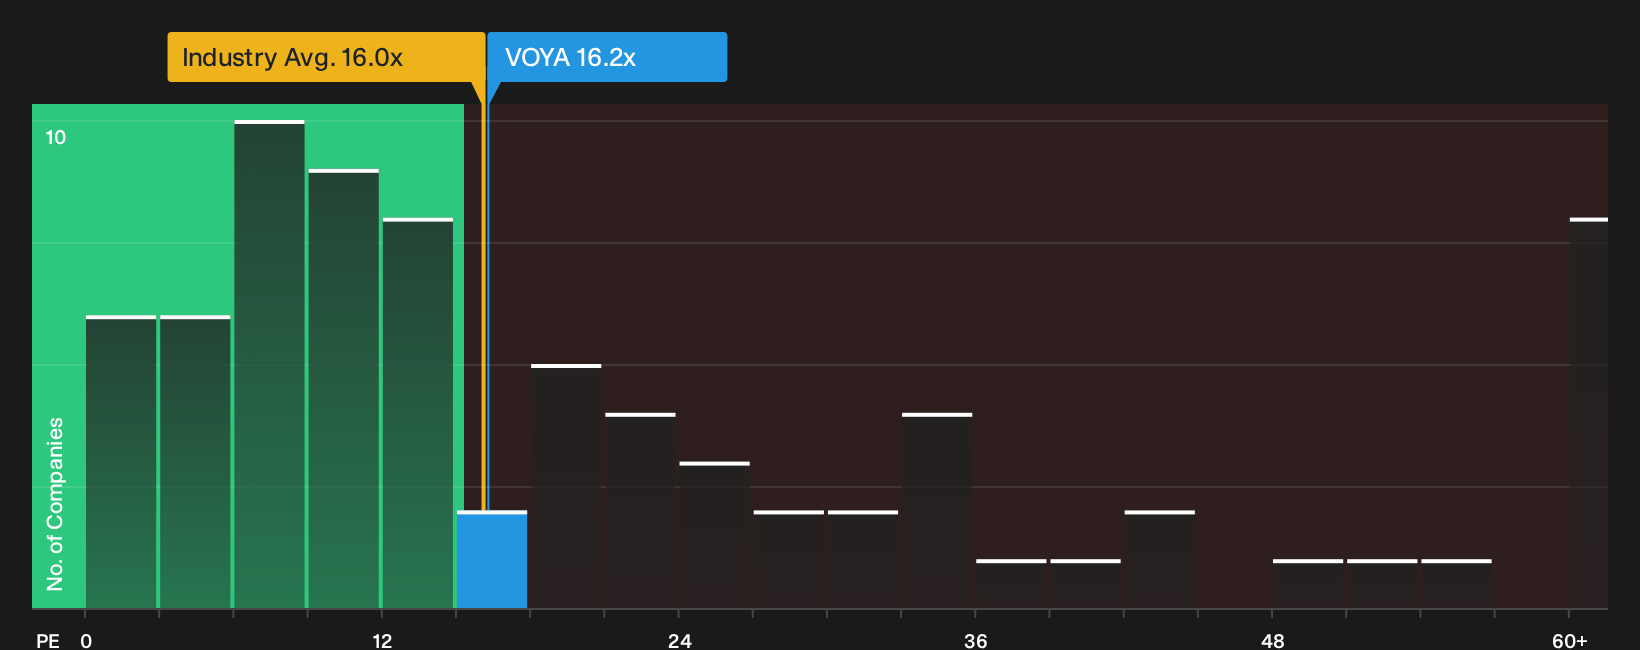
The SWS DCF model points to upside for Voya Financial, yet the simple earnings multiple sends a cooler message. VOYA trades at a P/E of 16.2x, compared with both a 16.1x fair ratio and a 16x industry average, as well as a 13.3x peer mean. That setup leans closer to fully priced and leaves you asking whether the margin of safety is now in the story or already in the tag.
To see how this earnings based view lines up with cash flow estimates, take a closer look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If this mix of optimism and caution around Voya Financial feels familiar, do not sit on the fence. Check the 3 key rewards and weigh those positives against your own expectations before you decide what the story really is.
Looking for more investment ideas beyond Voya Financial?
Do not let your research stop at Voya Financial. Use the Simply Wall Street Screener to quickly spot other opportunities that fit your risk and return goals.
- Target resilient balance sheets and steady fundamentals by reviewing the list of solid balance sheet and fundamentals (25 results) that match your preference for financial strength.
- Hunt for potential mispricing by scanning the 34 high quality undervalued stocks where quality and valuation line up more tightly.
- Focus on income potential and stability by checking the 5 dividend fortresses offering higher yields with supporting fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com