


EN
Home Depot (HD) Stock Could Be 29% Overvalued Following Housing Rally
Home Depot shares have moved sharply in recent weeks, and the question now is whether the current price lines up with the cash the business is expected to generate over time. With the stock having already delivered a meaningful return for holders in recent years, the key issue for anyone looking at it today is how that share price relates to the underlying cash flows.
- Over the past 3 years, Home Depot has delivered a total return of 29.7%, which puts real weight on whether the current valuation is fully backed by the cash the company can produce.
- Recent housing focused headlines, from a rally in related stocks after the US midterm elections to policy efforts on affordability, may support expectations for future demand at Home Depot, which matters because any shift in housing activity can change the timing and durability of its cash flows.
- Prefer to judge Home Depot on earnings? See why Home Depot's 24.9x P/E tells a different valuation story.
The stock's next move may depend on whether today's share price is adequately supported by Home Depot's projected cash flows when set against its intrinsic value estimate.
If you want more than one housing related idea on your radar, a focused stock screen built around 41 power grid technology and infrastructure stocks can be a useful next step in your research.
Is Home Depot Getting Expensive on Cash Flow?
The Discounted Cash Flow (DCF) model here projects what Home Depot might deliver in future free cash to shareholders and then discounts it back to today in dollar terms. The company generated last twelve month free cash flow of about $15.2b, and the forecast path assumes that cash generation continues to grow rather than shrink, with estimates stretching out over the next decade.
Those projections still leave the DCF estimate meaningfully below the current share price of $355.44. This signals that investors are already paying up for Home Depot’s position in home improvement and its cash profile. Recent housing focused optimism after the US midterm elections, including hopes for affordability policies that could support renovation demand, helps explain why the market is comfortable valuing the stock above what the discounted cash flows currently justify. Find out what Home Depot could be worth using our Discounted Cash Flow (DCF) estimate.
The Home Depot Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation puzzle leaves off for Home Depot, explaining in clear terms which paths for future growth, margins and earnings would need to hold for the shares to be worth materially more or less than today’s price. They sit on Home Depot's Community page and turn a single output from a ratio or model into a set of real world assumptions you can later test against what the business actually delivers.
One of the top community narratives on Home Depot: 6% undervalued
"Expansion into specialty distribution through platforms like SRS, GMS, Construction Resources and the HVAC businesses is creating a broader Pro ecosystem…"
Discover why this Narrative puts Home Depot at 6% undervalued.
One more Home Depot check that does not show up in the cash flow math
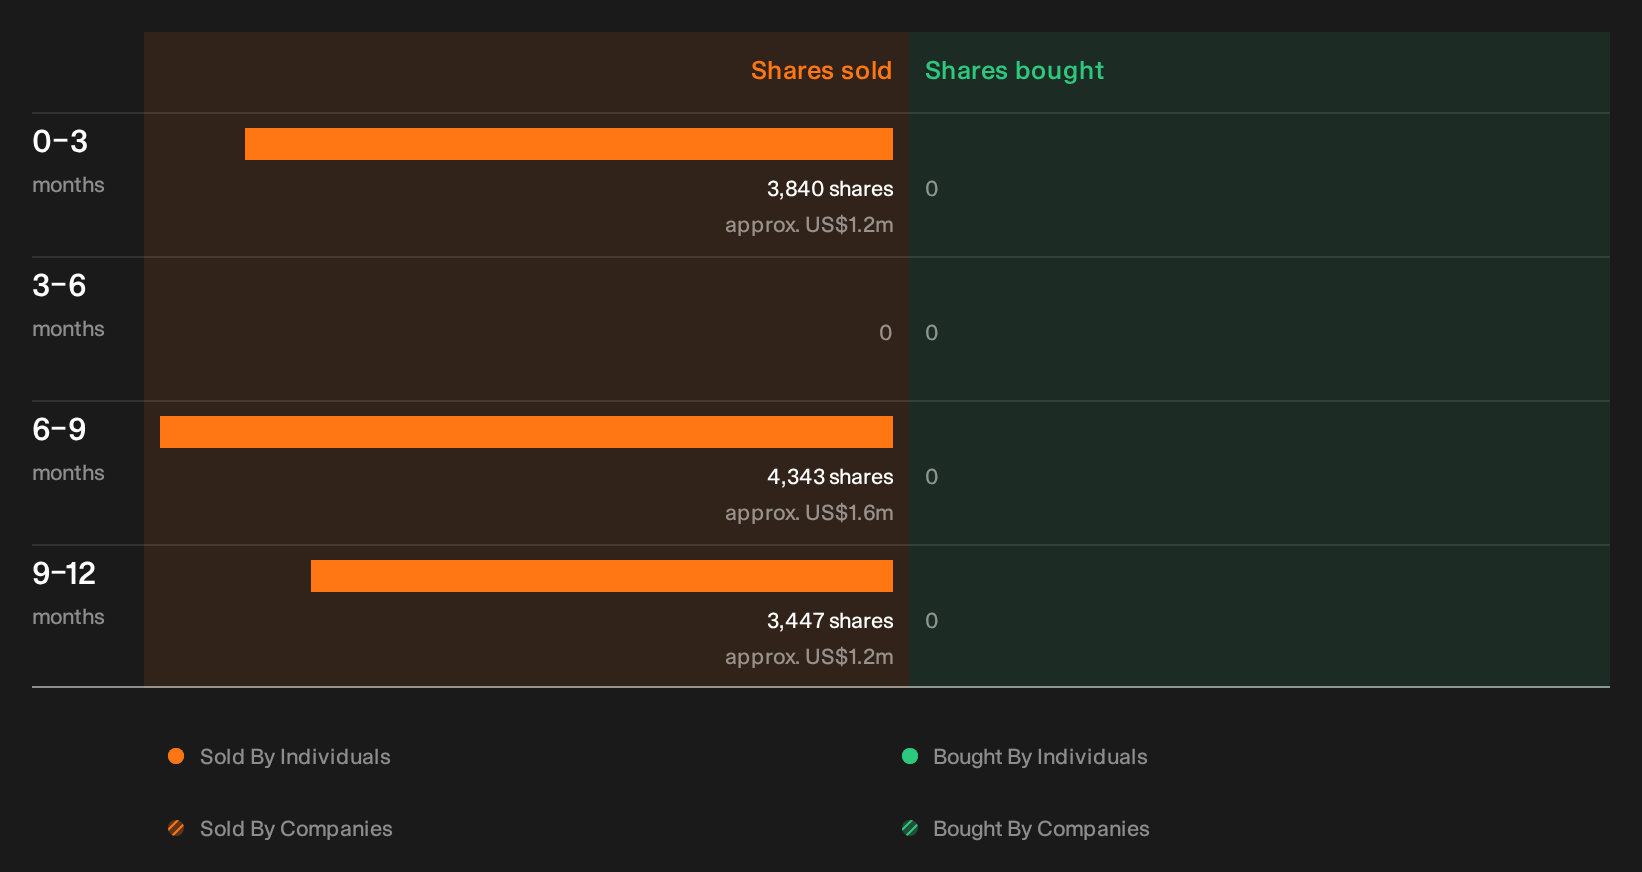
Price and projections tell only part of the story for Home Depot, because recent trading disclosures by people inside the business raise a fresh question about who has been selling and why. See the recent insider selling flagged for Home Depot.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com