


EN
Vistra (VST) Stock May Be A Bargain As Its Gas Fleet Grows
Vistra has pulled back sharply in recent months after a very large multi year climb, which puts fresh focus on whether the current share price still lines up with what its earnings can support. With the stock now well below its recent highs, the question for anyone looking at Vistra is how the latest moves in the business square with the valuation being placed on its profit stream.
- Over the past 5 years the stock has delivered a gain of roughly 7x. As a result, any change in expectations for the underlying earnings power may have an outsized effect on how sustainable that performance looks.
- The completed acquisition of Cogentrix Energy adds about 5,500 megawatts of natural gas capacity. This can influence how investors think about Vistra's future earnings mix, capital needs and the timing of cash flows from its expanded generation fleet.
- There is a second opinion on Vistra worth weighing. See what analysts think Vistra's shares could be worth.
The issue now is whether Vistra's current share price is adequately supported by the earnings power implied by these recent moves.
If you want a broader starting point for research alongside Vistra, consider running the same kind of earnings test across a curated list using the 34 high quality undervalued stocks
Is Vistra Still Cheap on Earnings?
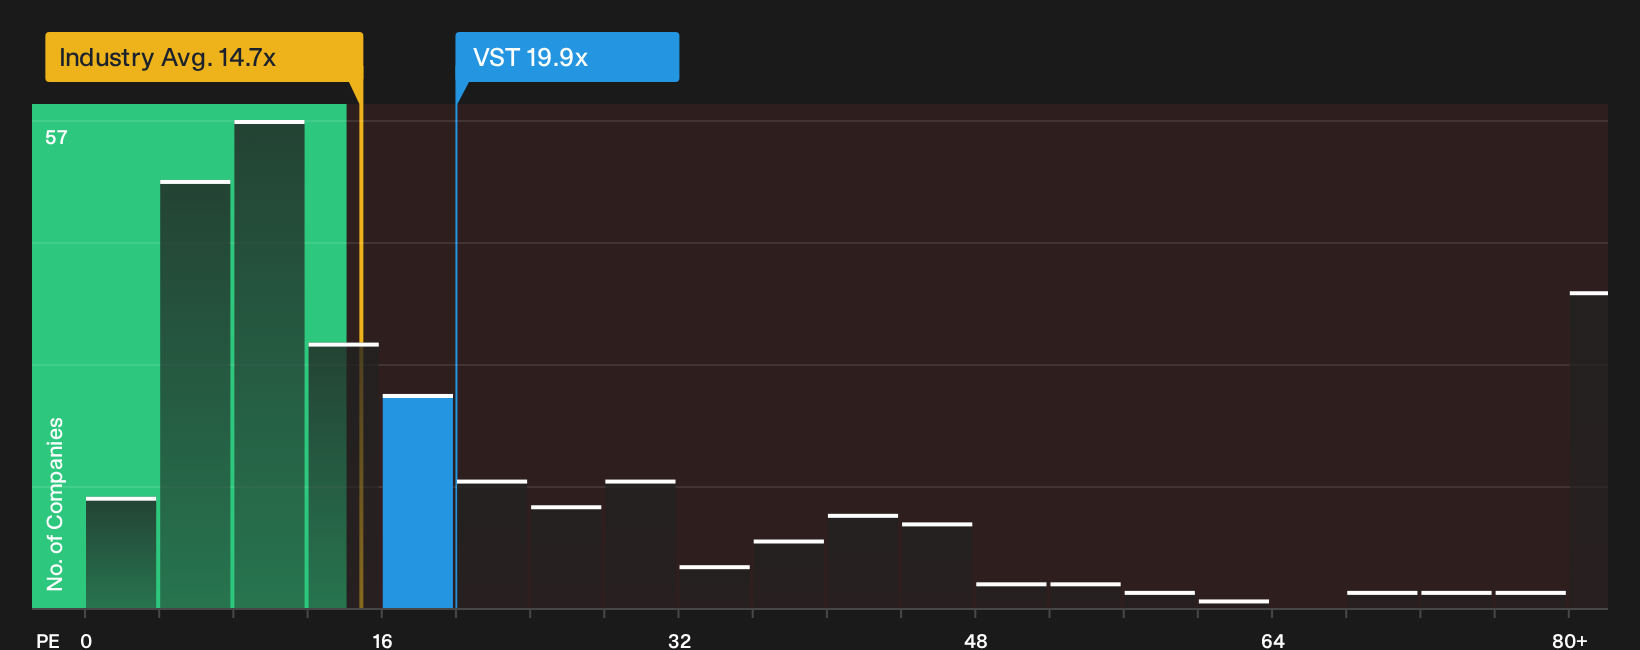
The P/E ratio works reasonably well for Vistra because earnings are a key focus for a capital intensive power producer. On this lens, the stock trades on a P/E of 19.9x, compared with a Renewable Energy industry average of 14.7x and a peer group around 16.8x. So the market is currently paying a higher price for each dollar of Vistra's earnings than it does for many similar businesses.
Because the recent Cogentrix acquisition expands Vistra's gas generation footprint, investors appear willing to assign a premium P/E multiple versus the benchmark the model suggests would be fair for the firm. The current ratio sits below that tailored fair multiple, which points to the shares screening as undervalued on this framework even after the recent run up and pullback. Despite the Cogentrix deal giving the company a larger and more diverse fleet, the stock still trades at a discount to what this earnings based model implies. Explore the numbers behind Vistra's P/E valuation.
The Vistra Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Vistra valuation puzzle leaves off by spelling out which paths for future growth, margins and earnings would need to play out for the stock to end up worth materially more or less than today. Each narrative treats fair value as a thesis about Vistra's business that can be revisited over time, and these viewpoints live on Simply Wall St's Community page rather than inside the core model.
One of the top community narratives on Vistra: 7% undervalued
"Layer in two investment-grade credit upgrades, S&P in December 2025, Fitch to BBB- in March 2026, and this stops sounding like a story about what AI might do to electricity demand someday…"
Discover why this Narrative puts Vistra at 7% undervalued.
One more Vistra signal investors should check before deciding
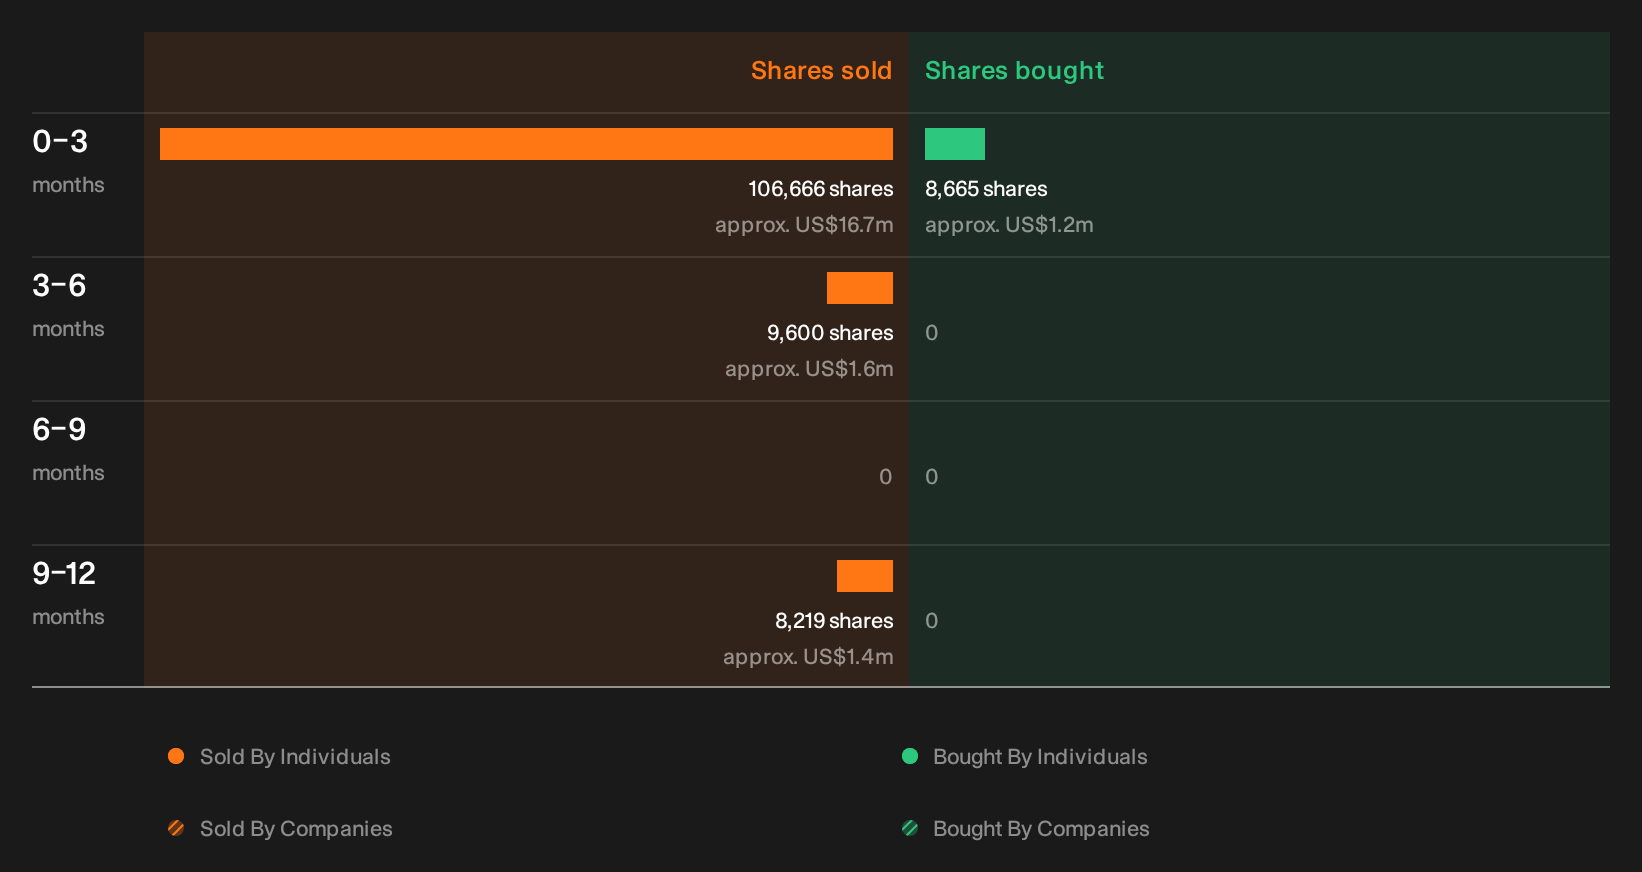
Before you lean too hard on the valuation work, it is worth knowing that recent trading by Vistra insiders has been flagged by our checks, with the specific sellers, transaction sizes and potential read throughs left for you to review. See the recent insider selling flagged for Vistra.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com