


EN
Cabot (CBT) Jumped, But What Is Driving Attention Now?
Cabot (CBT) has attracted investors’ attention after reporting fourth quarter earnings on 2 November 2026, with quarterly sales of US$1,009 million and net income of US$66 million from continuing operations.
Cabot’s recent earnings update and investments in battery materials have come against a mixed trading backdrop. The 1-day share price return of 4.31% lifted the stock to US$75.10 after a 90-day share price decline of 14.22% and a year-to-date share price gain of 12.01%, while longer-run total shareholder returns of 27.21% over 1 year and 46.16% over 5 years indicate that momentum has still rewarded patient holders.
Scan how Cabot’s earnings story compares with other materials players by jumping into our hand picked list of solid balance sheet and fundamentals (25 results) that may handle tougher conditions with fewer financial surprises.
Cabot now sits between two clear stories. One argues the recent jump and battery push justify a richer tag, while the other points to softer full year earnings. Which case does the current valuation support next?
Most Popular Narrative: 15% Undervalued
Cabot’s most followed narrative pegs fair value at $88.50, which sits above the last close of $75.10 and presents the recent rally as only a partial catch up to those expectations.
Battery Materials is growing quickly, supported by 43% year over year revenue growth and trailing 12 month EBITDA margins of about 24%. If this high margin, higher growth part of Cabot continues to scale while the market prices the business on more of a specialty materials profile, the share price could trend higher instead of staying flat as earnings and cash flow expand.
See why 1 investors see Cabot as 15% undervalued.
Result: Fair Value of $88.50 (UNDERVALUED)
Still, the whole story can unravel if battery materials underdeliver, or if weaker carbon black fundamentals continue to weigh on Reinforcement Materials for longer than bulls expect.
Find out about the key risks to this Cabot narrative.
Another View: Cabot Through a Cash Flow Lens
While the popular narrative sees Cabot as about 15% undervalued on earnings and analyst targets, the Simply Wall St DCF model sketches a cooler picture. On that framework, the shares at $75.10 sit above an estimated future cash flow value of $71, which screens as overvalued instead of cheap.
That gap between earnings based upside and cash flow caution leaves investors with a real question. Which signal feels more credible for you: the headline growth forecasts, or the harder to budge cash generation assumptions underpinning our DCF model?
Look into how the SWS DCF model arrives at its fair value.
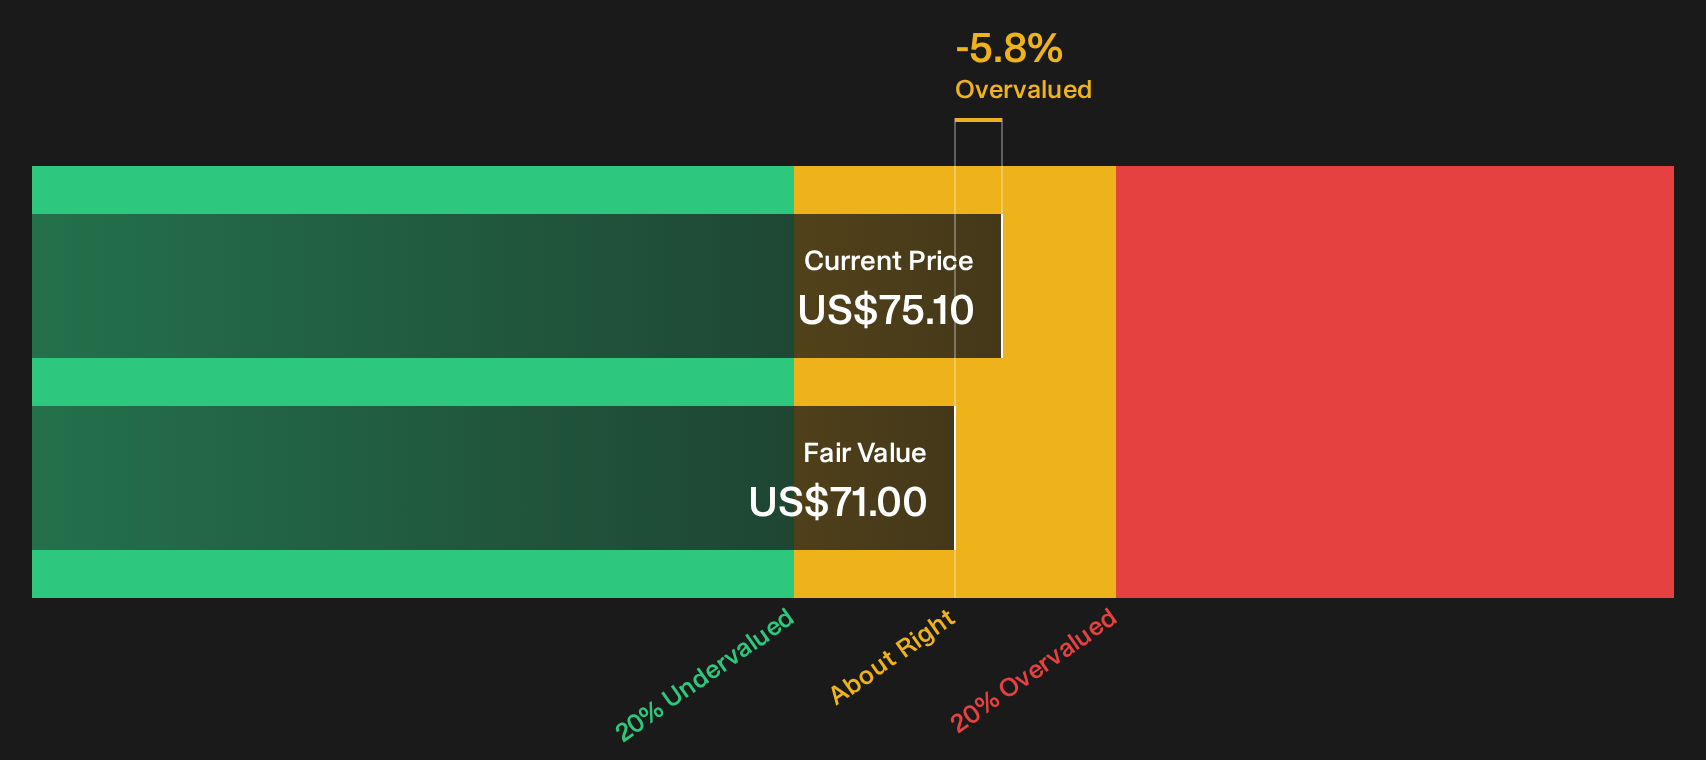
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Cabot for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 34 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Cabot’s value story can feel messy, so move quickly to inspect both sides of the argument and weigh the 4 key rewards and 3 important warning signs.
Looking for more ideas beyond Cabot?
If Cabot has sharpened your thinking, do not stop here. Fresh opportunities rarely wait around, so give yourself more quality options to compare.
- Target steadier potential outcomes by reviewing a 31 resilient stocks with low risk scores that aims to keep surprises on the downside in check.
- Hunt for quality at a discount through a 34 high quality undervalued stocks that filters for fundamentals first and price second.
- Zero in on resilient balance sheets using a 19 high quality undiscovered gems that highlights financial strength before momentum headlines arrive.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com