


EN
Hiscox (LSE:HSX) Looks Fully Valued After Q3 Premium Growth Keeps Guidance On Track
Hiscox (LSE:HSX) moved into focus after its Q3 2026 trading update, which flagged a 9.5% rise in insurance contract written premiums and progress toward upgraded guidance and long term retail growth targets.
That trading update landed after a strong run in the Hiscox share price, with a year-to-date share price return of 42.35% and a 1 year total shareholder return of 48.33% at a last close of £19.9. The 3 year total shareholder return of 119.30% and 5 year total shareholder return of 178.64% suggest that momentum has been building rather than fading.
Scan for other insurers showing similar momentum and balance sheet strength by reviewing our curated list of solid balance sheet and fundamentals (10 results) in conjunction with Hiscox's latest update.
After that kind of share price surge and a Q3 update that kept guidance on track, the question becomes simple: Does Hiscox still offer enough valuation upside to compensate you for the underwriting and cycle risk from here?
Most Popular Narrative: 1% Overvalued
The current Hiscox share price of £19.9 sits slightly above the most followed narrative fair value estimate of £19.68. The story now hinges on how capital returns, underwriting discipline and cost programmes play out against that small gap.
The current valuation suggests the share price already reflects a relatively full, positive view on Hiscox that factors in ongoing capital returns, structural cost benefits and sustained Retail growth.
Reinsurance rates declined by about 13% at the January 2026 renewal with further slight softening at April and some easing of terms and conditions. Efficient cycle management and capital allocation between own balance sheet and third party funds remain key levers for margins and fee income.
See why 12 investors see Hiscox as 1% overvalued.
Result: Fair Value of £19.68 (OVERVALUED)
Still, this narrative can crack if London Market losses combine with softer reinsurance pricing, or if heavy AI and change programme spending fails to deliver the expected efficiencies.
Find out about the key risks to this Hiscox narrative.
Another View: Hiscox Through The P/E Lens
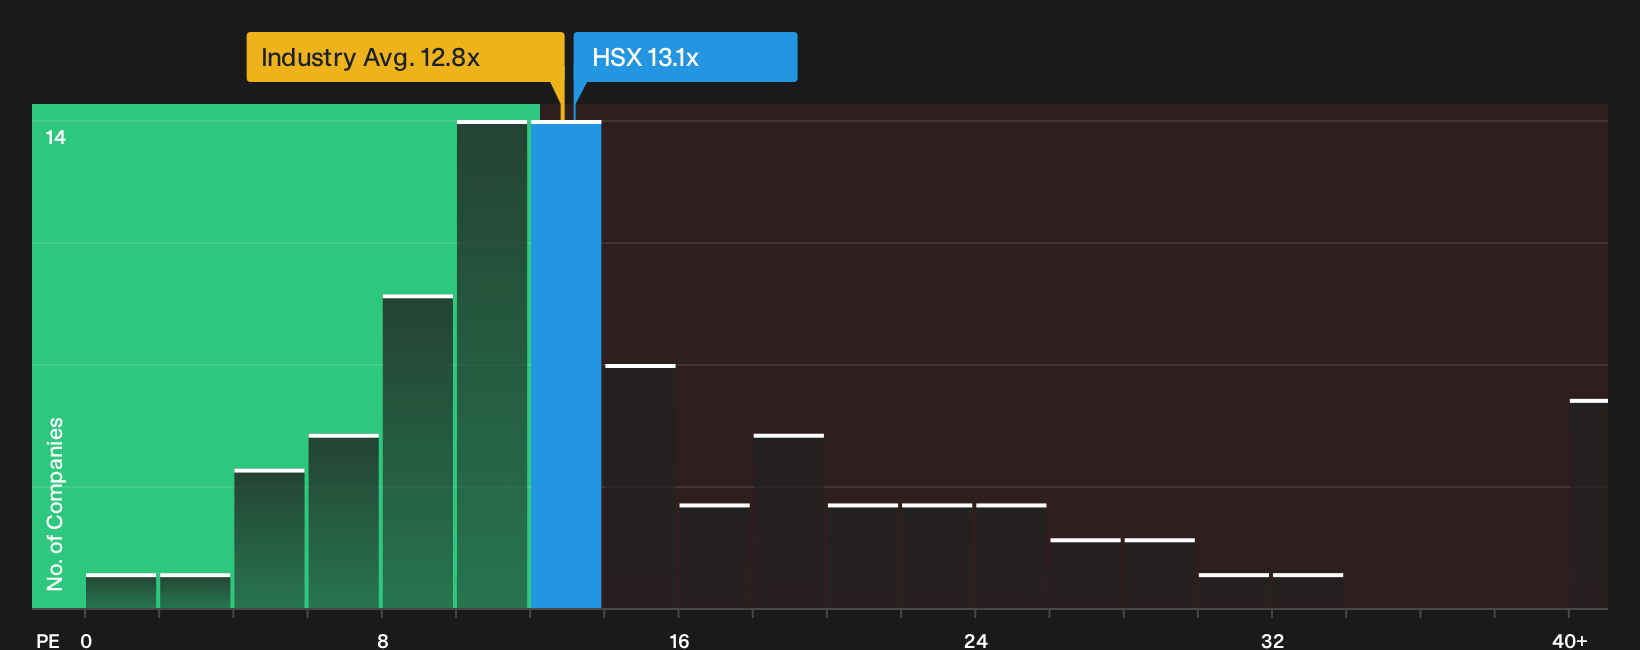
On price targets and fair value models, Hiscox looks only slightly ahead of the consensus narrative. On the plain P/E metric of 13.1x, the stock trades a touch above the European insurance group average of 12.8x but below its own fair ratio of 14.1x. That mix points to limited margin of safety but also some room for sentiment to shift toward the fair ratio if earnings keep tracking forecasts.
If you want to see how those P/E signals stack up against the detailed valuation work, take a closer look at the See what the numbers say about this price — find out in our valuation breakdown. next.
Next Steps
Sentiment around Hiscox so far looks cautiously optimistic, which means timing and context really matter for your next move. Act while the information is fresh and weigh the upside against the risks by checking the 3 key rewards.
Looking for more investment ideas beyond Hiscox?
If Hiscox has sharpened your focus, do not stop here. Put that momentum to work by scanning other opportunities that could fit your risk and return preferences.
- Target resilience in choppy markets by reviewing the 5 resilient stocks with low risk scores that have been screened for sturdier balance sheets and milder drawdowns.
- Hunt for strong businesses at appealing entry points by working through the 14 high quality undervalued stocks that pair healthier cash flows with more grounded valuations.
- Build a watchlist of potential income pillars by shortlisting the 3 dividend fortresses that combine higher yields with a focus on sustainability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com