


EN
Hudbay Minerals (TSX:HBM) Pushes Ahead With Copper World As Undervalued Narrative Holds
Hudbay Minerals (TSX:HBM) has moved ahead with construction of its Copper World copper project in Arizona, a roughly US$2.1 billion mine that aims to sidestep federal permits by operating on private land.
Recent trading tells a mixed story for Hudbay Minerals. The share price is CA$31.03 after a 1-day share price return of 3.36%, yet the 30-day share price return is down 20.29% and the 90-day move is down 15.98%, even as the year-to-date share price return is 12.43%. Over a longer horizon, momentum has still rewarded patient holders, with a 1-year total shareholder return of 40.72% and a very large 3-year total shareholder return. This indicates that sentiment around projects like Copper World has already been a key part of how investors value the business.
Scan Hudbay Minerals alongside other copper focused plays using the hand picked 16 top copper producer stocks, which zeroes in on producers tied directly to new mine development and long term supply themes.
Hudbay Minerals has just committed to a US$2.1b build while the share price has cooled off from recent highs. Does that recent pullback offer a reasonable entry now, or does patience still look safer until the valuation section can stack up the numbers?
Most Popular Narrative: 32% Undervalued
Hudbay Minerals closed at CA$31.03 against a widely followed fair value estimate of about CA$45.35. The current pullback therefore sits against a narrative that still sees meaningful upside based on its copper and gold pipeline and balance sheet strength.
The combination of record trailing twelve month adjusted EBITDA of about US$1.3b, more than US$400 million of free cash flow, and a net cash position of roughly US$80 million gives Hudbay Minerals scope to fund its growth pipeline and maintain its capital allocation framework. This can influence future net margins and earnings through disciplined investment and potential returns of capital.
See why 38 investors see Hudbay Minerals as 32% undervalued.
Result: Fair Value of CA$45.35 (UNDERVALUED)
Still, the Hudbay Minerals story can shift quickly if fuel and consumables stay expensive, or if Copper World’s higher upfront capital meaningfully weakens its projected economics.
Find out about the key risks to this Hudbay Minerals narrative.
Another View: What Hudbay Minerals’ P/E Is Really Saying
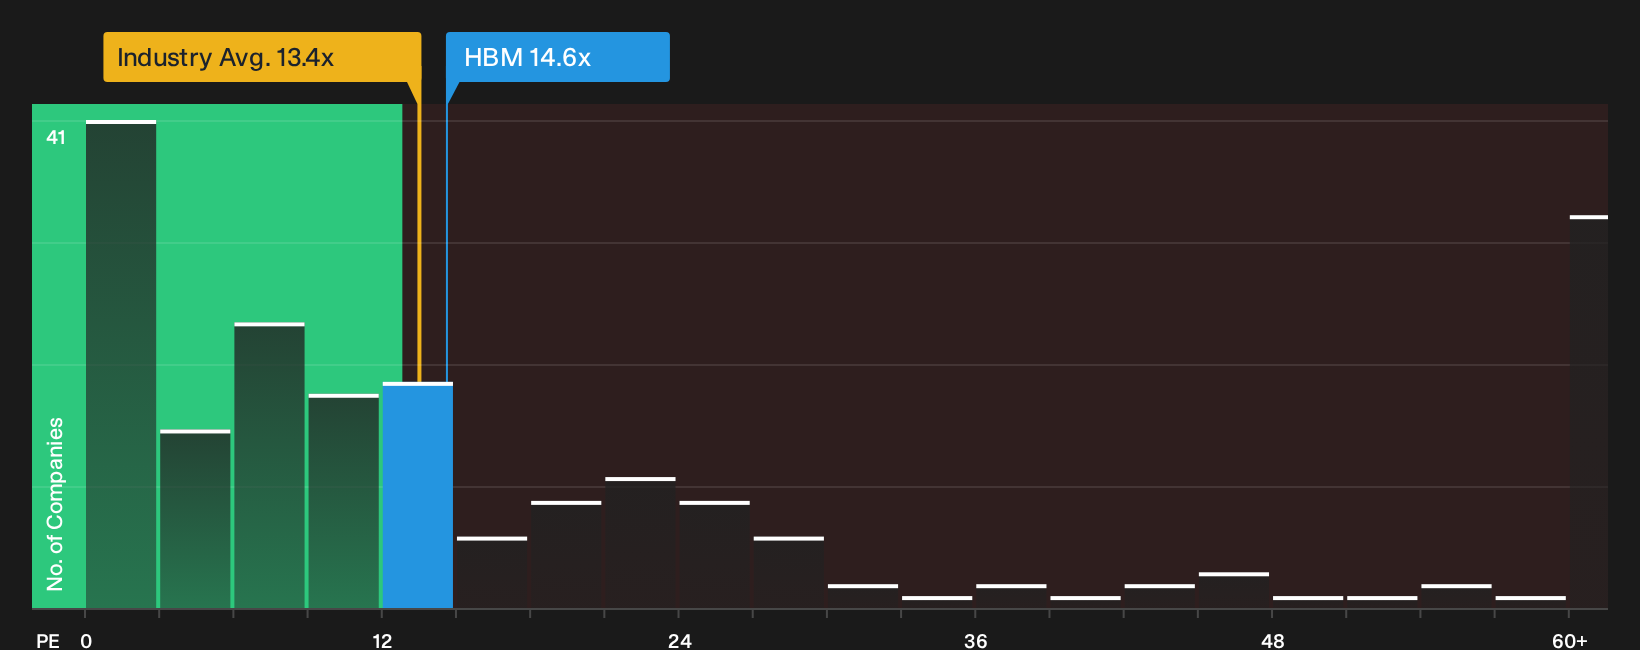
The first fair value anchor at CA$45.35 paints Hudbay Minerals as undervalued, yet the earnings multiple sends a more cautious message. The current P/E of 14.6x sits above the Canadian metals and mining group on 13.4x, even though it only nudges below the fair ratio of 15.1x.
That combination means the stock trades cheaper than its peer average but slightly rich against its own fair ratio, so the upside case is not risk free. The key question for you is whether Copper World and the wider copper and gold plan justify paying ahead of the sector today.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Hudbay Minerals often create the most interesting setups, so move quickly, stress test the numbers yourself, and then weigh the 4 key rewards and 1 important warning sign.
Looking for more Hudbay Minerals sized ideas?
Do not stop with Hudbay Minerals. Fresh opportunities are always emerging, and the Simply Wall Street Screener can help you quickly surface stocks that fit your style.
- Target resilient balance sheets and steadier financial profiles by running a pass through the list of solid balance sheet and fundamentals (6 results).
- Hunt for mispriced opportunities by filtering for strong fundamentals paired with appealing valuations using the 5 high quality undervalued stocks.
- Spot lesser known prospects with quality metrics on their side by scanning the 8 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com