


EN
Does Copper Guidance Cut Change The Bull Case For First Quantum Minerals Stock (TSX:FM)?
- First Quantum Minerals reported third quarter 2026 sales of US$2,086 million and net income of US$207 million, with higher copper, gold and nickel production compared with the same period a year earlier, and updated 2026 guidance that trims copper and gold ranges while lifting nickel expectations.
- The mix of stronger recent output and earnings, reduced copper production guidance, and unresolved Cobre Panamá uncertainty highlights how operational execution, asset availability and commodity exposure are pulling the business in different directions at the same time.
- The focus now shifts to how First Quantum Minerals' improved quarterly results, alongside lower copper guidance, may influence the longer term investment narrative.
Scan how other copper exposed producers are positioned by reviewing the 16 top copper producer stocks, which highlights miners where production profiles and guidance shifts are front and center for investors.
First Quantum Minerals Investment Narrative Recap
Owning First Quantum Minerals relies on a view that its large scale copper and nickel operations can run reliably while issues around Cobre Panamá are resolved over time. The third quarter swing to US$207 million in net income and stronger output supports confidence in current operations, yet it does not remove project or jurisdiction risk.
The most important near term catalyst remains clarity on Cobre Panamá, alongside consistent execution at Kansanshi, Sentinel and Enterprise. The trimmed copper and gold guidance, paired with higher nickel expectations, slightly reshapes the production mix but does not radically change that core near term focus or the principal risk.
The revision to 2026 production guidance is the announcement that matters most for this earnings release. First Quantum Minerals now expects 405,000 tonnes to 435,000 tonnes of copper and 150,000 ounces to 170,000 ounces of gold, both slightly tighter, while nickel guidance has been lifted to 40,000 tonnes to 45,000 tonnes.
This adjustment keeps copper volumes more constrained while leaning into higher nickel output, which places more emphasis on how well Enterprise and related assets run. For you as a shareholder or potential investor, the key question is whether this shift supports more dependable cash generation while the Cobre Panamá outcome and balance sheet pressures remain unresolved.
First Quantum Minerals' narrative projects US$12.1b revenue and US$2.5b earnings by 2029. This represents 23.0% yearly revenue growth and an earnings increase of about US$2.3b from US$172.0m today.
Uncover how First Quantum Minerals' fair value indicates a 53% potential upside to its current price that could narrow quickly if sentiment shifts in favor of First Quantum Minerals.
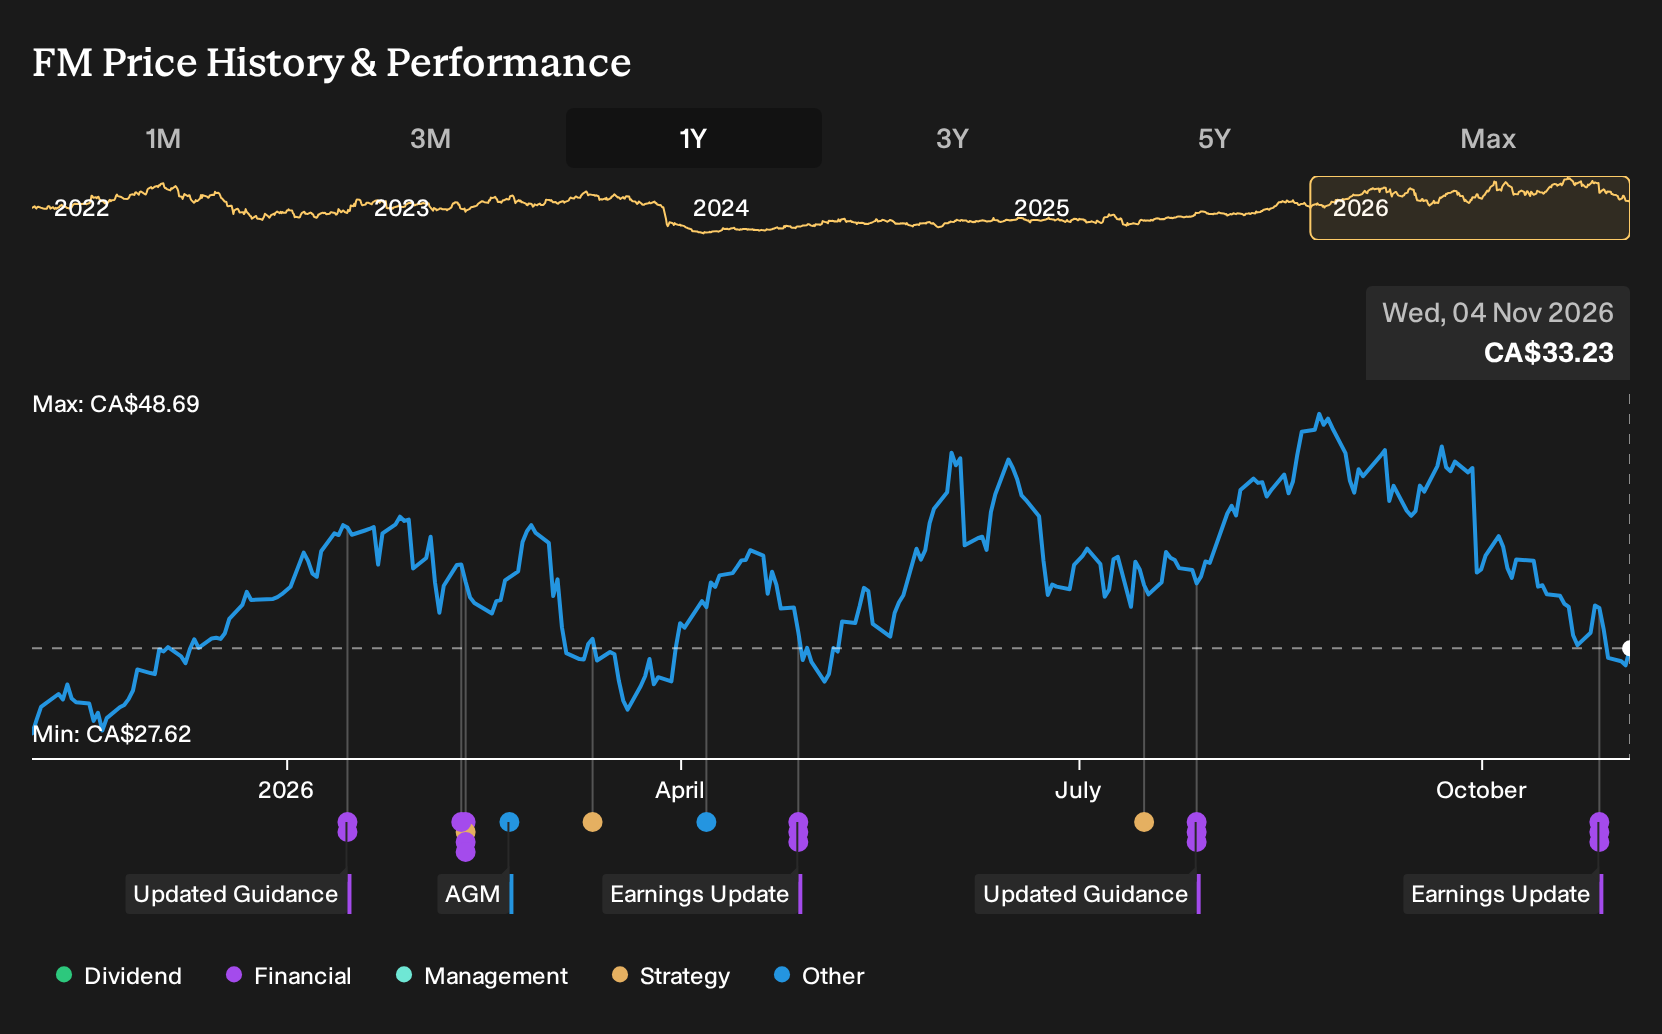
Exploring Other Perspectives
For First Quantum Minerals, the alternate narrative leans heavily on Cobre Panamá risk. The most cautious analysts were assuming revenue of about US$9.7b and earnings of roughly US$2.6b by 2029, with a lower 12.7x P/E. That paints a far more restrained story, which the latest guidance and results could still reshape.
Explore 3 other First Quantum Minerals fair value estimates, including one that suggests it could be worth just CA$50.81!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your First Quantum Minerals research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for First Quantum Minerals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate First Quantum Minerals' overall financial health at a glance.
Looking For More Investment Ideas Beyond First Quantum Minerals?
If the First Quantum Minerals story has sharpened your thinking about risk, balance sheets and future cash generation, it can be useful to line it up against other opportunities that share some of those qualities or differ in important ways.
- If you want income to play a bigger role in your portfolio, consider scanning a curated set of higher yielding payers through the 3 dividend fortresses.
- If capital protection and steadier financial profiles matter most to you right now, compare First Quantum Minerals with companies screened in the 9 resilient stocks with low risk scores.
- If you are hunting for less crowded opportunities with solid fundamentals, broaden your watchlist using the 8 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com