


EN
Is Barrick Mining (TSX:ABX) Cheap Following Golds Post Election Rally?
Gold’s jump after the Democratic Party secured both chambers of the US Congress quickly fed into miners, with Barrick Mining (TSX:ABX) climbing more than 5% in premarket trading as the weaker US dollar supported bullion.
That surge comes after a softer patch for Barrick Mining, with the 30 day share price return slipping 1.74% and the 90 day share price return down 3.46%. Even so, the latest move lifts the CA$56.07 share price and builds on a 1 year total shareholder return of 23.77% and a very large 3 year total shareholder return of 186.03%, suggesting momentum that investors are again willing to pay for when gold sentiment improves.
Scan beyond Barrick Mining and see how other producers are reacting to the same gold tailwind by reviewing the 34 elite gold producer stocks shaping this move.
The latest jump leaves Barrick Mining trading at a discount to analyst targets, yet at a premium to some intrinsic estimates. Is the market simply being cautious, or is it underpricing what this miner already delivers today?
Most Popular Narrative: 14% Undervalued
Barrick Mining’s most followed thesis pins fair value at CA$65.43, above the CA$56.07 last close. This puts the latest rally into clearer context and frames today’s move as part of a longer valuation gap story rather than a simple gold price trade.
The current numbers and market pricing suggest that Barrick Mining’s share price may not fully reflect the cash generation from its existing Tier 1 assets, the planned North American gold IPO and the embedded growth options in its copper and gold project pipeline.
The planned IPO of North American gold assets and continued dividends and buybacks are now treated as key capital allocation levers that influence equity value recognition and balance sheet flexibility.
See why 123 investors see Barrick Mining as 14% undervalued.
Result: Fair Value of CA$65.43 (UNDERVALUED)
Still, if political setbacks at assets like Loulo Gounkoto or rising fuel and project costs bite harder than expected, the Barrick Mining re rating story could stall.
Find out about the key risks to this Barrick Mining narrative.
Another View On Barrick Mining’s Valuation
Analyst targets frame Barrick Mining as undervalued, yet the SWS DCF model tells a different story. On that cash flow view, the current CA$56.07 price sits above an intrinsic estimate of CA$49.32, which flags a potential premium rather than a discount. Which lens do you trust more when real money is on the line?
To unpack how that cash flow estimate is built, and what would need to change for it to move closer to the market price, take a closer look at the Look into how the SWS DCF model arrives at its fair value.
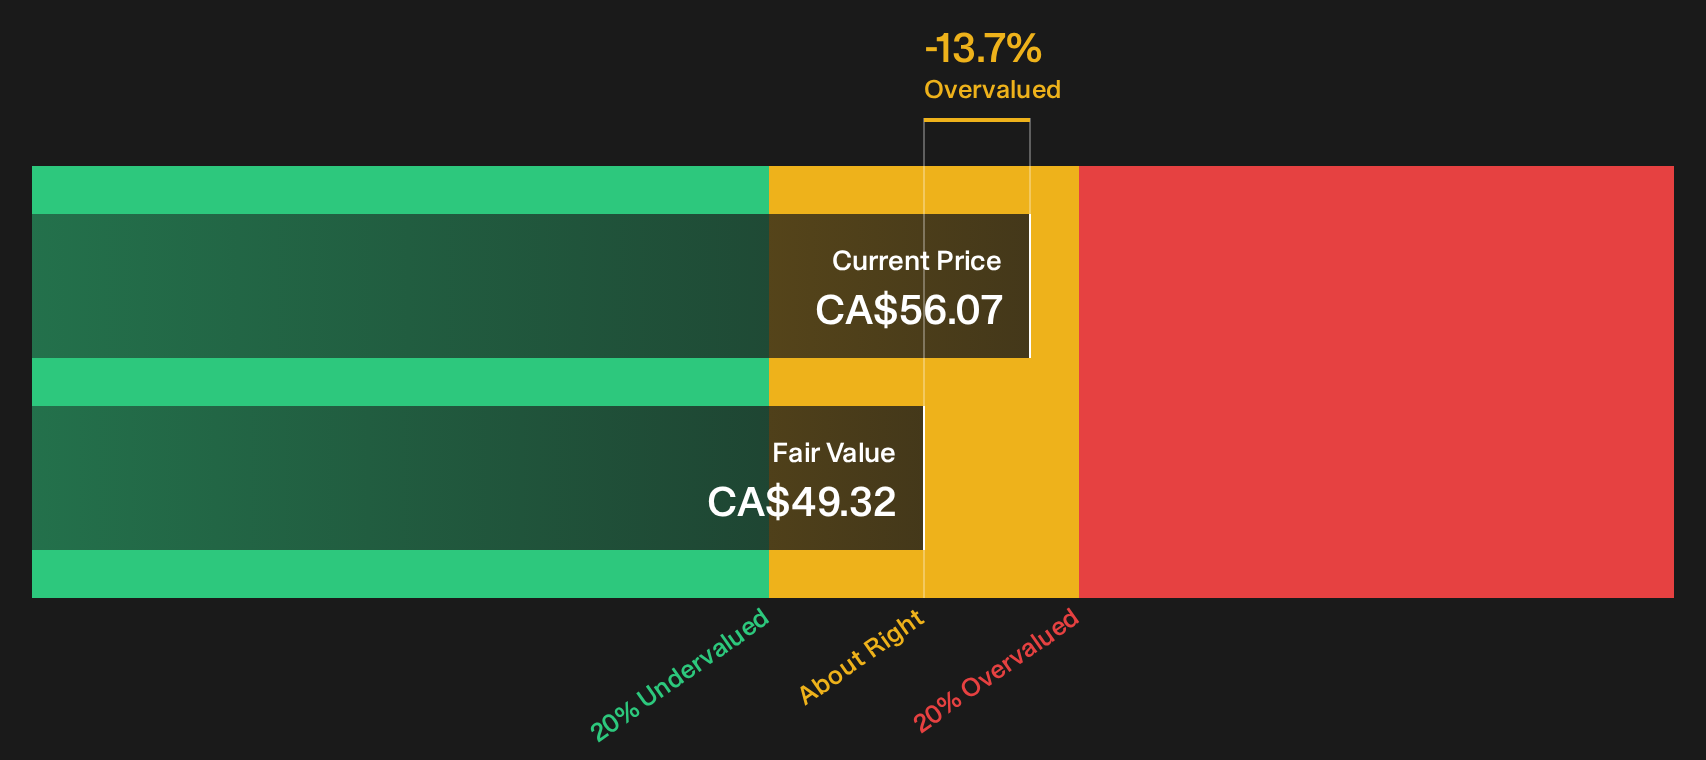
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Barrick Mining for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 5 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages in the data, or a clear tilt in one direction? Act while the market is still debating and weigh both sides for yourself with the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Barrick Mining?
Do not stop with one gold producer. Broaden your watchlist now using focused screeners that surface different types of opportunities other investors may overlook.
- Spot potential turnarounds early and size up smaller opportunities with the 19 elite penny stocks with strong financials that already clear higher financial quality hurdles.
- Hunt for mispriced quality by scanning the 5 high quality undervalued stocks that combine solid fundamentals with prices that sit below many investors’ expectations.
- Strengthen your income playbook and focus on durability by reviewing the 3 dividend fortresses that pair higher yields with resilient profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com