


EN
Galaxy Digital (GLXY) Stock May Be Undervalued Despite Data Center Expansion
Galaxy Digital has seen its share price swing sharply over the past few years, which puts extra focus on a simple question for anyone looking at the stock today. Is the current valuation that the market places on Galaxy Digital justified by the revenue the business generates?
- Over the past 3 years the share price has risen 154.1%, which puts a lot of weight on whether the underlying sales base can support that move.
- Recent profits from the company’s own digital asset holdings and the build out of large scale data center leasing, including Helios projects and related financing, may support different expectations for how quickly Galaxy Digital can turn sales into cash over time.
- Your read on Galaxy Digital is one view; the desks covering it have another. See what analysts think Galaxy Digital's shares could be worth.
The issue now is whether the stock price around US$13.98 makes sense when you line it up against Galaxy Digital’s current and potential future sales.
If you are comparing Galaxy Digital with other AI and data center related plays, it can help to start with a focused stock screen built around 53 AI infrastructure stocks.
Is Galaxy Digital Still Cheap on Sales?
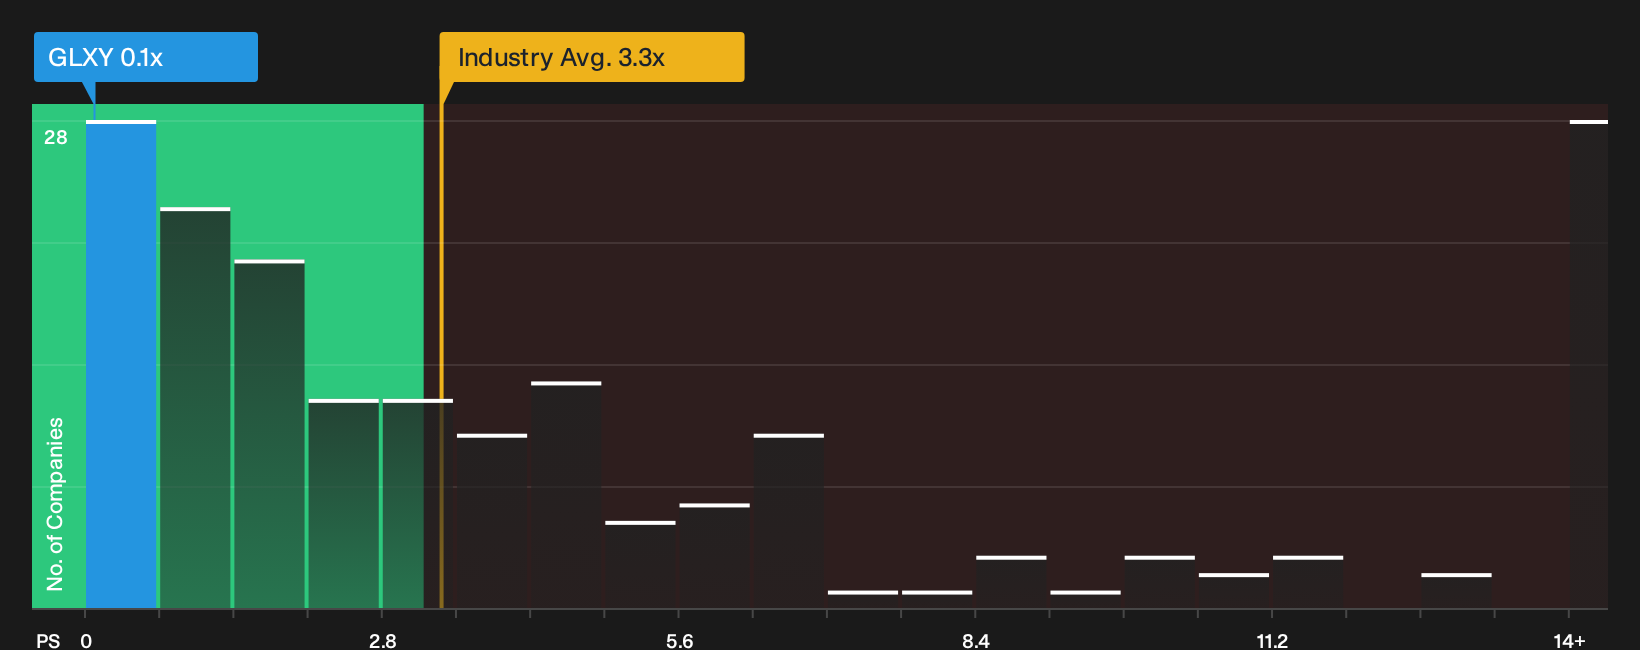
P/S works reasonably well for Galaxy Digital because investors often focus on revenue when profits and free cash flow move around a lot. On this measure, the stock trades on a P/S ratio of 0.1x, which sits far below the Capital Markets industry average of 3.3x and the peer group level of 5.2x. For a reader, that gap means the market is paying a much lower price for each dollar of Galaxy Digital’s sales than for many comparable financial and data center related platforms.
The fair multiple implied by Galaxy Digital’s own profile, including its margins, scale and risk factors, is higher than the current P/S. Because the P/S today comes in below that tailored benchmark, the shares screen as undervalued on this framework. Because the business has reported a Q3 2026 profit and is expanding its data center leases, yet still trades on such a compressed sales multiple, the current price leaves a wide range of expectations about how those revenues might be treated over time. Explore the numbers behind Galaxy Digital's P/S valuation.
The Galaxy Digital Narrative: What Would Justify Today's Price?
Narratives for Galaxy Digital pick up where this valuation puzzle leaves off and explain which combinations of growth, margins and earnings paths would need to hold for the shares to be worth materially more or materially less than today’s price, all housed on Simply Wall St’s Community page. Each one treats fair value as a specific, trackable thesis about Galaxy Digital's business so you can watch how that view holds up over time.
One of the top community narratives on Galaxy Digital: 42% undervalued
Bearish analysts expect Galaxy Digital to remain heavily exposed to a single Helios tenant with high leverage and financing costs...
Discover why this Narrative puts Galaxy Digital at 42% undervalued.
Before making a call on Galaxy Digital, there is one more angle to weigh
Galaxy Digital’s current share price tells one story, while the longer range projections that analysts have mapped out for the business tell another, and lining those up can change how you read today’s numbers. Explore where analysts expect Galaxy Digital to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com