


EN
Winpak (TSX:WPK) Posted Higher Sales, Is The Stock Still Cheap?
Winpak (TSX:WPK) just released third quarter and nine month results that combined higher sales with slightly softer net income, a mix that tends to pull investor attention toward earnings quality.
At a share price of CA$45.56, Winpak has seen short term momentum pick up, with a 30 day share price return of 5.76% and a 90 day gain of 6.30%. The 1 year total shareholder return of 8.89% and 5 year total shareholder return of 26.67% point to steadier compounding in the background as investors weigh the latest mix of higher sales and softer net income.
Scan how Winpak’s mix of firmer sales and softer earnings compares with packaging peers by reviewing the curated list of solid balance sheet and fundamentals (6 results) in the same corner of the market.
The share price has moved up while Winpak still trades below analyst targets and a much higher intrinsic estimate. Is that a sensible margin of safety, or a sign the market sees real risks?
Most Popular Narrative: 6% Undervalued
Against the last close of CA$45.56, the most followed narrative anchors Winpak’s fair value at about CA$48.38, using a 6.44% discount rate and a long term earnings profile that stays broadly steady rather than explosive.
The main thing that has to go right is that Winpak turns its expanded footprint, sold-out in-mold labeling platform, and sustainability-focused product mix into meaningful market share gains in a shrinking end market that is pressured by GLP-1-driven changes in food consumption.
The current valuation, alongside Neutral ratings and modestly higher price targets around the mid CAD 40s, suggests that the share price does not yet fully reflect this narrative that Winpak is undervalued and that its balance sheet and cash generation can support both growth capital expenditures and a sustainable dividend.
See why 1 investors see Winpak as 6% undervalued.
Result: Fair Value of CA$48.38 (UNDERVALUED)
Still, the Winpak narrative can be upset if GLP 1 driven shifts in food consumption keep shrinking packaged volumes, or if heavy capital spending fails to attract enough new orders.
Find out about the key risks to this Winpak narrative.
Another View On Winpak’s Valuation
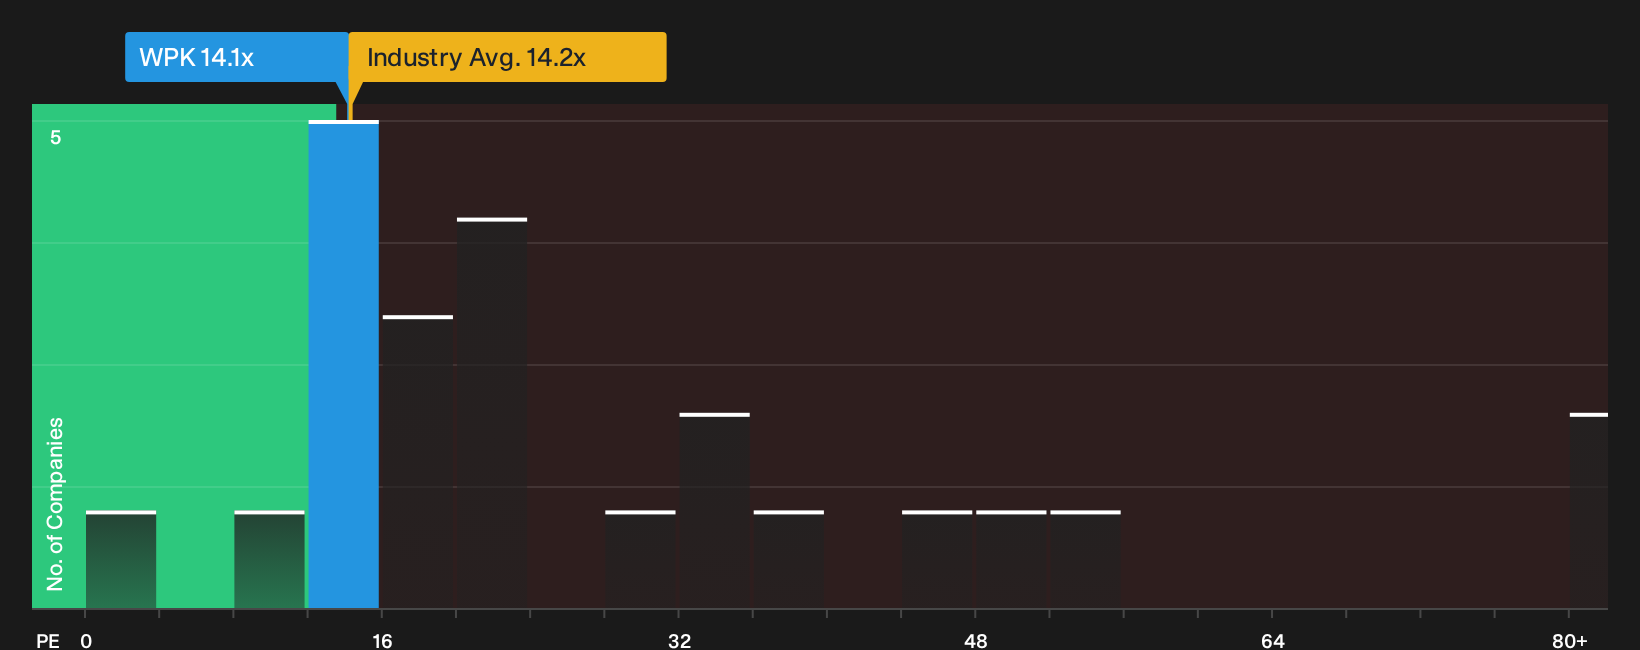
There is a catch. On simple P/E math, Winpak trades at 14.1x earnings versus an estimated fair ratio of 12.6x and a Canadian peer average of 12.4x. That points to a richer tag on every dollar of profit. Is that a premium for quality, or just extra valuation risk?
To pressure test that question against hard numbers and to see how the market could shift toward the fair ratio over time, take a look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If the mix of higher sales, softer earnings and valuation gaps leaves you on the fence, act quickly and review the numbers yourself. To see the potential upside alongside the key risks in one place, take a close look at the 2 key rewards.
Looking For More Ideas Beyond Winpak?
Do not stop with one opportunity. Broader context across sectors and styles can help you stress test your thinking and spot patterns you might otherwise miss.
Use the Simply Wall Street Screener to quickly surface stocks that fit clear, data driven criteria, then compare them against Winpak to sharpen your next move.
- Target potential breakout value by scanning the 5 high quality undervalued stocks that combine quality fundamentals with compressed valuations.
- Lock in income-focused ideas by reviewing the 3 dividend fortresses that put reliable cash returns at the center of the thesis.
- Prioritise capital resilience by filtering for the 9 resilient stocks with low risk scores that score well on financial strength and volatility.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com