


EN
How SAP Tracking Integration At Descartes Systems Group (TSX:DSG) Has Changed Its Investment Story
- Descartes Systems Group reported that its MacroPoint Advanced Ocean Visibility tool is now integrated with SAP Business Network Freight Collaboration and SAP Business Network Global Track and Trace, giving SAP customers container-level tracking and multimodal shipment visibility within existing SAP workflows.
- The integration uses standardized APIs and harmonized data models over the Descartes Global Logistics Network. This positions the platform as embedded infrastructure inside SAP environments for customers that want near real-time event data to support analytics, automation and AI-led supply chain projects.
- We will look at how Descartes Systems Group's investment narrative is affected by deeper SAP integration around real time shipment visibility.
Scan beyond Descartes Systems Group and line up other logistics and supply chain software players with resilient balance sheets using our curated list of solid balance sheet and fundamentals (6 results) as a comparison set.
Descartes Systems Group Investment Narrative Recap
To own Descartes Systems Group, you need to be comfortable with a logistics software story that leans heavily on recurring revenue, acquisitions and increasing complexity in global trade and e commerce. The near term focus is on execution as management heads into the December 2 results call, where investors will look for confirmation that earnings growth near current forecasts remains intact.
The latest SAP integration strengthens the Global Logistics Network product story but does not radically change the immediate risk profile. The bigger swing factor is still exposure to freight volumes and global trade policy, along with the possibility that acquisition heavy expansion or rising competition slows organic service growth.
The SAP Business Network integration is the announcement that lines up most directly with the current visibility narrative. It deepens Descartes Systems Group’s role inside existing transportation and tracking workflows, which matters if you care about customer stickiness, cross sell potential and the durability of subscription and transactional revenue tied to shipment activity.
For catalysts, this kind of embedded container and multimodal tracking can support analytics and AI projects that customers are already prioritizing, which may help usage of the Global Logistics Network if freight conditions cooperate. The operational risk is that higher complexity, regulatory change or weaker shipping volumes limit how much of that opportunity actually turns into billable activity.
Descartes Systems Group’s consensus scenario points to 2029 revenue of $1.0b and earnings of $275.4m, based on analysts’ assumption of 11.3% yearly revenue growth and an earnings increase of about $111.6m from $163.8m today by that 2029 estimate year.
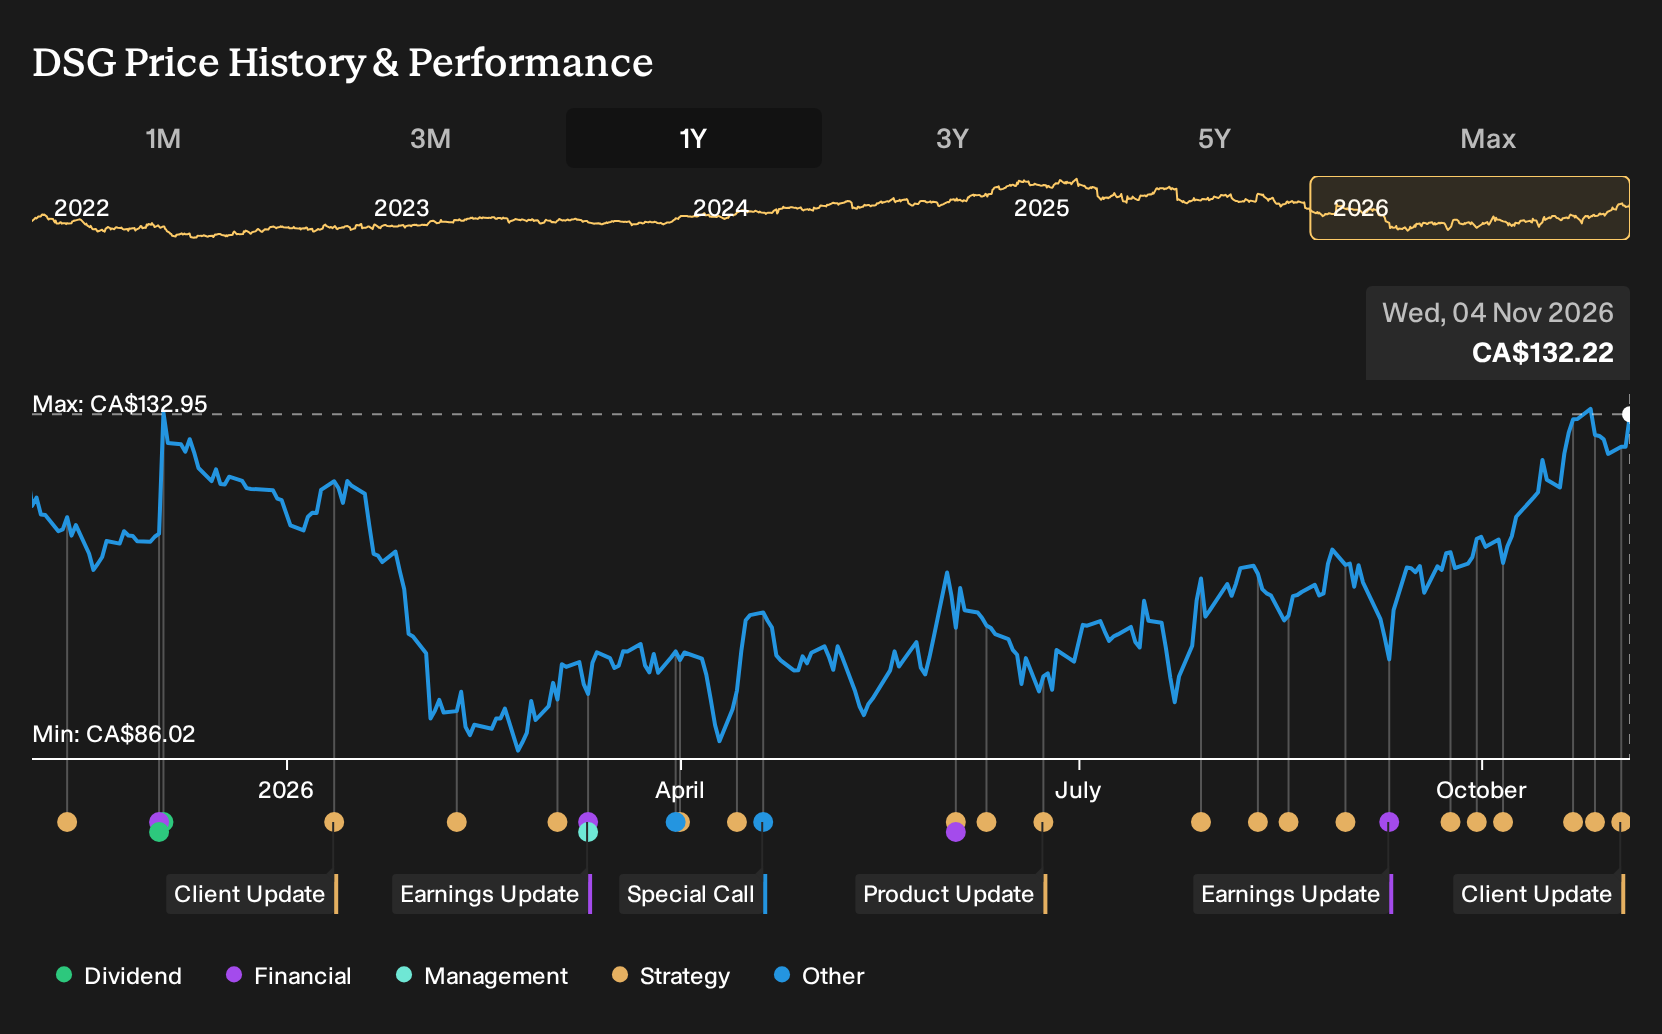
Uncover why Descartes Systems Group's fair value indicates a 3% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between $128.28 and $162.98. This suggests some see Descartes Systems Group as only mildly mispriced, while others allow for a wider upside band. You should weigh those views against risks around trade policy, freight volumes and acquisition execution, and compare several alternative opinions before deciding how Descartes fits your portfolio.
Explore 2 other Descartes Systems Group fair value estimates, including one that suggests as much as 23% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Descartes Systems Group research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Descartes Systems Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Descartes Systems Group's overall financial health at a glance.
Looking for more investment ideas beyond Descartes Systems Group?
If Descartes Systems Group sits on your watchlist, it can help to set it alongside other companies with clear financial profiles so you can judge risk and reward in context. The Simply Wall St Screener gives you that broader field of options, filtered by balance sheet strength, valuation and stability so you can quickly build a shortlist that fits your own approach.
- If capital preservation is front of mind, compare Descartes Systems Group with a group of resilient businesses by screening for 9 resilient stocks with low risk scores that may better match your comfort with volatility.
- If you want income on top of potential capital gains, scan for 3 dividend fortresses that could help support a regular cash return profile in your portfolio.
- If you prefer to hunt earlier in the story, line up 8 high quality undiscovered gems that pair solid fundamentals with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com