


EN
O'Reilly Automotive (ORLY) Shares Just Moved, So What Is Driving Attention Today?
O'Reilly Automotive (ORLY) just delivered third quarter results that showed higher sales, net income, and earnings per share compared with the same period last year, along with updated full year guidance and an accelerated store expansion plan.
The latest earnings and store expansion news has arrived after a choppy stretch for O'Reilly Automotive’s share price, with a 10.1% 1 month share price return contrasting with a slight 3 month pullback and a modest 1 year total shareholder return decline of 2.7%. Over 3 and 5 years, total shareholder returns of 42.3% and 113.8% respectively show that long term investors have still seen substantial value creation, even as near term sentiment has only recently started to improve.
Power up your research by scanning list of solid balance sheet and fundamentals (25 results) that, like O'Reilly Automotive after this earnings update, pair resilient operations with disciplined financial foundations.After a quick 10% rebound yet a flat year for holders, O'Reilly Automotive now sits at a more awkward crossroads. The key question is whether the current valuation still leaves enough potential upside to justify taking on new risk.
Most Popular Narrative: 14.3% Undervalued
Against the latest close of $92.34, the most followed narrative pegs fair value for O'Reilly Automotive at $107.80, which implies a material gap that investors need to explain through execution, margins, and capital allocation.
The main thing that has to go right is that O'Reilly Automotive converts its professional DIFM growth, private label strength, and planned store expansion into sustained market share gains without eroding its 51.5 to 52% gross margin outlook.
See why 24 investors see O'Reilly Automotive as 14% undervalued.
Result: Fair Value of $107.80 (UNDERVALUED)
Still, the proposed US$10b NAPA bid and management’s move toward 2.5x leverage mean O'Reilly Automotive’s story could change quickly if integration or funding options disappoint.
Find out about the key risks to this O'Reilly Automotive narrative.
Another View: O'Reilly Automotive Looks Expensive On Earnings
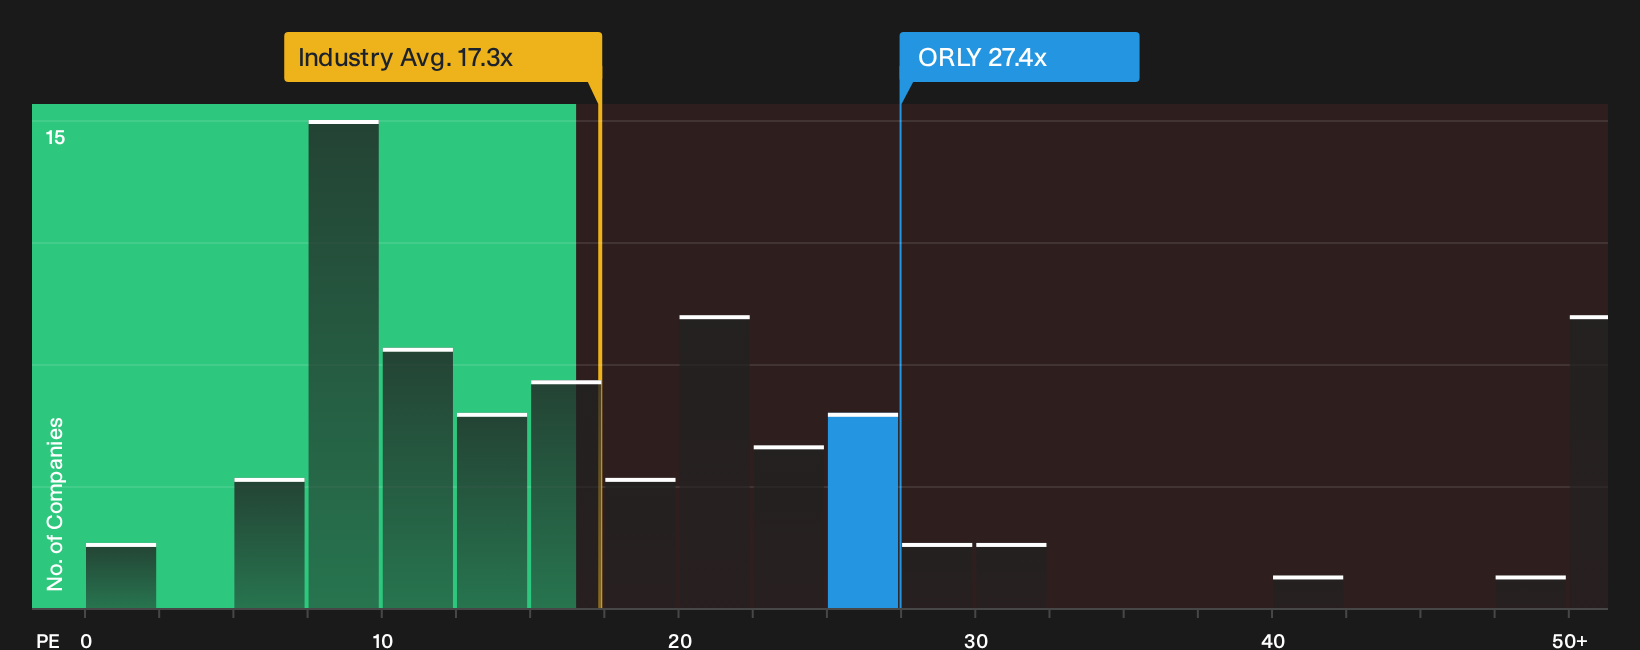
The first story presents O'Reilly Automotive as around 14.3% undervalued on a fair value of $107.80. A simple earnings multiple suggests a tougher story. The stock trades on a P/E of 27.4x, while the fair ratio sits at 20.2x. That gap points to valuation risk if expectations cool.
The P/E comparison is also not flattering next to peers. O'Reilly Automotive trades at 27.4x earnings, compared with 17.3x for the US Specialty Retail industry and 20.7x for similar companies. Paying a clear premium like that might only feel comfortable for investors who have strong conviction in the long term narrative.
Investors therefore face a clear fork in the road. The richer P/E could be treated as a warning sign, or as the price of owning a business with high quality earnings and strong execution so far, even after a softer one year share price return.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views like these only matter if you check the figures yourself and decide where you stand. To see how optimism and concern balance out, look through the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond O'Reilly Automotive?
If O'Reilly Automotive has sharpened your focus on quality, broaden your watchlist now so you do not miss other opportunities quietly lining up.
- Target dependable compounding by reviewing income opportunities in the 5 dividend fortresses that can support a portfolio focused on regular cash flows.
- Hunt for mispriced quality and scan the 19 high quality undiscovered gems before attention and fresh buyers potentially re-rate those businesses.
- Dial down portfolio stress and filter through the 31 resilient stocks with low risk scores built to spotlight companies with more resilient profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com