


EN
How Investors Are Reacting To CN (TSX:CNR) Strong Quarterly Earnings
- Canadian National Railway reported third quarter 2026 sales of C$4,771 million and net income of C$1,209 million, alongside a C$0.9150 quarterly dividend and active share repurchases under its 2026 buyback.
- The planned transition of long serving CFO Ghislain Houle to retire in early 2027, with internal successor Jamie Lockwood stepping in, points to an emphasis on continuity in financial stewardship, while capital returns continue through dividends and repurchases.
- We will now look at how Canadian National Railway's recent earnings strength could reshape the investment narrative investors have been using.
Scan how Canadian National Railway's earnings, dividends and buybacks compare with other rail and infrastructure focused businesses by jumping into our hand picked list of solid balance sheet and fundamentals (6 results).
Canadian National Railway Investment Narrative Recap
To own Canadian National Railway, an investor needs to be comfortable with a freight story that leans on Western Canadian export volumes, cross border corridors and ongoing efficiency work through programs like Fast Track. The latest quarter shows higher sales and earnings per share alongside slightly lower net margins over the past year, so the near term focus stays on cost control and mix. The key short term catalyst remains execution on grain, energy and Mexico related lanes, while the biggest operational risk is demand softness in lumber, overseas intermodal and other industrial freight that leaves parts of the portfolio underused.
The recent earnings release does not fundamentally change that thesis. Revenue and profit are higher over both the quarter and nine month period, which supports the idea that capacity investments and productivity work are feeding through, even if some segments remain uneven. For now, the update looks more like confirmation of the existing narrative than a new inflection point, with the main risk still that weaker industrial end markets and tariffs on key commodities limit how much operating leverage Canadian National Railway can pull from the network.
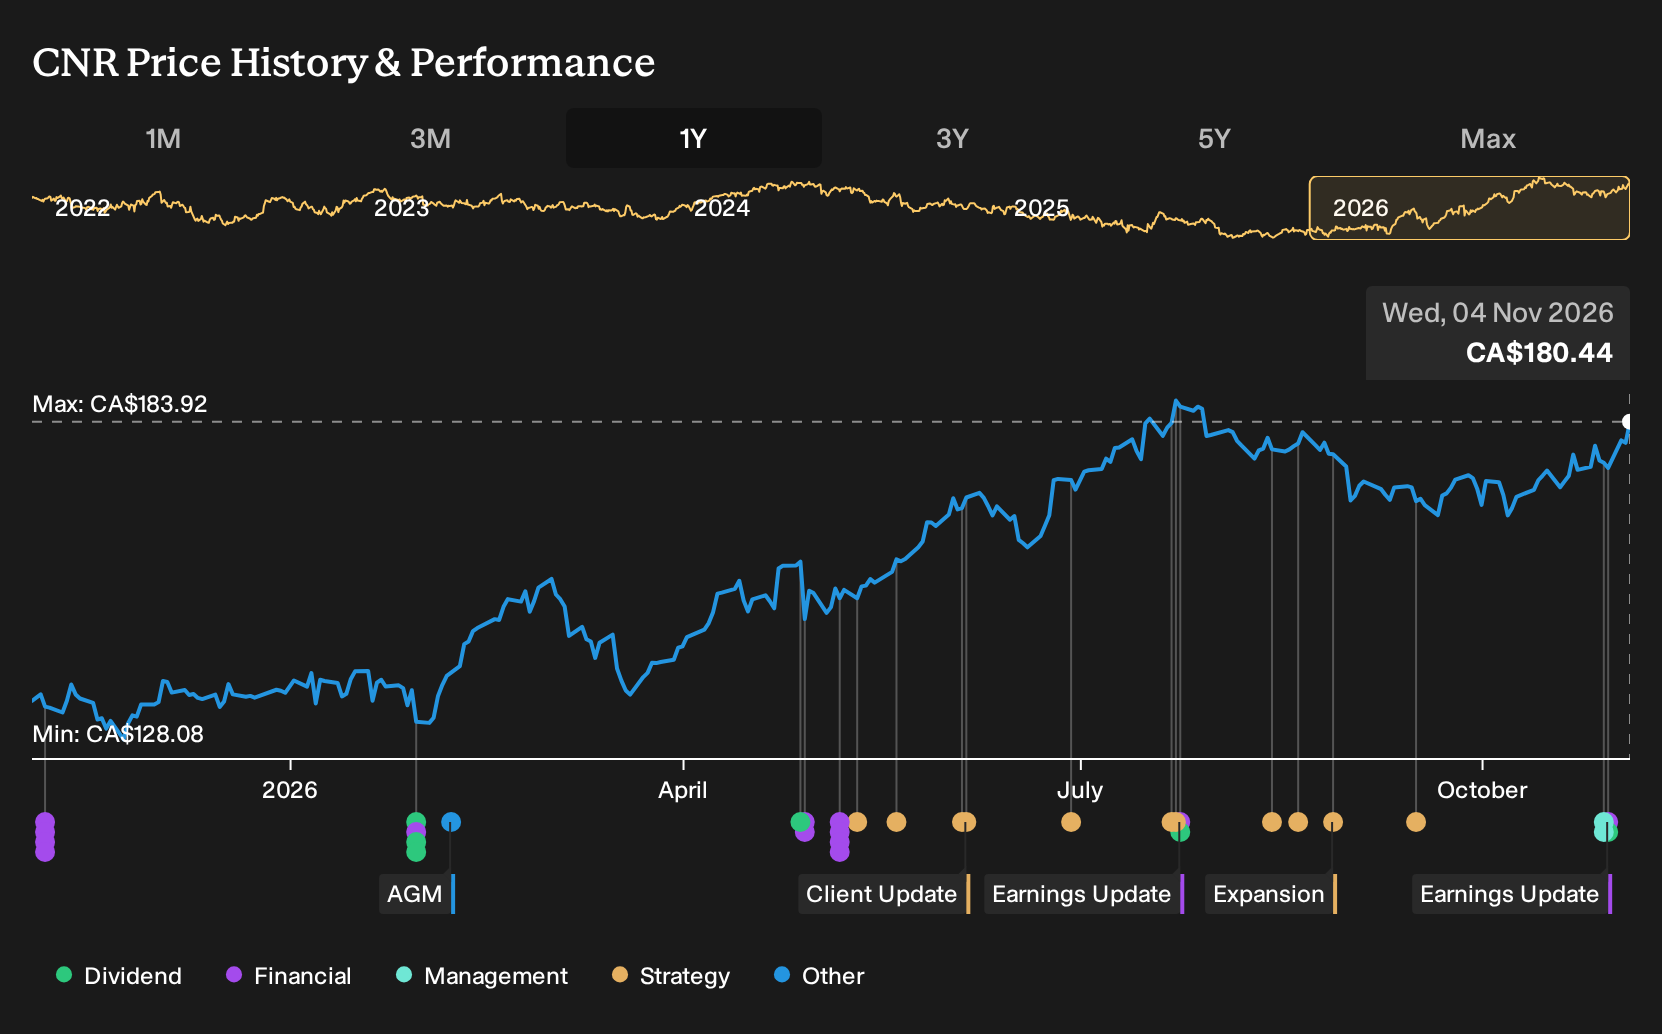
The dividend affirmation for the fourth quarter of 2026 is the most relevant piece of news alongside the earnings print. A C$0.9150 per share payment scheduled for December fits with Canadian National Railway’s long running pattern of returning cash through regular distributions. For a shareholder, that payout is part of the total return equation, especially with the stock already showing strong 1 year and year to date performance. The announcement also arrives in the context of a P/E that sits below the wider transportation industry and a dividend profile described as reliable.
Viewed next to the catalyst list, the maintained dividend and ongoing buybacks reported for 2026 indicate that management is pairing heavy network investment with consistent capital returns. That matters if you are watching for free cash flow progress as Western Canada capex normalizes to the 15% to 17% of revenue range over time and tax benefits from the productivity mega deduction start to show up after 2027. The main execution watchpoint stays the same. Grain, energy and new Canada to Mexico traffic need to carry more of the earnings load if lumber and overseas intermodal volumes continue to lag.
Canadian National Railway is underpinned by analyst assumptions that revenues reach CA$20.9b and earnings reach CA$5.8b by 2029. These projections are based on forecast yearly revenue growth of 5.5% and an earnings increase of about CA$1.0b from current earnings of CA$4.8b.
Uncover why Canadian National Railway's fair value indicates a 5% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between C$155.20 and C$191.16, so retail opinions on Canadian National Railway already span a wide band before the latest earnings, dividend affirmation and buyback data. Use that spread, along with the mix of volume risks and Mexico growth catalysts, to test your own view.
Explore 2 other Canadian National Railway fair value estimates, including one that suggests as much as 6% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Canadian National Railway research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Canadian National Railway. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Canadian National Railway's overall financial health at a glance.
Looking for more investment ideas beyond Canadian National Railway?
If you want to round out your watchlist around Canadian National Railway with other opportunities, the Simply Wall St Screener can help you quickly surface stocks that match different goals, from value potential through to income and balance sheet strength.
- For investors who want potential value combined with quality fundamentals, scan a curated set of opportunities through the 9 high quality undiscovered gems.
- If capital preservation and steadier profiles matter most to you, narrow the field to sturdier candidates using the 9 resilient stocks with low risk scores.
- When cash generation and resilience are at the top of your checklist, broaden your research beyond Canadian National Railway with a targeted 3 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com