


EN
FirstService (TSX:FSV) Could Be 10% Below Fair Value As New Contract Wins Land
FirstService (TSX:FSV) just picked up a fresh property management mandate at The Highlands Community Association in Pennsylvania, alongside a new risk-focused partnership for water leak detection, giving investors fresh context for the stock’s recent move.
The fresh mandate at The Highlands and the water risk partnership land at a moment when FirstService’s share price has been picking up speed. A 1-month share price return of 18.66% and a 7-day gain of 11.53% have contributed to a 90-day rise of 8.39% from a CA$216.76 close, although the 1-year total shareholder return is broadly flat and the 5-year total shareholder return has declined 6.39%, pointing to short term momentum against a more subdued longer term record.
Spot emerging momentum stories like FirstService and broaden your watchlist with our hand picked 5 high quality undervalued stocks.The recent jump in FirstService shares has narrowed the gap to both analyst targets and intrinsic value estimates, yet a discount still shows up on the screens. How much room does that really leave at today’s CA$216.76 price?
Most Popular Narrative: 9% Undervalued
On Simply Wall St, the most followed narrative puts FirstService’s fair value at CA$238.65, above the recent CA$216.76 close. This frames the latest rally as closing rather than erasing the perceived discount.
The main factor that has to go right is that management continues to execute on capital deployment, including M&A and buybacks, while stabilising weaker roofing and home services operations without eroding the stronger restoration and Century Fire businesses.
The current valuation and active share repurchases indicate that the market is pricing FirstService as if roofing and home services softness will weigh on the share price more than management and several covering firms suggest.
See why 12 investors see FirstService as 9% undervalued.
On that view, the current setup hinges on two moving parts: capital allocation and business mix. Cash generation and the balance sheet give management room to keep buying back shares and funding tuck under deals in areas like fire protection and restoration while weaker roofing and home services units are worked through.
At the same time, the thesis on FirstService leans heavily on those large loss restoration wins and specialty construction work discussed in the narrative. If those contracts are converted efficiently through the existing cost base, the margin lift that analysts have built into their models becomes easier to understand, especially with earnings already growing 6.2% over the past year and 4.4% per year over five years.
Forecast numbers in that storyline remain reasonably punchy. Earnings are expected to grow 15.7% per year, faster than the 11% per year projection for the wider Canadian market, while revenue is projected to rise 5.4% per year, ahead of the 4.2% market forecast but not at high growth levels. A discount rate of 7.97% is used to pull those future cash flows and earnings back into today’s value. This is where the CA$238.65 fair value anchor comes from.
There are trade offs baked into that conclusion. FirstService is assessed as trading 10.1% below an intrinsic value estimate and 10.1% below Simply Wall St’s future cash flow value of CA$240.98, yet the same dataset flags the stock as expensive on P/E compared with both the broader North American real estate group and an estimated fair P/E of 41.3x. The narrative effectively argues that the earnings and cash flow profile, along with high quality earnings, justify paying more than sector averages.
Risks temper the story. The narrative itself points to softer roofing demand, flat home services, and weather dependent restoration work that can leave backlogs weaker year over year. On top of that, the company carries a high level of debt, uses only higher risk funding sources, and has a low current Return on Equity of 13.5%, even if that measure is expected to reach 21.9% in three years.
Investors weighing the recent price spike against that fair value anchor are essentially deciding how much confidence to place in management’s ability to execute buybacks and acquisitions while holding margins in the slower units. The narrative suggests the market has focused more on near term weakness in roofing and home services than on the potential contribution from large loss restoration and Century Fire. This is why a discount still shows up at CA$216.76.
Result: Fair Value of CA$238.65 (UNDERVALUED)
Still, two pressure points could flip that script fast: roofing weakness and weather sensitive restoration volumes are both capable of undercutting the current FirstService narrative.
Find out about the key risks to this FirstService narrative.
Another View: FirstService Through The P/E Lens
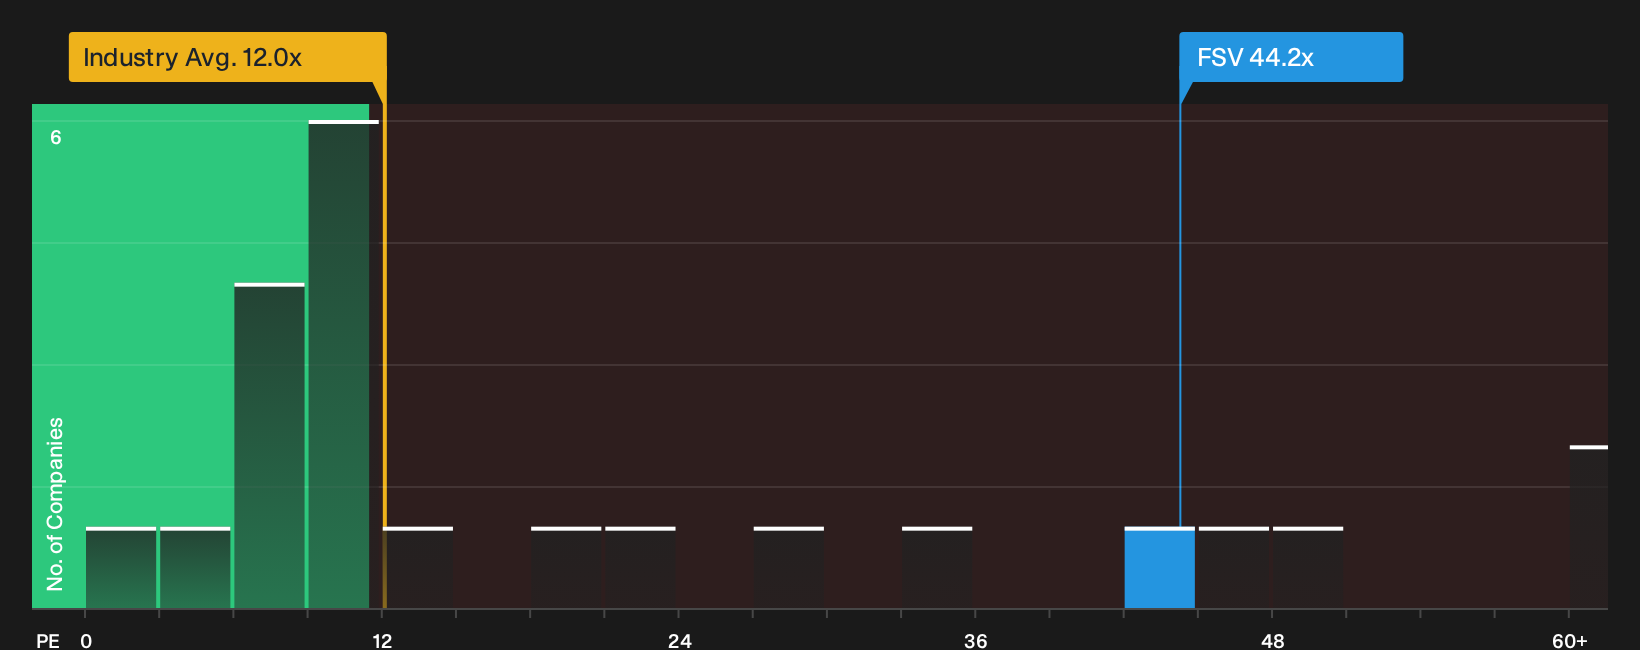
DCF work suggests FirstService has some headroom at around CA$216.76, yet the P/E picture is far less relaxed. The stock trades on 44.2x earnings versus a peer average of 20.2x and a fair ratio of 41.3x, which points to richer pricing and less margin for error if growth disappoints.
That kind of premium multiple rests on the idea that quality, growth and buybacks justify paying more than both sector and fair ratio levels. The question for anyone watching FirstService now is simple: Does the recent share price jump leave enough upside to compensate for that valuation stretch, or does it start to cap the payoff from here?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on FirstService so far. If you want to move quickly and decide where you stand, start by weighing the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond FirstService?
- Spot potential bargains early by scanning a curated 9 high quality undiscovered gems that focuses on strong fundamentals before broader attention arrives.
- Reduce portfolio stress by reviewing a 9 resilient stocks with low risk scores that concentrates on resilient businesses with sturdier financial profiles.
- Sharpen your opportunity set by filtering a 19 elite penny stocks with strong financials designed to highlight smaller companies with stronger financials than typical microcap picks.
Do not stop at FirstService alone. Widening your research with high quality screeners today can help you identify ideas you may wish you had found earlier.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com