


EN
American Assets Trust (AAT) Just Gave Investors Something To Think About
American Assets Trust (AAT) is back in focus after releasing third quarter 2026 results and affirming its regular cash dividend, giving investors fresh information on both recent performance and ongoing income.
At a share price of $22.09, American Assets Trust has seen short term momentum pick up, with a 1 month share price return of 3.47% and a year to date share price gain of 17.63%, while the 5 year total shareholder return decline of 25.52% shows the longer term record has been more mixed.
Scan how American Assets Trust compares with other income focused real estate plays by reviewing our hand picked 5 dividend fortresses in the same segment.
American Assets Trust now trades at a discount both to one estimate of fair value and to the average analyst target after a strong recent run. Is that gap a genuine opportunity, or a warning that the market’s caution is justified?
Most Popular Narrative: 6% Undervalued
On the most followed view, American Assets Trust carries a fair value of $23.50 against a last close of $22.09, with that gap tied closely to how much of the identified leasing pipeline turns into durable cash flow.
Embedded earnings growth from leasing up La Jolla Commons Tower 3, One Beach Street and suburban Bellevue, with management quantifying about $0.29 per share of potential incremental FFO and about half tied to already signed leases that are scheduled to commence through 2027, could support higher future earnings and dividend coverage as this rent flows through the income statement.
See why 2 investors see American Assets Trust as 6% undervalued.
Result: Fair Value of $23.50 (UNDERVALUED)
Still, the narrative around American Assets Trust can change quickly if leasing momentum stalls, or if elevated net debt and a high payout ratio start to bite.
Find out about the key risks to this American Assets Trust narrative.
Another View: What The P/E Ratio Signals For American Assets Trust
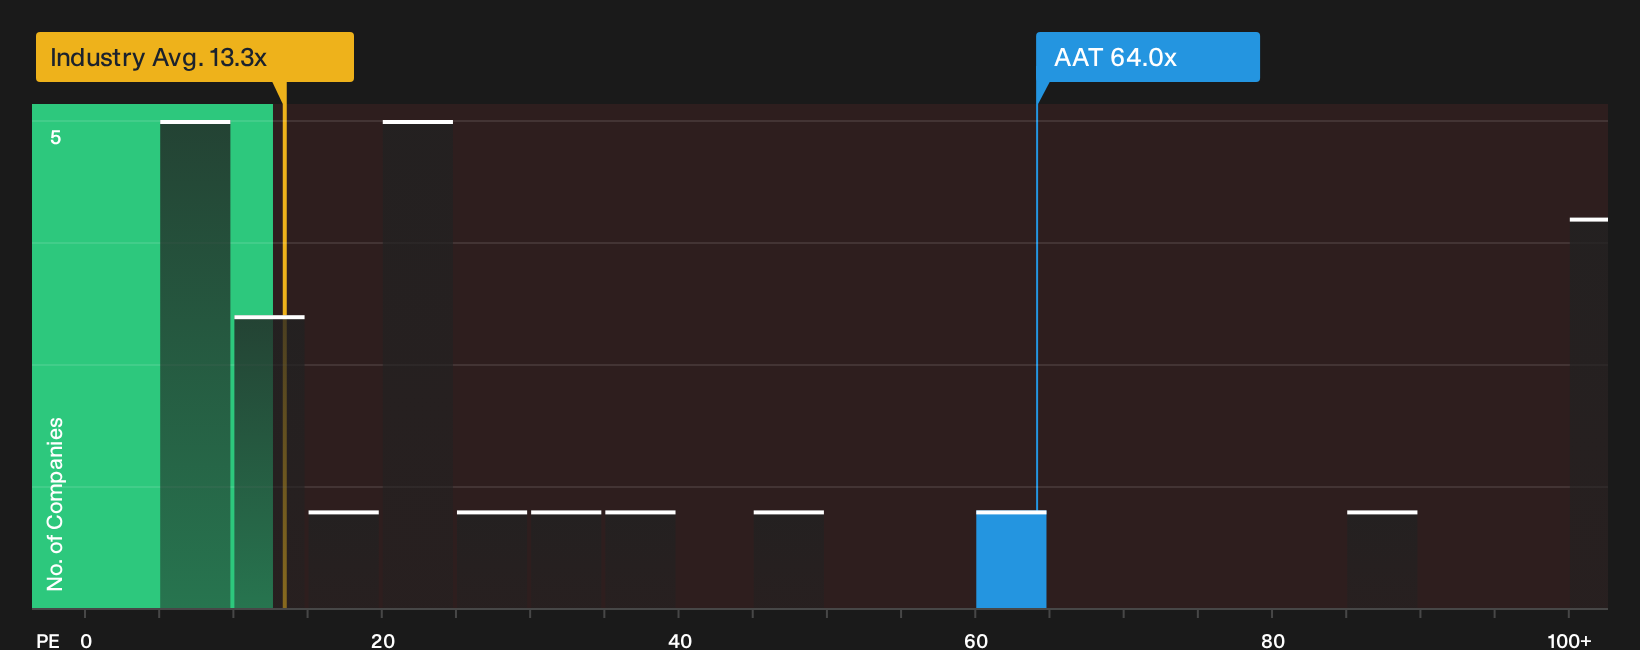
The earlier fair value work points to American Assets Trust trading below an estimate of its future cash flow value. Purely on the P/E ratio, the picture is less forgiving. AAT changes hands at about 64x earnings, compared with roughly 13.3x for the global REITs industry and a fair ratio of 36.6x based on Simply Wall St’s model.
That premium also runs slightly ahead of peers on average at 65.9x. This places the stock in a tightly priced group where small disappointments can matter. If the market leans back toward that 36.6x fair ratio over time, does current pricing still feel like enough cushion, or is the risk of multiple compression too easy to overlook?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Skeptical about whether the mixed sentiment around American Assets Trust lines up with your own read of the numbers and the story? Weigh both the concerns and the potential upside by reviewing the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond American Assets Trust?
If American Assets Trust has you thinking more broadly about where to put fresh capital, do not stop here. Use focused screeners to uncover ideas that match your goals before the next window of opportunity tightens.
- Target durable income streams by reviewing a curated 5 dividend fortresses that prioritize payout strength and consistency.
- Hunt for potential mispricings with the 19 high quality undiscovered gems list that highlights quality businesses the market may be overlooking.
- Prioritise resilience and capital preservation through the 32 resilient stocks with low risk scores focused on companies with lower risk scores and sturdier profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com