


EN
Lundin Mining (TSX:LUN) Pushes Copper Growth On While Fair Value Debate Builds
Lundin Mining (TSX:LUN) is in focus after moving ahead with several growth projects, including an additional ball mill at Chapada linked to the Saúva project, as well as fresh copper interests in Chile and Argentina.
The recent project approvals arrive after a mixed stretch for Lundin Mining’s stock, with the share price down 9.77% over 30 days and 15.75% over 90 days, yet still sitting at CA$31.67 and carrying a 1-year total shareholder return of 40.05%, which indicates momentum building over a longer window.
Scan how Lundin Mining’s latest copper moves compare with other producers by checking the 16 top copper producer stocks for ideas that fit a similar theme in your portfolio.
Lundin Mining trades at a meaningful discount to analyst targets and implied fair value, even after the recent pullback. Is the market correctly pricing execution risk on these copper projects, or overstating it?
Most Popular Narrative: 26% Undervalued
Lundin Mining’s most followed narrative pegs fair value at about CA$43.02, compared with the last close at CA$31.67. This frames the current copper project news against a valuation gap built on long run assumptions and execution risk.
Lundin Mining is advancing the multi stage build out of the Vicuña district, with fiscal stability, provincial royalty arrangements and national power line approvals already secured. This positions the company to bring a large copper, gold and silver resource base into production and potentially lift long term revenue and free cash flow once the development moves into execution.
See why 34 investors see Lundin Mining as 26% undervalued.
Result: Fair Value of CA$43.02 (UNDERVALUED)
Still, the Lundin Mining story can be knocked off course if country risks in South America or repeat weather disruptions in Chile raise costs and interrupt output.
Find out about the key risks to this Lundin Mining narrative.
Another View: Lundin Mining Through The P/E Lens
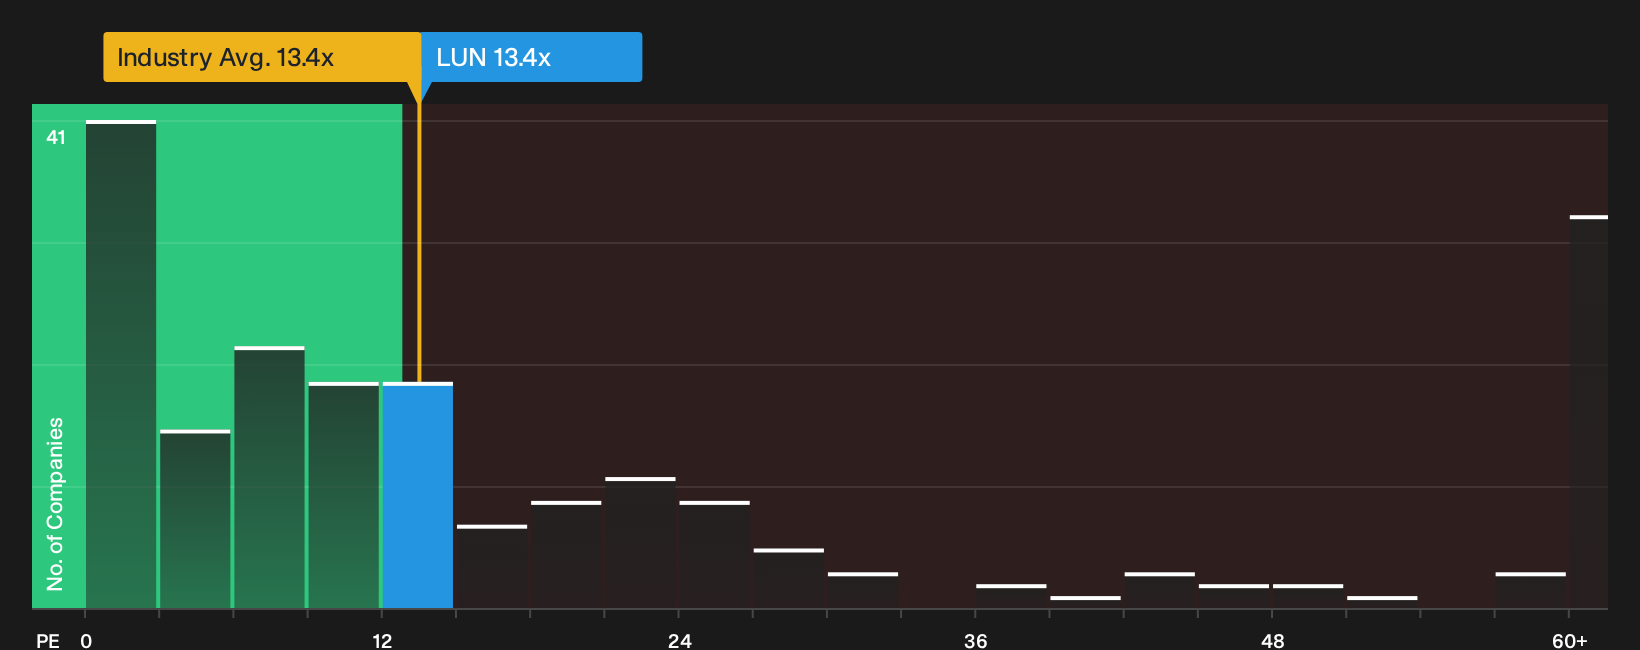
On multiples, Lundin Mining tells a different story. The shares trade on a P/E of 14.3x, which is slightly higher than the Canadian Metals and Mining industry on 13.4x, yet well below a peer average of 38x and above a fair ratio of 12.1x that the market could move toward. That mix points to some valuation risk if sentiment cools, but also scope for re rating if the peer group remains richly priced. Which side of that trade are you really betting on?
For a closer look at how this ratio based view stacks up against internal estimates, review the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Feeling torn between the upside story and the copper project risks around Lundin Mining is reasonable. Move quickly, review the data, and stress test both sides of the argument using the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Lundin Mining?
If Lundin Mining has sharpened your focus on where risk and reward really meet, do not stop here. Use fresh screens, compare opportunities, and pressure test your watchlist with data driven filters.
- Target potential mispricing by checking companies flagged in the 5 high quality undervalued stocks and see which ones line up with your return expectations.
- Prioritise resilience by scanning the 9 resilient stocks with low risk scores and focus on businesses where risk scores stay firmly under control.
- Strengthen your core holdings by reviewing the list of solid balance sheet and fundamentals (6 results) and concentrate on firms backed by sturdier financial foundations.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com