


EN
How Earnings Beat At Covista Stock Has Changed Its Investment Story
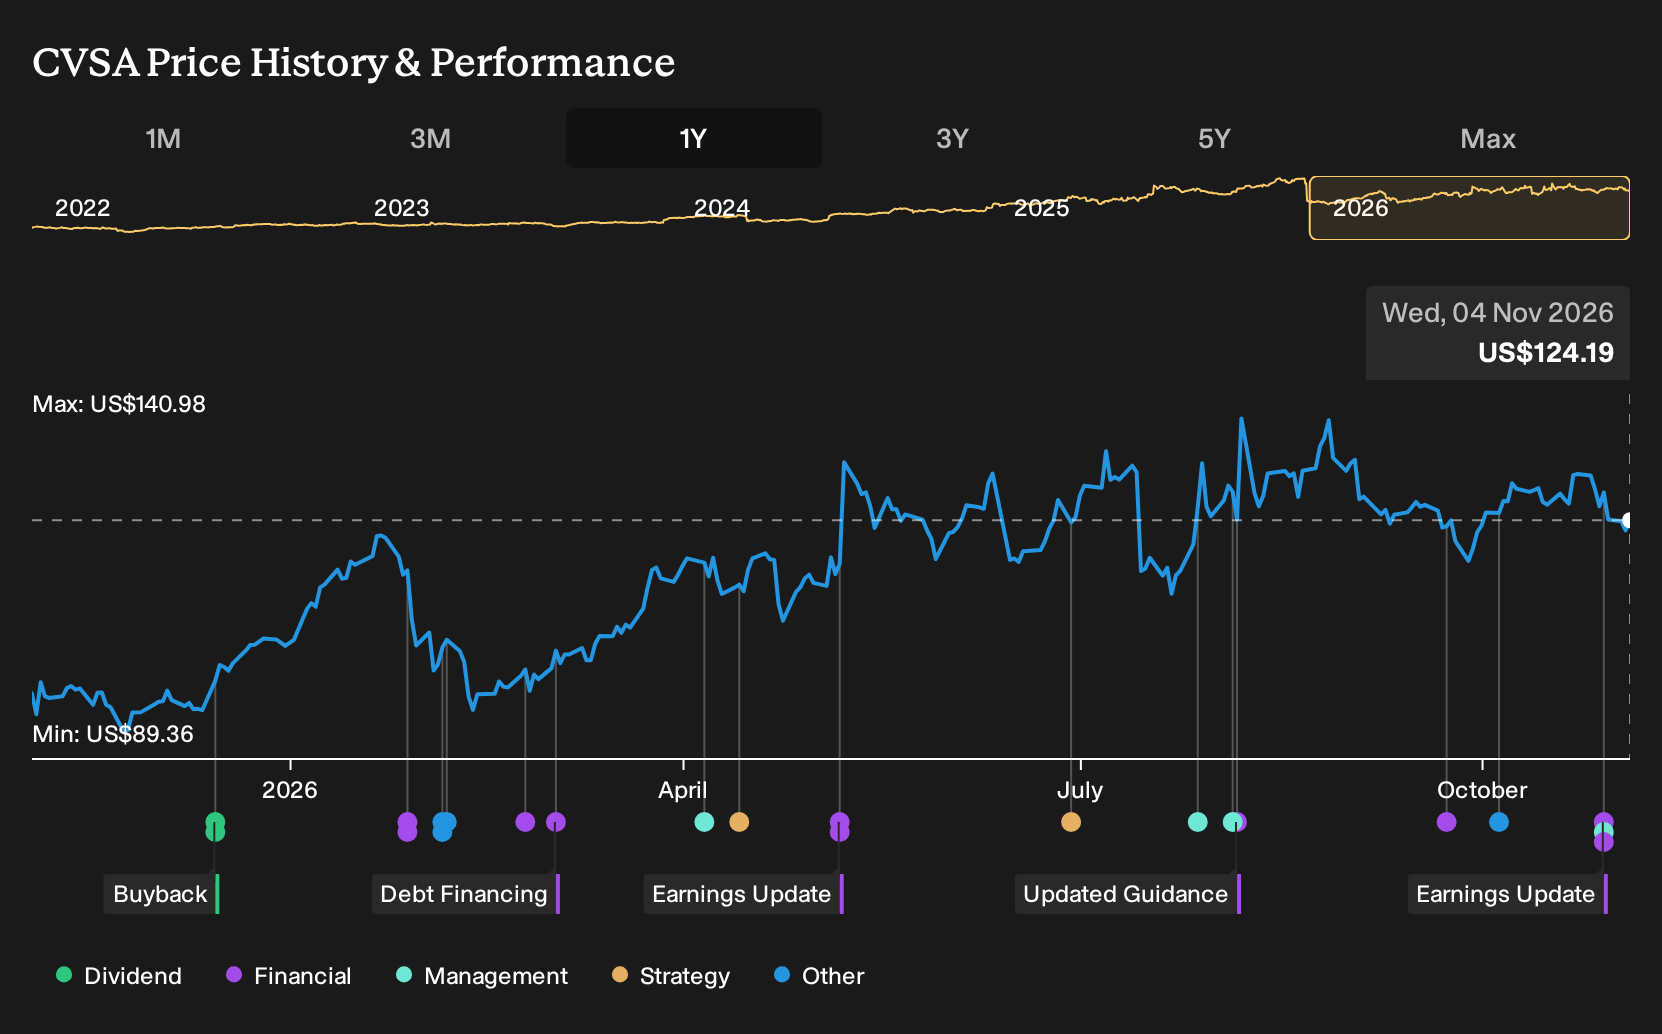
- Covista reported first quarter 2026 sales of US$511.53 million and net income of US$67.43 million, raised its 2027 revenue outlook to a range of US$2.06 billion to US$2.095 billion, and continued an active buyback that has retired 4.41% of shares since late 2025.
- The combination of stronger healthcare program enrollment, higher earnings guidance and ongoing share repurchases highlights how Covista is using current cash generation to fund growth initiatives while also reducing its share count.
- Next, the focus will be on how Covista's raised guidance, supported by healthcare enrollment strength, could reshape the broader investment narrative.
See how Covista's guidance upgrade and buyback program compare with other education and training stocks that screens flag as momentum candidates in 19 high quality undiscovered gems.
Covista Investment Narrative Recap
To own Covista, you need to be comfortable with a healthcare focused education model that leans on steady enrollment in nursing, medical and behavioral health programs, plus scaled online learning at Walden and Chamberlain. The raised 2027 revenue range and solid first quarter figures keep the near term demand story intact, with healthcare enrollment still the key short term swing factor.
The biggest immediate catalyst is whether recent campus expansions, AI enabled classroom tools and employer linked programs sustain that enrollment strength without eroding margins. The largest risk remains any disruption to student financing or a reset in online learning preferences, which could weigh on utilization, cash generation and the capacity to keep funding growth and buybacks.
The most relevant update here is Covista lifting its 2027 revenue outlook to US$2.06b to US$2.095b from US$2.05b to US$2.09b. That is a modest shift. It aligns with first quarter sales of US$511.53 million and net income of US$67.43 million, which show the current model supporting both scale and profitability.
This guidance tweak matters mainly because it sits alongside an active buyback and ongoing investment in technology and capacity. The combination gives you a clear operational checklist over the next year: watch enrollment trends in healthcare programs, any regulatory moves on student lending, and whether cash generation remains strong enough to keep funding both new programs and share repurchases.
Covista's narrative projects US$2.4b revenue and US$362.8 million earnings by 2029. This projection is based on an assumed 7.4% yearly revenue growth and an earnings increase of about US$95 million from current earnings of US$267.4 million.
Uncover why Covista's fair value signals a 28% potential upside to its current price. This discount may not last much longer.
Exploring Other Perspectives
One alternate view on Covista leans heavily on margin risk. The most cautious analysts were penciling in revenue of about US$2.4b and earnings near US$353.2 million by 2029 before this guidance and CFO transition, paired with a lower 14.2x P/E. That outlook is more restrained, so consider using it to pressure test your own assumptions.
Explore 2 other Covista fair value estimates, including one that suggests it could be worth just $159.00!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Covista research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Covista. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Covista's overall financial health at a glance.
Looking for more Covista sized investment ideas?
If the Covista story has sharpened your thinking, use that momentum to stress test other opportunities with the Simply Wall St Screener before committing fresh capital.
- For investors who want quality on sale, filter for companies that screen as attractively priced relative to their fundamentals using the 33 high quality undervalued stocks.
- If income and resilience matter most to you, narrow the field to businesses that have paid out at least a 5% yield and appear built to sustain it through the 5 dividend fortresses.
- When capital preservation is the priority, focus on businesses that score well on balance sheet strength and fundamentals by starting with the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com