


EN
How Earnings Cuts Will Impact BCE (TSX:BCE) Investors
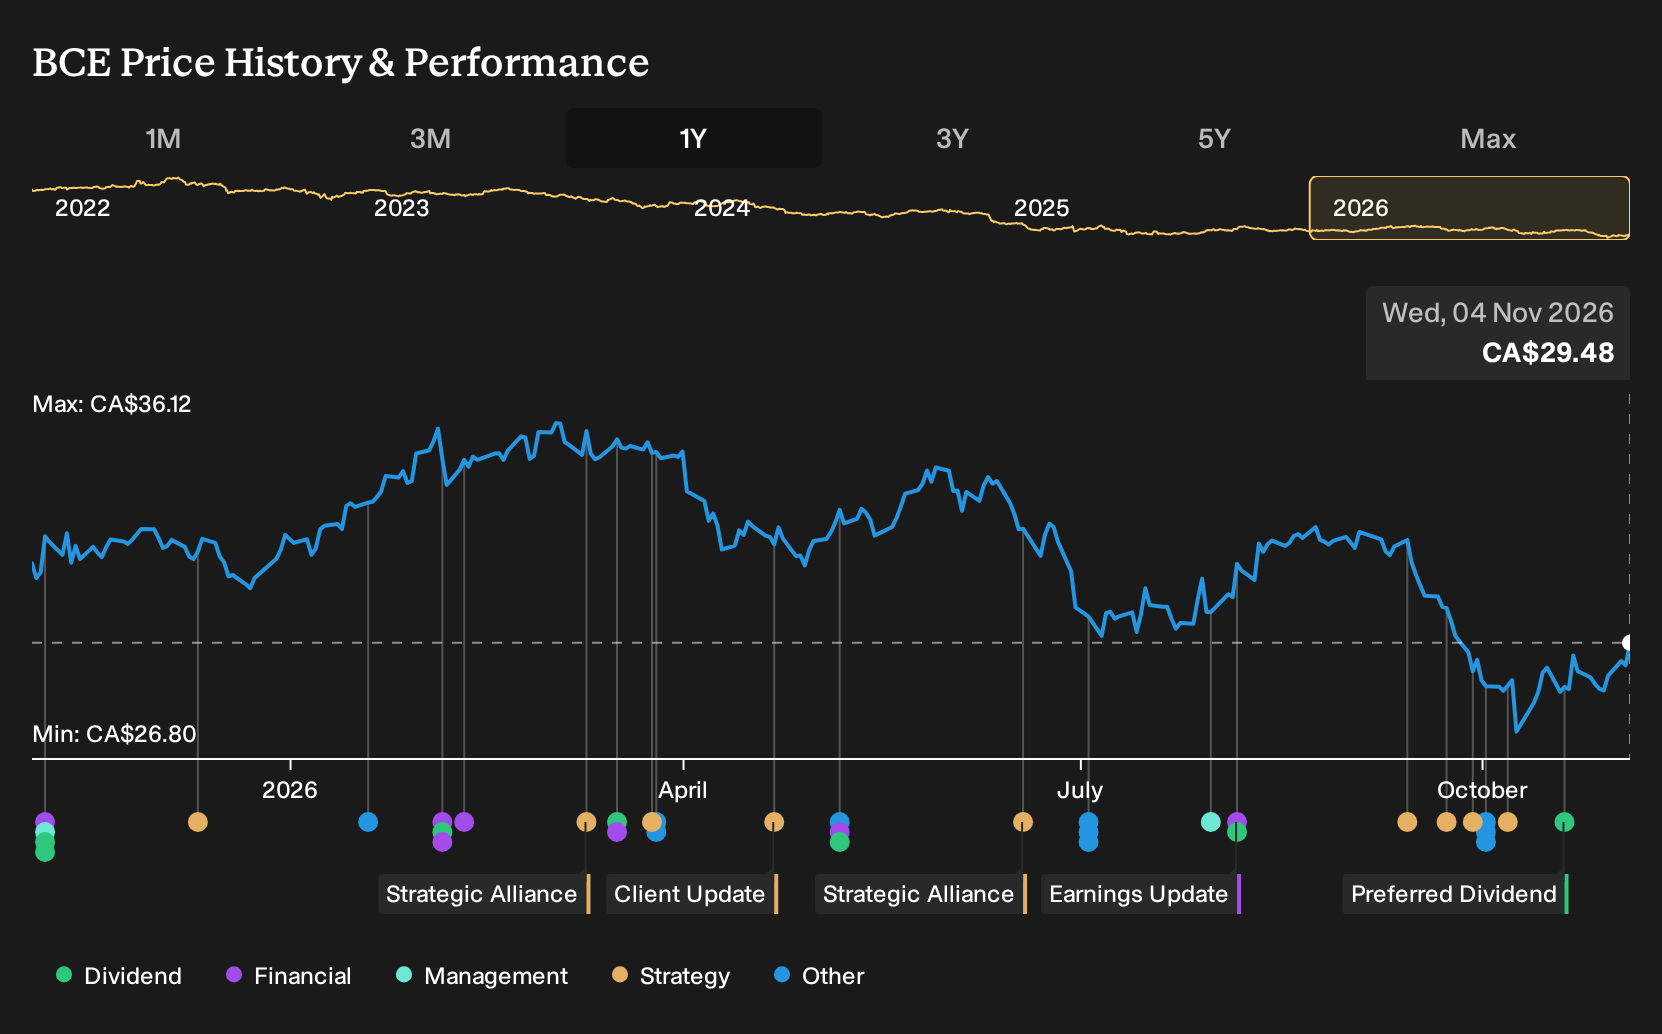
- BCE is heading into its next quarterly earnings release with analysts expecting lower earnings per share and revenue compared with the same period last year, alongside softer mobile subscriber activation and net additions metrics.
- The focus on forecasted declines in BCE’s core telecom earnings power highlights how sensitive the business remains to shifts in subscriber growth and usage patterns.
- We will look at how BCE’s investment narrative is tested by anticipated earnings pressure and weaker forecast mobile subscriber activations.
Balance your view on BCE by scanning a curated set of telecom peers and income plays screened as 3 dividend fortresses before this earnings season reshapes expectations.
BCE Investment Narrative Recap
To own BCE, you need to be comfortable with a telecom and media group that is leaning hard into fibre, data centres and AI focused enterprise services, while its traditional wireless metrics come under pressure. The latest expectation of softer earnings and weaker mobile activations tests that thesis but does not fundamentally change it unless subscriber softness turns into a sustained trend.
The near term swing factor is still how quickly wireless and internet cash flows can support heavier spending on Bell AI Fabric, Ziply Fiber and fibre to the home. The biggest risk is that rising capex and already pressured wireless ARPU combine with any earnings shortfall, leaving less room to fund growth, pay down debt and keep the dividend plan intact.
Recent communication around the 300 MW Saskatchewan AI data centre in Bell AI Fabric matters most against this earnings backdrop. Management has framed this facility as fully contracted with a targeted contribution of about CA$500m of revenue, CA$400m of EBITDA and over CA$250m of free cash flow at full run rate, which gives BCE another leg of contracted economics as telecom results soften.
For you as a shareholder, that project sits right beside this quarter’s wireless trends as a key catalyst. Execution timing, setup fees and prepayments become important because capex intensity is expected to be around 20% in 2026. Any delay in those contracted returns would make weaker mobile activations and ARPU pressure more of a strain on near term cash generation.
BCE's analyst narrative points to forecast revenue of CA$25.6b and earnings of CA$3.0b by 2029, based on revenue growth of 1.1% a year and an earnings decline of CA$3.3b from current earnings of CA$6.3b.
Uncover how BCE's fair value indicates a 26% potential upside to its current price before the discount closes.
Exploring Other Perspectives
You might see BCE very differently if you lean into the bullish story around the Saskatchewan AI data center program. The most optimistic analysts were pencilling in revenue of about CA$26.6b and earnings near CA$2.7b by 2029, and a higher 18.7x P/E, before this earnings update. That gap in expectations shows how widely views can differ, so it can help to compare several narratives and decide which assumptions feel closest to your own.
Explore 4 other BCE fair value estimates, including one that suggests as much as 49% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your research and judgment.
- A great starting point for your BCE research is our analysis highlighting 4 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for BCE. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate BCE's overall financial health at a glance.
Looking for more investment ideas beyond BCE?
If the current setup for BCE has sharpened your process, use that same mindset to scan a wider field of opportunities with the Simply Wall St Screener before the next wave of earnings headlines lands.
- For readers who care most about resilience, start with a curated set of companies that score well on financial strength and steady balance sheets through the 9 resilient stocks with low risk scores.
- If you prefer quality at a sensible entry point, focus on businesses that pair solid fundamentals with attractive pricing by running the 5 high quality undervalued stocks.
- Income focused investors can broaden their watchlist beyond BCE by zeroing in on stocks offering higher yields with defensive characteristics using the 3 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com