


EN
DeSoto Resources (ASX:DES) Will Have To Spend Its Cash Wisely
Even when a business is losing money, it's possible for shareholders to make money if they buy a good business at the right price. For example, although software-as-a-service business Salesforce.com lost money for years while it grew recurring revenue, if you held shares since 2005, you'd have done very well indeed. Nonetheless, only a fool would ignore the risk that a loss making company burns through its cash too quickly.
So should DeSoto Resources (ASX:DES) shareholders be worried about its cash burn? In this report, we will consider the company's annual negative free cash flow, henceforth referring to it as the 'cash burn'. Let's start with an examination of the business' cash, relative to its cash burn.
How Long Is DeSoto Resources' Cash Runway?
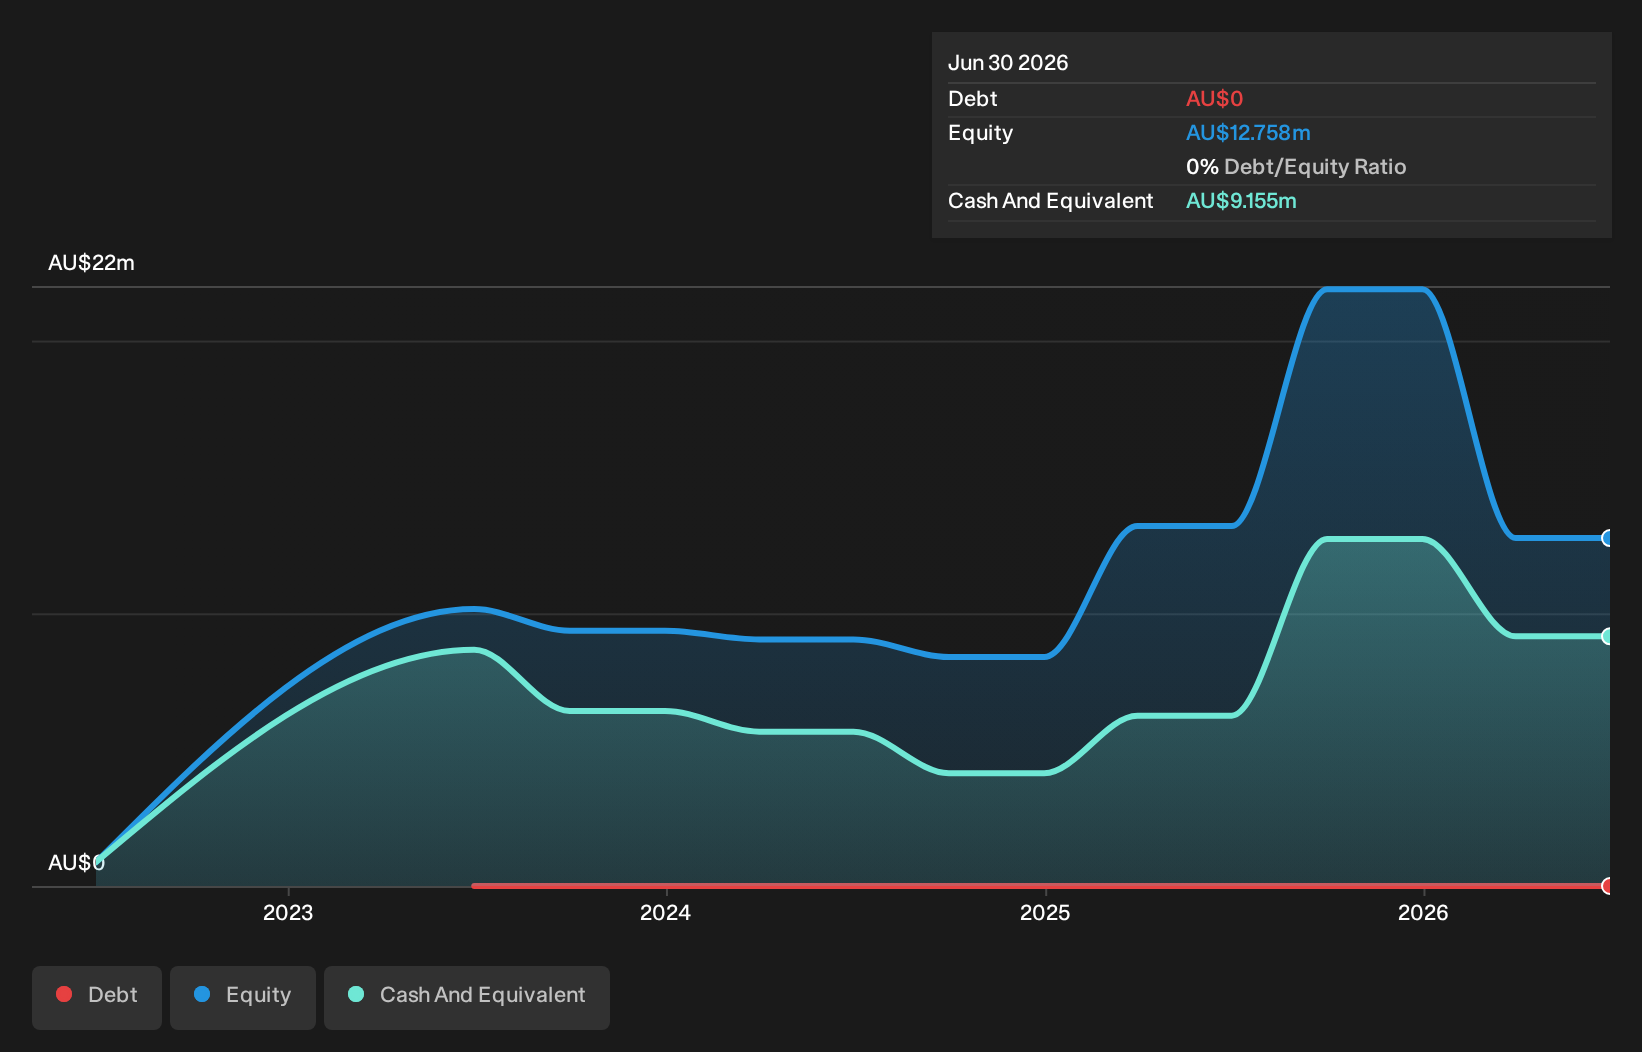
A cash runway is defined as the length of time it would take a company to run out of money if it kept spending at its current rate of cash burn. When DeSoto Resources last reported its June 2026 balance sheet in September 2026, it had zero debt and cash worth AU$9.2m. In the last year, its cash burn was AU$9.9m. That means it had a cash runway of around 11 months as of June 2026. To be frank, this kind of short runway puts us on edge, as it indicates the company must reduce its cash burn significantly, or else raise cash imminently. You can see how its cash balance has changed over time in the image below.
View our latest analysis for DeSoto Resources
How Is DeSoto Resources' Cash Burn Changing Over Time?
Although DeSoto Resources reported revenue of AU$3.0k last year, it didn't actually have any revenue from operations. That means we consider it a pre-revenue business, and we will focus our growth analysis on cash burn, for now. In fact, it ramped its spending strongly over the last year, increasing cash burn by 170%. That sort of spending growth rate can't continue for very long before it causes balance sheet weakness, generally speaking. DeSoto Resources makes us a little nervous due to its lack of substantial operating revenue. We prefer most of the stocks on this list of stocks that analysts expect to grow.
How Hard Would It Be For DeSoto Resources To Raise More Cash For Growth?
Since its cash burn is moving in the wrong direction, DeSoto Resources shareholders may wish to think ahead to when the company may need to raise more cash. Generally speaking, a listed business can raise new cash through issuing shares or taking on debt. Commonly, a business will sell new shares in itself to raise cash and drive growth. By comparing a company's annual cash burn to its total market capitalisation, we can estimate roughly how many shares it would have to issue in order to run the company for another year (at the same burn rate).
DeSoto Resources' cash burn of AU$9.9m is about 33% of its AU$30m market capitalisation. That's not insignificant, and if the company had to sell enough shares to fund another year's growth at the current share price, you'd likely witness fairly costly dilution.
So, Should We Worry About DeSoto Resources' Cash Burn?
DeSoto Resources is not in a great position when it comes to its cash burn situation. While its cash runway wasn't too bad, its increasing cash burn does leave us rather nervous. After looking at that range of measures, we think shareholders should be extremely attentive to how the company is using its cash, as the cash burn makes us uncomfortable. On another note, DeSoto Resources has 6 warning signs (and 3 which make us uncomfortable) we think you should know about.
If you would prefer to check out another company with better fundamentals, then do not miss this free list of interesting companies, that have HIGH return on equity and low debt or this list of stocks which are all forecast to grow.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.