


EN
Whitbread (LSE:WTB) Is Back In The Spotlight, But Why?
Whitbread (LSE:WTB) is heading into its 9 November general meeting with governance firmly in focus after ISS and PIRC opposed Corvex’s proposed board nominee, while Glass Lewis backed the candidate.
Whitbread’s governance debate is landing at a time when momentum in the share price has picked up, with a 30 day share price return of 16.1% and a 90 day gain of 11.4%, even though the 3 year total shareholder return is still down 5.1%.
Scan how Whitbread's governance story compares with other companies showing strong balance sheets and fundamentals in our curated list of solid balance sheet and fundamentals (10 results) as activism and board debates pick up pace.
Whitbread shares now trade only modestly below both intrinsic value estimates and analyst targets after the recent jump. Is that small discount a genuine margin of safety, or a sign the market still sees unresolved risks?
Most Popular Narrative: 0% Overvalued
Whitbread last closed at £28.17, almost exactly in line with the widely followed fair value estimate of £28.13 that uses a 12.68% discount rate. As a result, the debate now shifts from headline valuation to whether the long term plan can actually deliver the earnings path that model implies.
The extended Accelerating Growth Plan that converts 197 remaining branded restaurants into hotel capacity, adds around 3,000 new extension rooms and targets about £100m of incremental profit before tax by FY31 on £660m of spend is set up to support revenue growth and higher return on capital.
See why 31 investors see Whitbread as 0% overvalued.
Result: Fair Value of £28.13 (ABOUT RIGHT)
Still, the story around Whitbread could change quickly if higher UK business rates bite harder than planned or if German returns lag the ambitions built into current models.
Find out about the key risks to this Whitbread narrative.
Another View On Whitbread’s Valuation
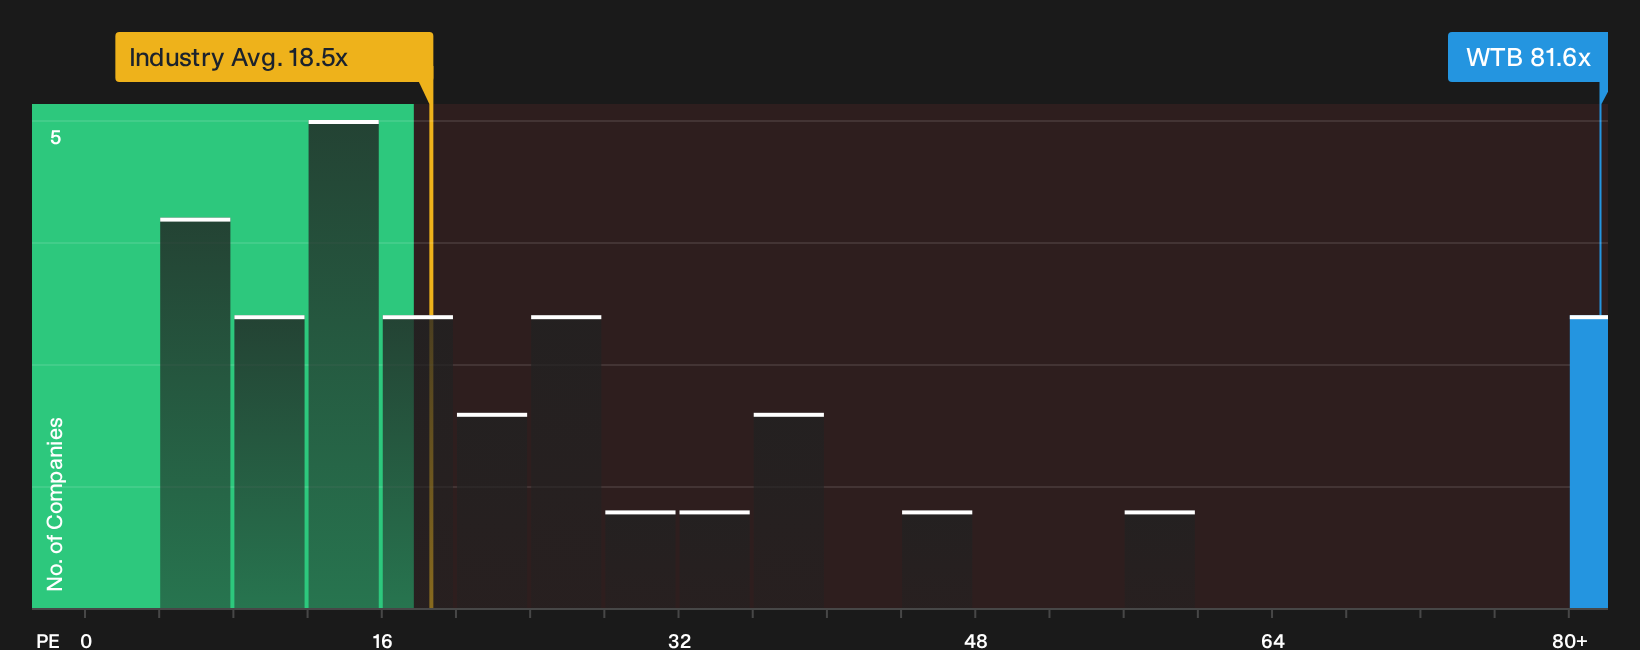
On simple earnings multiples, Whitbread screens very differently. The shares trade on a P/E of 81.6x, compared with 18.5x for the UK Hospitality sector, 15.7x for peers and a fair ratio of 31.1x that the market could move towards. That gap points to meaningful valuation risk if sentiment cools or earnings fall short.
When one framework signals fair value and another flags a rich multiple, which signal do you trust more for your own hurdle rate and time horizon, and what would need to change for your view to shift?
See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Whitbread for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 14 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Whitbread’s outlook can be useful, because disagreement forces you to test the numbers yourself and move quickly to a clear stance. Before you settle on your own call, weigh how the 2 key rewards and 3 important warning signs fit with your thesis.
Looking for more investment ideas beyond Whitbread?
If Whitbread has sharpened your thinking, use that momentum to compare it with other opportunities and pressure test where your next pound really works hardest.
- Target long term value compounding by checking companies that combine quality fundamentals with attractive pricing through the 14 high quality undervalued stocks.
- Strengthen your income game by reviewing companies that feature resilient payouts and higher yields inside the 3 dividend fortresses.
- Dial down risk by focusing on resilient balance sheets and robust financial profiles using the 5 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com