


EN
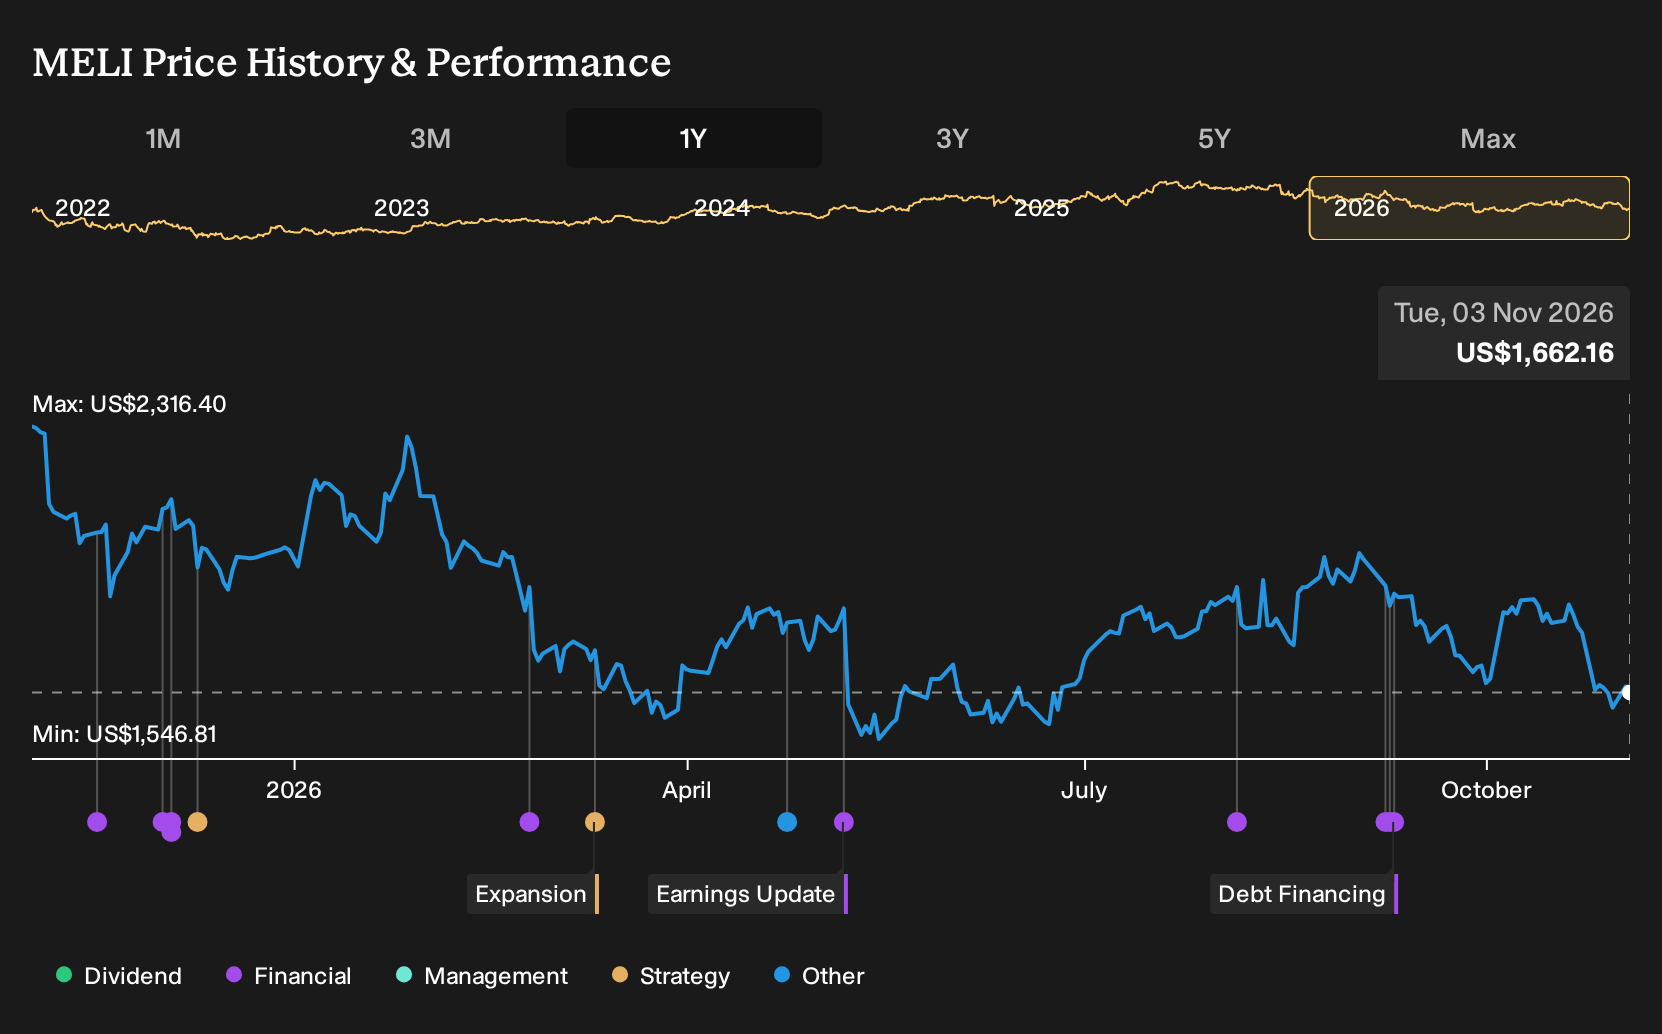
MercadoLibre Stock After Q3 Earnings Faces Brazil Margin Test
- MercadoLibre confirmed that it released third quarter 2026 results on November 4, with management reiterating that operating margins are not expected to improve materially in the near term as the group continues heavy investment in logistics and credit expansion, particularly in Brazil.
- The earnings update puts a spotlight on MercadoLibre's decision to accept thinner profitability while Brazil remains the largest revenue contributor and while its growing credit and free shipping programs reshape the cost structure of the overall ecosystem.
- In this context, we will examine how MercadoLibre's investment narrative holds up as Q3 margin pressure collides with its Brazil focused growth strategy.
Compare MercadoLibre's trade off between growth and margin pressure with other companies pursuing similar expansion by scanning our curated list of 19 high quality undiscovered gems with strong fundamentals that are still under the radar.
MercadoLibre Investment Narrative Recap
To own MercadoLibre, you need to trust that heavy spending on Brazil logistics, free shipping and credit will eventually support healthier unit economics, even with management signaling that operating margins are unlikely to improve much in the near term. The near-term catalyst is simple: investors are watching for any sign that revenue and user activity can stay strong while margins stay compressed.
The main risk right now sits in the growing credit book and the choice to run with thinner profitability. If credit losses or provisions worsen, or if the extra volume from fee cuts and shipping perks in Brazil does not offset higher costs, earnings and net margins could stay under pressure longer than many shareholders are comfortable with.
The freshest piece of information is management’s Q3 commentary that operating margins are not expected to improve materially for now as MercadoLibre doubles down on logistics and credit, especially in Brazil. For you, that frames the next few quarters. The story hinges less on near-term profit growth and more on how efficiently the ecosystem can scale.
This update ties directly into existing catalysts. Lower free shipping thresholds in Brazil and fee reductions are linked to higher items per buyer and purchase frequency, while Mercado Pago’s expanding credit portfolio is already large, at about US$16.4b. The opportunity is that these investments deepen engagement. The risk is that high funding needs and any deterioration in asset quality could strain future earnings and limit reinvestment flexibility.
What The Current Forecasts Assume For MercadoLibre
MercadoLibre's narrative projects US$75.8b in revenue and US$5.2b in earnings by 2029, based on the analyst valuation framework. This implies revenue growth of about 29.1% per year and an earnings increase of US$3.3b from US$1.9b today to the US$5.2b consensus figure.
Uncover why MercadoLibre's fair value indicates a 36% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
You can also frame MercadoLibre through the most bullish lens, where the key swing factor is AI driven efficiency rather than Brazil credit risk. The highest analysts were penciling in US$82.6b in revenue and US$6.1b in earnings by 2029, before this Q3 update. That optimism may shift, so compare these brighter forecasts with other viewpoints.
Explore 16 other MercadoLibre fair value estimates, including one that suggests as much as 101% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Remember that extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your MercadoLibre research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for MercadoLibre. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easier to evaluate MercadoLibre's overall financial health at a glance.
Looking For More Ideas Beyond MercadoLibre?
Once you have a view on MercadoLibre, it can help to widen the lens and compare it with other businesses that offer different mixes of risk, quality and income potential.
- If capital preservation comes first for you, start with a basket of companies that score well on resilience by reviewing 30 resilient stocks with low risk scores and see which ones match your comfort level.
- Income focused investors can scan for reliable cash generators by filtering for 4 dividend fortresses and checking which pay-out profiles line up with their target yield.
- For those hunting for early opportunities with solid foundations, look through a carefully curated set of under-the-radar businesses via 19 high quality undiscovered gems that already show strong fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com