


EN
Pearson (LSE:PSON) Expands Digital Learning Push As Fair Value Debate Stays Open
Pearson (LSE:PSON) has been busy, announcing fresh digital learning deals with CPA Canada, showcasing generative AI tools in Thailand, and partnering with WorldSkills Australia, while reshaping leadership in its US higher education arm.
Pearson’s recent education partnerships and AI initiatives have landed against a strong run in the shares, with the latest share price at £13.17 and a year to date share price return of 29.18%, supported by a 1 year total shareholder return of 28.18% and a 5 year total shareholder return of 134.04%. This suggests momentum has been building rather than fading.
Scan beyond Pearson and see how other education and AI focused players are positioned with our curated list of 41 profitable AI stocks that aren't just burning cash in the current market.
Bulls see Pearson’s AI partnerships and fresh digital deals as proof the rally has room to run. Sceptics point to valuation risk after a sharp rise. Which case do the numbers lean toward as you weigh the current price?
Most Popular Narrative: 2% Overvalued
The most followed valuation story on Pearson pitches a fair value of £12.89 against the latest share price of £13.17, which places the stock slightly above that anchor and shifts attention toward execution risk rather than deep value arguments.
The main thing that has to go right is that Pearson successfully executes its portfolio simplification and customer led reorganisation, while scaling enterprise and virtual offerings fast enough to offset ongoing pressure in English testing and parts of Higher Education.
The numbers and recent broker downgrades on valuation grounds imply that Pearson's current share price already prices in much of the near term operational progress. Future returns therefore depend heavily on continued delivery against the mid single digit growth and margin expansion ambitions.
See why 18 investors see Pearson as 2% overvalued.
Result: Fair Value of £12.89 (OVERVALUED)
Still, the Pearson story can wobble if English Language Learning and parts of Higher Education stay under pressure, or if FX swings unsettle reported earnings and cash flow.
Find out about the key risks to this Pearson narrative.
Another View: Pearson Through The Cash Flow Lens
The story shifts when you swap analyst targets for the SWS DCF model. On that framework, Pearson at £13.17 sits below an estimated future cash flow value of £14.40, which points to an undervalued reading rather than an already full price. Which signal do you put more weight on today?
For a clearer sense of how this cash flow driven view is built, and how sensitive it is to the inputs you care about most, take a closer look at the Look into how the SWS DCF model arrives at its fair value.
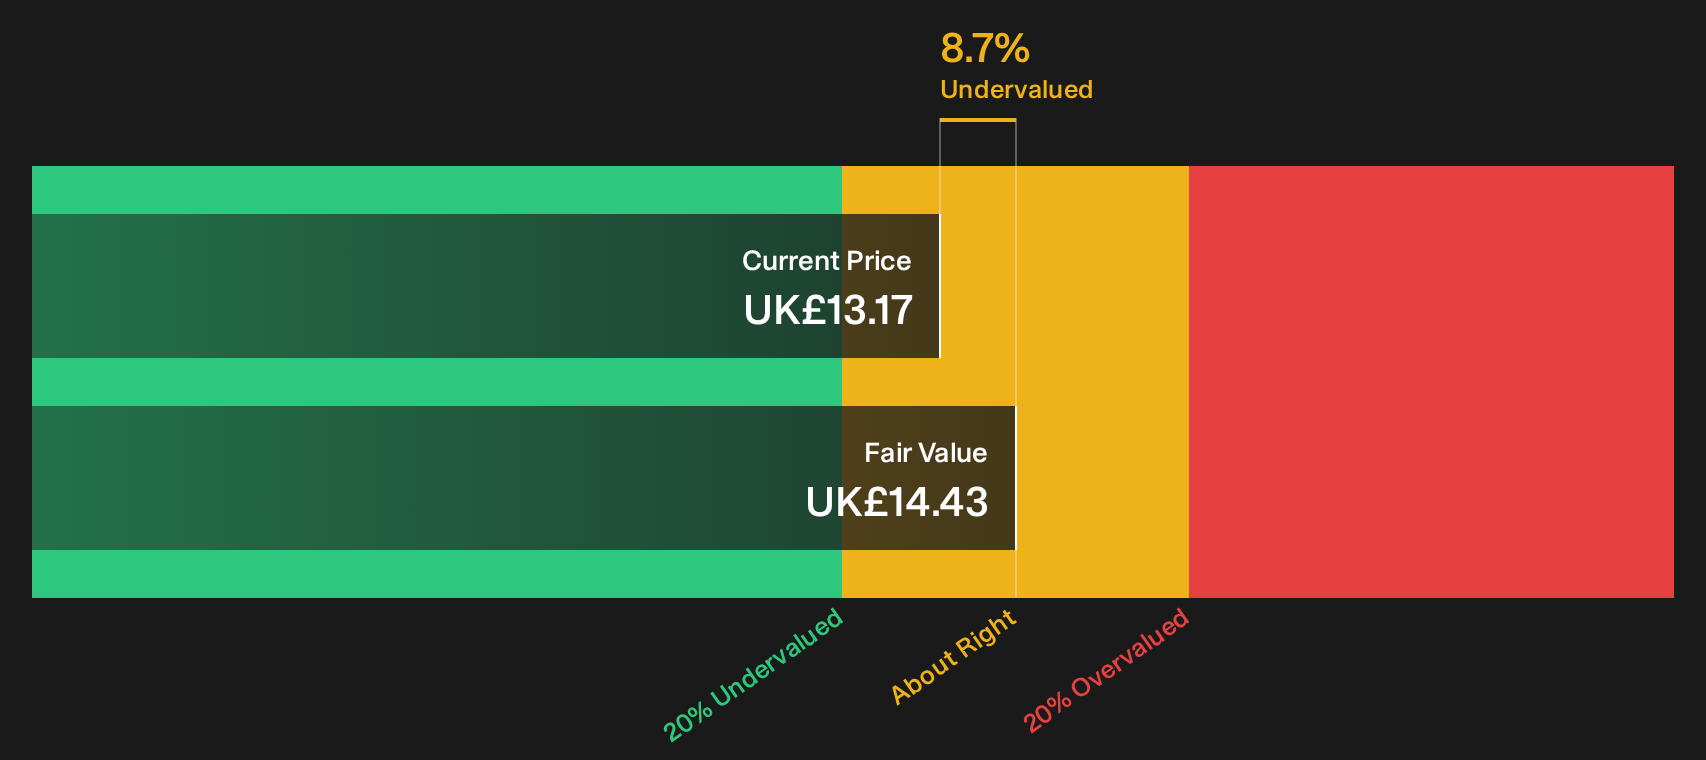
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Pearson for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 14 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment across Pearson's story is mixed, and that is exactly why the data matters. Act quickly, rigorously evaluate the key metrics, and weigh the 2 key rewards
Looking for more Pearson sized investment ideas?
If you stop with Pearson, you miss the broader opportunity set. Use the Simply Wall Street Screener to rapidly surface fresh ideas that match your risk and income goals.
- Target resilient balance sheets and cleaner fundamentals by scanning a list of solid balance sheet and fundamentals (10 results) that keeps financial strength front and centre.
- Hunt for mispriced quality and compare it with Pearson by reviewing a 14 high quality undervalued stocks built around strong cash flows and sensible valuations.
- Lock in potential income ideas before others crowd in by reviewing a focused 3 dividend fortresses geared toward higher yielding, sturdier payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com