


EN
Is Wizz Air Holdings (LSE:WIZZ) Cheap On Bomb Threat News Or Is Risk Priced In?
A bomb threat forced a Wizz Air Holdings (LSE:WIZZ) flight from London to Sofia to divert to Budapest, where a Hungarian fighter jet escort and full security checks drew sharp attention to the airline’s risk profile.
Investors have reacted to the bomb threat in the context of an already volatile year for Wizz Air Holdings, with a 1-day share price return of 4.46% and a 7-day share price return of 7.67%, in contrast with a year to date share price decline of 19.25% and a 5-year total shareholder return that is down 78.23%. This points to short term momentum building against a much tougher long term record as the stock trades at £10.53.
Spot 5 resilient stocks with low risk scores that may handle rare shock events differently to Wizz Air Holdings while still aiming to keep financial risk profiles in tighter check.After a sharp bounce, yet with a share price still far below its multi year peak, the real puzzle on Wizz Air Holdings is whether the bigger upside sits ahead or already lies in the rear view mirror.
Most Popular Narrative: 1% Overvalued
The most followed narrative sees Wizz Air Holdings trading just above its estimated fair value of £10.41, compared with the latest close at £10.53. As a result, the focus shifts from pure upside to whether the business can actually deliver on its operational clean up.
A key requirement is that Wizz Air restores and sustains lower ex fuel unit costs and more reliable operations as grounded aircraft return, older ceo planes exit, and high network churn is brought under control.
The current valuation suggests that the share price already reflects Wizz Air Holdings being fairly valued with successful execution on its cost, growth, and balance sheet plans, rather than reflecting a distressed or highly stretched outcome.
See why 36 investors see Wizz Air Holdings as 1% overvalued.
Result: Fair Value of £10.41 (ABOUT RIGHT)
Still, if aircraft remain grounded for longer or network churn stays high, the central Wizz Air Holdings fair value narrative could quickly lose its footing.
Find out about the key risks to this Wizz Air Holdings narrative.
Another Take On Wizz Air Holdings’ Value
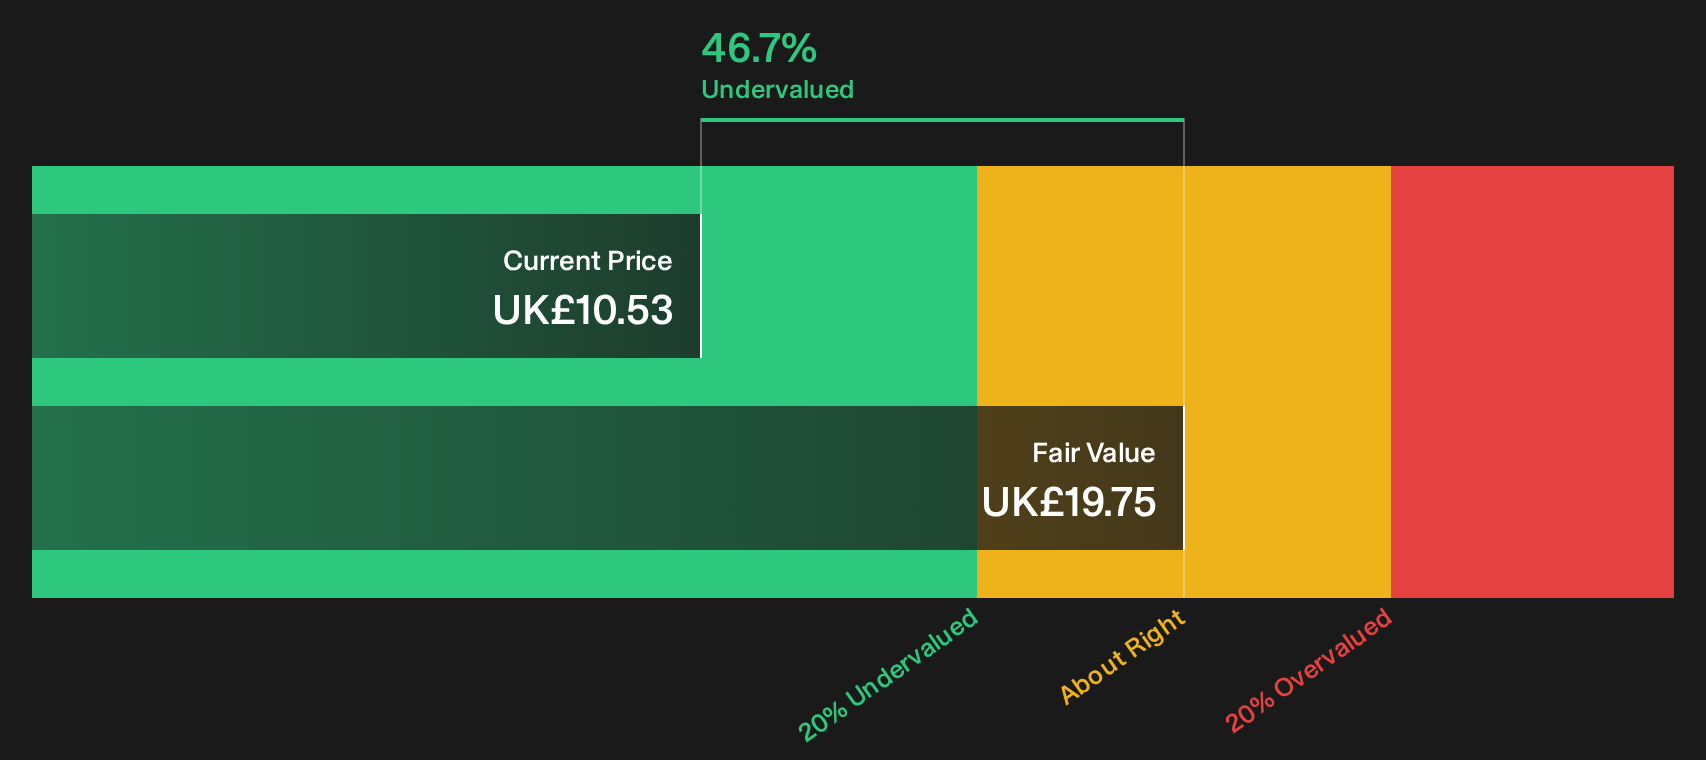
The first view pegs Wizz Air Holdings close to fair value at about £10.41, almost in line with the £10.53 share price. Our DCF model presents a very different picture, with an estimate of £19.78 that indicates the stock trades at a steep discount. This raises a question: which perspective seems more convincing, the current market price or the cash flows implied by the model?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals appear in this story for Wizz Air Holdings, so consider acting promptly, review the data for yourself, and weigh both sides using 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Wizz Air Holdings?
If Wizz Air Holdings has sharpened your focus on risk and reward, broaden your watchlist with a few data driven shortlists built to surface different types of opportunities.
- Target income first and stress test your payout candidates by scanning companies we classify as potential 3 dividend fortresses.
- Hunt for value opportunities and compare them with Wizz Air Holdings by reviewing the current lineup of 14 high quality undervalued stocks.
- Strengthen your capital preservation plan and balance higher risk names with a list of solid balance sheet and fundamentals (10 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com