


EN
Associated British Foods (LSE:ABF) Jumped, What Is Driving Attention Today?
Associated British Foods (LSE:ABF) has kicked off November with full year 2026 results that show higher sales but lower profitability, as Sugar losses, factory closures and softer Primark metrics reshape the investment debate.
The latest results have jolted sentiment towards Associated British Foods, with the share price jumping 6.4% on the day and delivering an 11.6% share price return over the past month, yet the 1-year total shareholder return is still down 5.9%, which suggests recent momentum is building from a weaker long-term base.
Spot emerging consumer and retail opportunities moving on earnings surprises by scanning our hand picked 5 high quality undiscovered gems alongside Associated British Foods.Bulls see Associated British Foods as a mispriced mix of Primark growth plans and diversified food earnings, while bears point to falling profits and sugar losses. Which case does the current valuation actually support?
Most Popular Narrative: 12% Overvalued
Associated British Foods is trading at £20.21 against a widely followed fair value estimate of £17.99, so the latest narrative frames the current price as rich for the earnings and cash flow profile being modeled.
The main thing that has to go right is that Primark's omnichannel rollout and international expansion deliver enough profitable growth to offset Sugar losses and pockets of weaker trading in Grocery.
The current valuation implies investors are pricing Associated British Foods as fairly valued, with solid Primark profitability and balance sheet strength, while still treating Sugar and some Grocery assets as meaningful execution risks.
See why 67 investors see Associated British Foods as 12% overvalued.
Result: Fair Value of £17.99 (OVERVALUED)
Still, the pressure in Sugar and the risk that Primark’s newer services do not lift like-for-like sales enough could easily overturn the current Associated British Foods story.
Find out about the key risks to this Associated British Foods narrative.
Another View: What Multiples Say About Associated British Foods
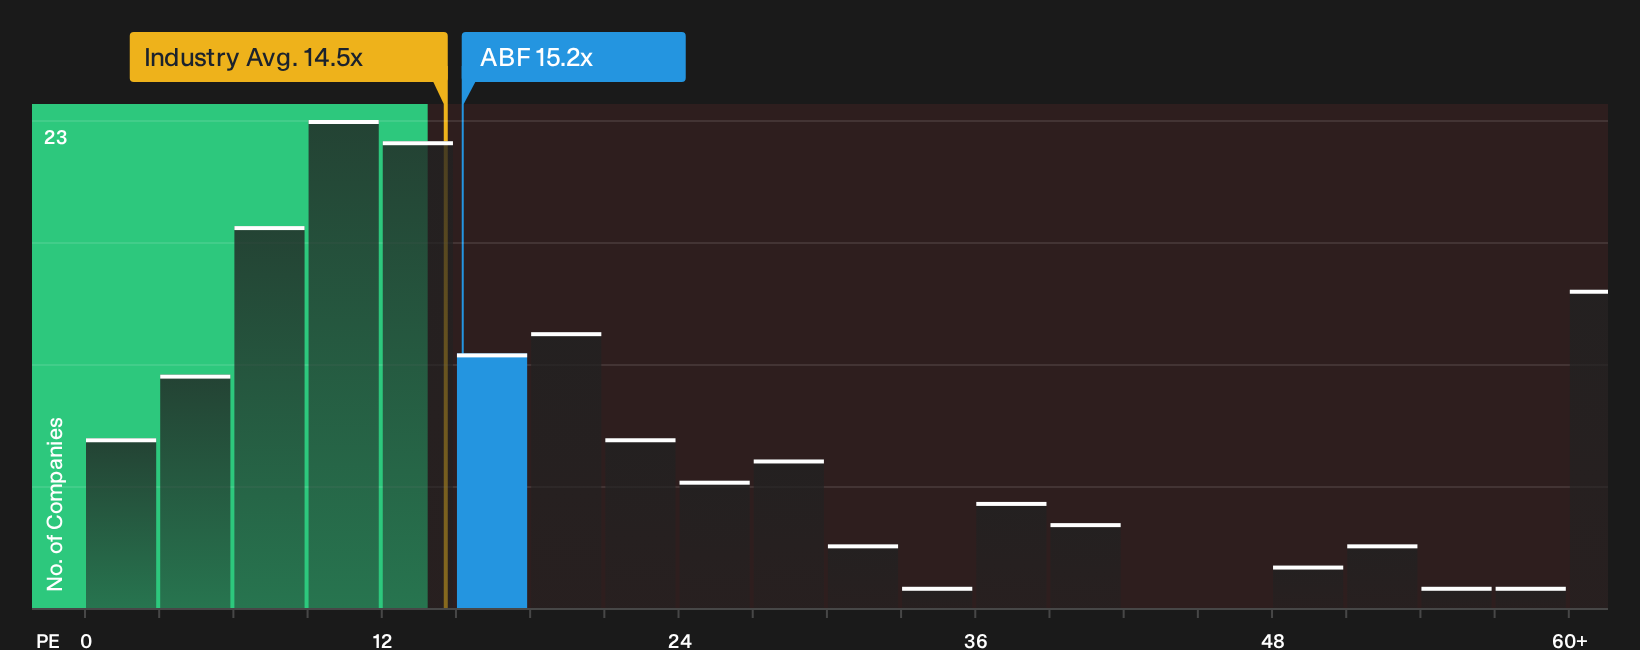
On earnings forecasts and fair value models, Associated British Foods screens as 12% overvalued versus the £17.99 consensus. On simple P/E maths, the picture tilts the other way. ABF trades on 15.2x earnings, which is cheaper than peer averages at 20.4x and also below an estimated fair ratio of 22.7x. That gap points to a risk that sentiment, not just fundamentals, is doing some of the heavy lifting in keeping the share price in check. Which signal do you treat as more important for your own framework?
See what the numbers say about this price, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on valuation can feel messy, and the market rarely waits for full clarity. Move quickly, test the numbers, and weigh both the risk flags and upside signals through 2 key rewards and 1 important warning sign
Looking for more investment ideas beyond Associated British Foods?
If you only focus on Associated British Foods, you could miss other attractive setups that match your risk tolerance and income goals on the Simply Wall St Screener.
- Target resilient performers that aim to protect capital first by filtering for 5 resilient stocks with low risk scores that still clear your quality bar.
- Focus on balance sheet strength and staying power by shortlisting companies from the list of solid balance sheet and fundamentals (10 results) before the crowd catches on.
- Hunt for mispriced opportunities by scanning the 14 high quality undervalued stocks that combine quality fundamentals with prices that have not fully reflected them yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com