


EN
Greatland Resources Heads 3 Australian Undervalued Stocks To Watch
Democrats have just taken control of Congress in the United States, and early trading showed how quickly sentiment can swing when politics collides with markets. Sharp moves in big tech, energy and AI infrastructure remind investors that headlines can push prices around faster than fundamentals change. That can create openings. This article highlights three Australian companies where cash flow potential appears stronger than the current share price suggests.
The three stocks in this article are just a sample pulled from the cash flow screen, with four more companies showing similarly interesting stories that are not covered below and may warrant a closer look for patient value hunters.
If you want to move straight from headlines to hard numbers, use the Undervalued Stocks Based On Cash Flows screener to identify, analyze, and prioritize the highest-conviction ideas for your watchlist.
Greatland Resources (ASX:GGP)
Overview: Greatland Resources is a Subiaco based miner focused on developing the Havieron gold and copper project in Western Australia.
Operations: Greatland Resources currently reports all A$2.26b in revenue from the Telfer-Havieron segment, reflecting a concentrated operating base.
Market Cap: A$6.35b
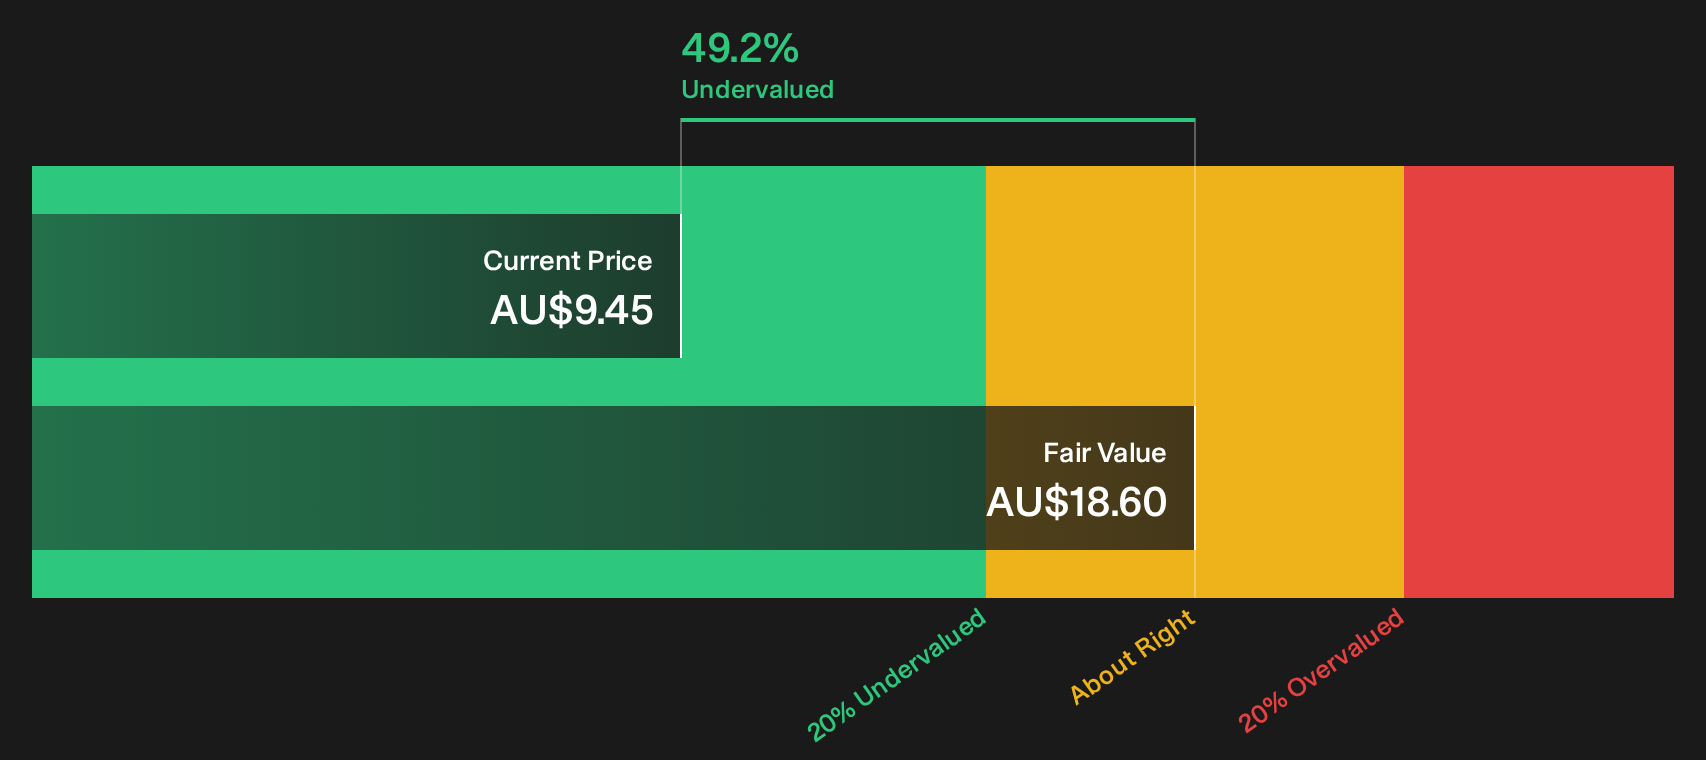
Greatland Resources matters for a cash-flow-focused screen because the Havieron gold copper project links a single major asset to potentially meaningful future production income, which puts real weight behind a discounted cash flow story rather than just speculative drilling results.
"The primary driver of Greatland’s future is the gold price. As a single asset developer moving toward production, it offers significant operational leverage to gold."
What happens when one unresolved pressure on future operating costs and project timing finally meets that leverage will heavily shape eventual cash generation.
That inflection point is exactly what the full narrative for Greatland Resources unpacks, outlining how project timing, leverage to gold and cost risks may be colliding or quietly decoupling.
Woodside Energy Group (ASX:WDS)
Overview: Woodside Energy Group is a Perth based oil and gas producer, with LNG projects providing the main cash flow engine for investors.
Operations: Woodside Energy Group reports around US$7.3b from Australia, US$4.6b from International and US$1.9b from Marketing operations.
Market Cap: A$61.9b
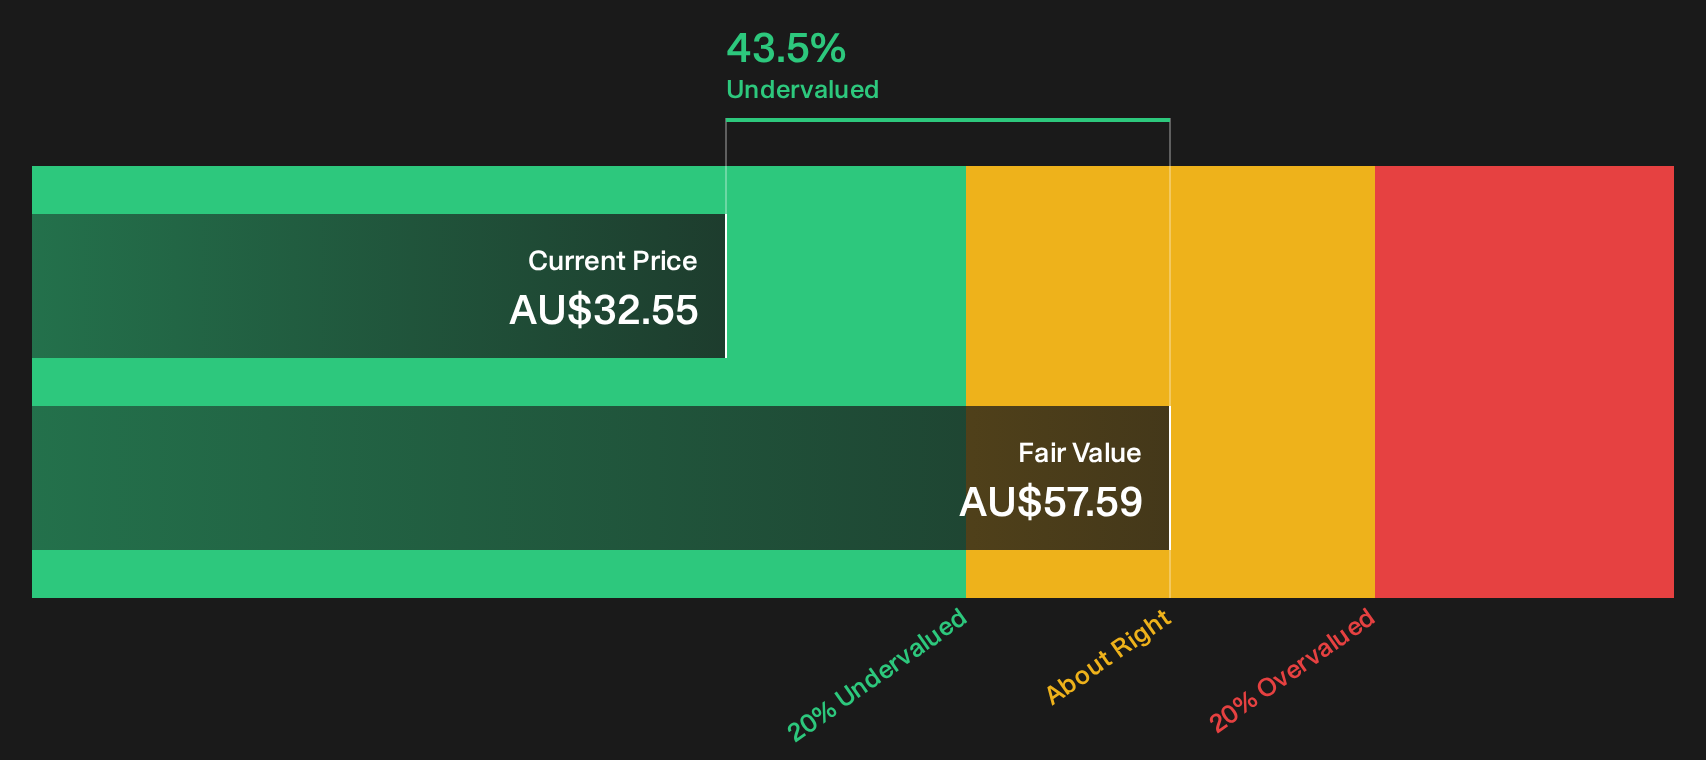
Woodside Energy Group matters for this cash flow screen because its LNG hubs convert long term production contracts into sizeable, modelable cash streams that anchor the SWS DCF work behind the screener.
"The valuation also allows for Scarborough and Pluto Train 2 beginning production as planned, with the project 96% complete and targeting its first LNG cargo in the fourth quarter of 2026. However, net debt had increased to approximately US$9.3 billion by 31 March 2026 as Woodside continued investing in Scarborough, Trion and Louisiana LNG."
What happens if a single key LNG project schedule or cost assumption moves off script will matter a lot for that apparent discount.
When those project assumptions start to shift, the full narrative for Woodside Energy Group shows how Woodside Energy Group’s LNG build out could turn timing risk into accelerating cash flow optionality.
Origin Energy (ASX:ORG)
Overview: Origin Energy is an integrated utility that earns most income from Australian Energy Markets, with its Integrated Gas and LNG operations providing the key link to the undervalued cash flow theme.
Operations: Origin Energy generates about A$15.26b from Energy Markets and A$307m from Integrated Gas, with Australia as its primary revenue base.
Market Cap: A$21.3b
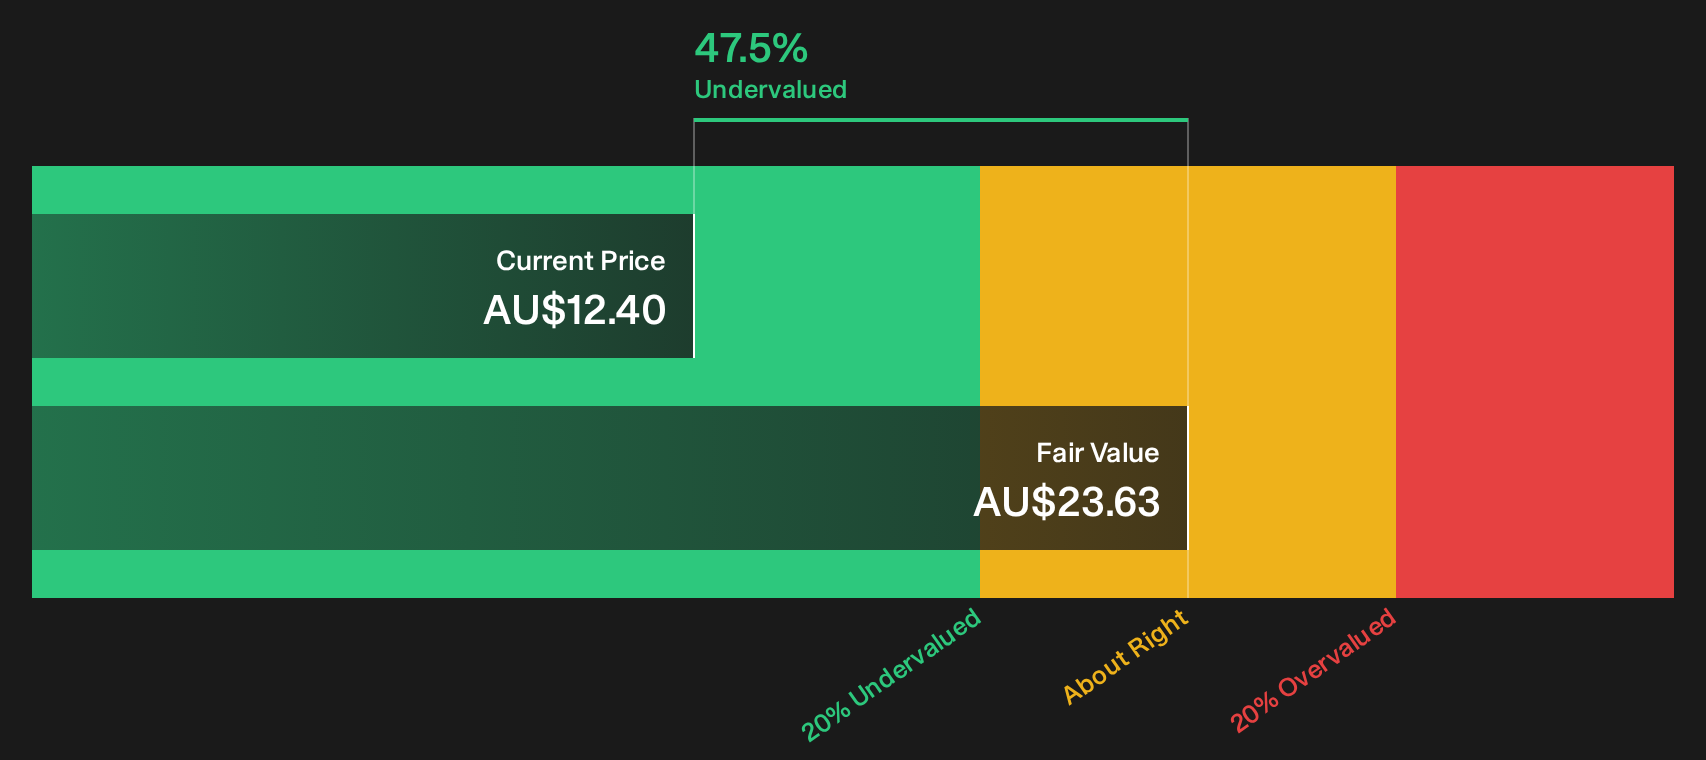
Origin Energy matters for this cash flow screen because its Energy Markets earnings and Integrated Gas LNG streams feed into sizeable, modelable cash generation that can look mispriced when compared with discounted cash flow estimates.
"Continued growth in rooftop solar, home batteries and the 1.6 GW virtual power plant, supported by rising adoption of customer electrification products, can shift more consumption behind the meter and reduce grid supplied volumes."
If one unseen pressure on future Integrated Gas cash distributions and dividend coverage breaks against expectations, it could materially reset how investors view that apparent discount.
That pressure point is exactly what the full narrative for Origin Energy tackles, mapping how Origin Energy’s behind the meter shift could either stall valuations or accelerate a rerating.
Seeking Fresh Alternatives Before They Fly
Markets can move fast when new themes catch a bid, and some ideas can build quiet momentum before they attract wider attention. Review these lists while they may still be developing.
- Target income streams that can help stabilise your portfolio and track payout strength across 5 dividend fortresses before later investors influence yields.
- Look for early movers in automation by scanning 93 robotics and automation stocks while adoption trends may still be developing and sentiment has not fully adjusted.
- Consider potential beneficiaries of infrastructure upgrades and filter 41 power grid technology and infrastructure stocks to see which businesses are exposed to grid spending, rather than reacting only after prices have already moved.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com